MyCard - Contactless Payment
4.0FinanceUpdated October 7, 2026
Screenshots
Pros
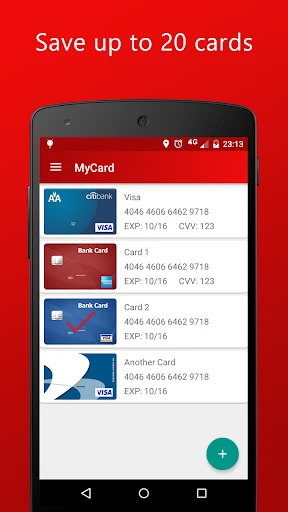
- Supports multiple bank cards.
- User-friendly interface.
- Fast transaction processing.
- Secure payment encryption.
- Works offline for some payments.
Cons
- Limited support for international cards.
- Occasional app freezing issues.
- Requires frequent updates.
- High battery consumption.
- No customer service chat support.
 Analysis By Mobexer
When I think about a payment app, the important question is not only how quickly it can handle a purchase but what happens when the phone, the shop terminal, or the connection gets in the way. MyCard is a finance app from Road Dogs built around using a phone for contactless payments. That focused purpose can suit someone who wants to leave a physical card in a pocket or bag, but it also makes the practical details of setup and payment worth considering before relying on it for every errand.
Where the connection matters
A mobile payment can feel instant at the counter, yet the experience depends on more than a quick tap. Your phone needs to be ready, the shop must accept contactless payments, and the payment setup must be in working order. I would treat a reliable connection as part of preparation rather than assume every step will work regardless of network conditions. If I were about to make a purchase where I could not easily switch payment methods, I would check that MyCard is ready before joining the queue.
That small habit matters most when timing is awkward: paying while carrying shopping, catching a bus, or standing at a busy counter. A phone that is still loading or needs attention can turn a convenient tap into a delay. I would open the app in advance when I had a moment, rather than wait until the cashier is ready. This is not a substitute for understanding how a particular payment flow works, but it is a sensible way to avoid troubleshooting in front of other customers.
Picking the right mobile moments
The clearest use case is a routine in-person purchase at a place that accepts contactless payment. For example, if I stop for groceries after work, I can have the phone accessible before reaching the till and avoid digging around for a wallet. The benefit is less about changing how I budget and more about reducing the small bits of friction involved in paying. I would still carry a backup card or another accepted way to pay, especially for a day of errands or travel.
MyCard is less compelling if most of your spending happens online, if you prefer paying with a watch, or if you already have a mobile wallet that is accepted wherever you shop. In those cases, adding another payment app may create one more setup to maintain without making checkout meaningfully easier. It is also not a replacement for a bank’s own account tools simply because it sits in the finance category; I would choose a banking app when I need a broader view of accounts or services, and use a contactless payment option for the narrower task of paying in person.
One useful way to decide is to consider your backup plan, not just your ideal payment. If your battery is nearly empty, the terminal is slow, or you cannot get the app ready at the counter, another payment method prevents a minor inconvenience from disrupting the purchase. I would keep a physical card available until I had a good sense of how MyCard fits my regular shops and routine. That is a practical trade-off: the app may make a wallet lighter, but relying on a phone also ties payment to the phone being usable.
MyCard is listed for $17.99, so I would weigh that cost against how often I expect to use it and whether it offers something my existing payment method does not. For an occasional contactless purchase, a payment option already available on the phone may be the more straightforward choice. For someone who specifically wants to try MyCard’s approach, the price is a decision to make before treating it as an everyday essential. I would not assume that paying for an app automatically makes every transaction, shop, or banking feature available; the useful question is whether its actual payment flow suits your needs.
Breaking News
Google Play Services: The Android App That Works Best Unnoticed
Google Photos: Dominating the Mobile Photography Scene
How Booking.com Shapes Modern Travel Habits
What You Give Up When You Switch to Fortnite
How Gallery is Transforming Mobile Photography
How MobiOffice: Word, Sheets, PDF Masters iOS and Android Updates
What I would check before depending on it
My first practical tip is to complete setup when I am not in a hurry. Payment apps are most frustrating when an account or card needs attention just as a queue builds behind me. I would allow time to work through the setup screens, then make a low-pressure first purchase somewhere I already know accepts contactless payments. That gives me a chance to learn the sequence without making an important or time-sensitive transaction the test run.
I would also keep an eye on the distinction between an app showing payment-related information and a payment being accepted by a merchant. A phone screen can help me prepare, but the terminal’s response is what matters at checkout. If a tap does not complete, I would pause and confirm whether the transaction went through before trying again; repeating a payment without checking can create confusion about whether I have been charged. If the issue persists, switching to a backup method is usually more practical than holding up the line while trying to diagnose the cause.
For data-conscious users, I would take a deliberate approach: use the app for the payment task I need, and avoid assuming that a finance app’s presence on a phone tells me exactly how it handles every kind of information. I would review the app’s current in-app disclosures and device settings before entering financial details, and keep the phone protected with the security options I already use. Those are prudent steps for any payment app, not a claim about a particular policy or technical safeguard.
How it compares with familiar alternatives
Compared with cash, a phone payment can spare me from carrying exact change, but cash does not depend on a charged phone or an app being ready. Compared with a contactless bank card, MyCard offers a phone-based route to checkout; the card remains the simpler fallback when I do not want to manage another app. Compared with a general mobile wallet, this app’s appeal depends on whether its particular setup and payment experience work better for me than the option already built into my routine. I would not switch purely because a payment app sounds more modern.
The difference is especially relevant for people who already use one wallet consistently. A second option can be worthwhile if it addresses a concrete need, but otherwise it may split attention: I might have to remember which app contains the payment method I want, whether it is ready, and where to look if something goes wrong. My practical test would be simple: after setup, does MyCard make the contactless purchase I actually make feel easier, without creating extra steps? If not, the familiar card or wallet is probably the better fit.
Simplified Setup
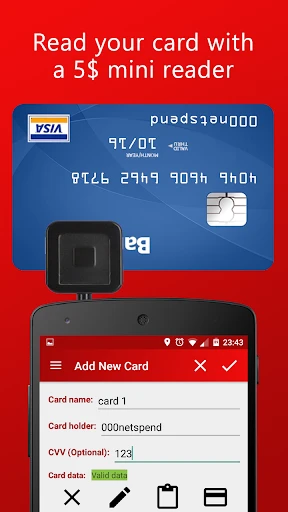
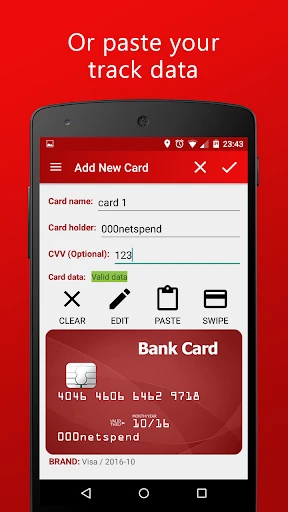
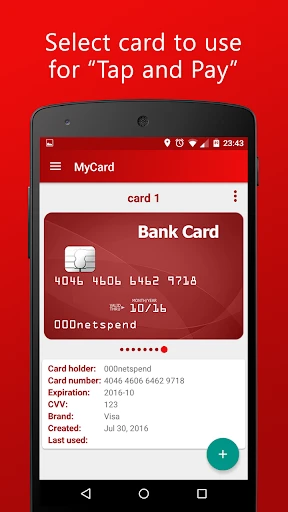
First things first, getting started with MyCard is a breeze. The app is available for both Android and iOS, so all you need to do is head over to the respective app store and hit download. The installation process is straightforward, and within minutes, you're ready to dive into the world of contactless payments. Once installed, setting up an account is just as simple. You enter your details, link your bank account or credit card, and voilà, you're all set up.
User-Friendly Interface
What truly sets MyCard apart is its user interface. It's sleek, intuitive, and designed for people like me who aren’t tech-savvy. The home screen presents you with all the essential features without overwhelming you with options. I appreciated how everything I needed was just a tap away, from checking my balance to viewing recent transactions.
One feature I found particularly useful was the ability to categorize expenses. This not only helps in tracking where my money goes but also in budgeting for future expenses. It's like having a mini financial advisor in your pocket!
Security Features
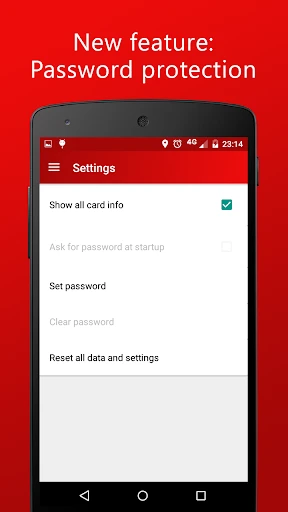
In an era where digital security is paramount, MyCard doesn't disappoint. The app employs top-notch encryption to ensure your financial data is secure. Plus, with biometric authentication, I felt an added layer of security knowing that my transactions are safe from unauthorized access.
Additionally, MyCard offers instant notifications for every transaction. This means I can immediately spot any suspicious activity. It's this kind of attention to security detail that gives me peace of mind while using the app.
Everyday Convenience
Using MyCard for everyday purchases is as easy as pie. Whether I’m buying groceries, dining out, or shopping online, the contactless feature works seamlessly. Just a tap, and the payment is done. Gone are the days of fumbling for cash or worrying about the change.
Moreover, the app supports multiple currencies which is a godsend for someone like me who loves to travel. It automatically converts to the local currency, making international transactions hassle-free.
Rewards and Offers
Who doesn’t love a good deal? MyCard keeps things exciting with its regular rewards and offers. Whether it’s cashback on purchases or discounts at partner stores, the app ensures you get more bang for your buck. It's like getting rewarded for spending money, which is a win-win in my book!
For a quick sense of scale, MyCard has a 4.0 average from around 285 ratings, with over 10,000 installs. Those figures can be a useful snapshot of its audience, but they cannot tell me whether it will work well with my own phone, payment habits, or preferred shops. I would put more weight on a careful first transaction and on whether the app fits my routine than on popularity alone.
Who is likely to find it useful?
I can see MyCard working best for someone who regularly pays in person, is comfortable managing a payment method on a phone, and wants to explore a dedicated contactless option. It is also more appealing to a person who likes keeping an eye on spending and values the expense-categorizing feature described in the app experience. Someone who rarely shops face to face, already has a dependable mobile wallet, or does not want to pay for another finance app may reasonably decide it is not worth adding.
Travelers may appreciate the stated multi-currency support, but I would still plan carefully before depending on it abroad. A different currency can make a payment easier to understand, yet the basic questions remain: will the payment method be accepted at the places I visit, can I access the app when I need it, and do I have another way to pay? I would keep a backup and check the app’s own current guidance before a trip rather than assume every destination will offer the same experience.
Keeping expectations grounded
The contactless concept is straightforward, but convenience should not be confused with universal acceptance. A shop needs a compatible checkout, the phone needs to be usable, and the payment setup has to be ready. That means MyCard is a helpful option rather than a reason to leave every other payment method at home. I would also distinguish its payment role from a full financial-management service: the expense tools can help me notice patterns, but they do not replace the attention needed to review spending and make a budget.
There is also a version and device consideration for anyone deciding whether to install it. The app’s current version is 1.21 and its minimum Android requirement is 5.0, while its content rating is Everyone. It was released on March 22, 2016. I would check compatibility on the device I intend to use and make sure the version available to me is suitable before building a daily routine around it. That is especially sensible for a payment tool, where a smooth setup matters more than simply getting an app icon onto the home screen.
Connectivity verdict
My overall view is that MyCard is most interesting when I want a phone-centered way to make ordinary contactless purchases and appreciate having spending categories in the same experience. Connectivity and readiness are part of that convenience: I would prepare before reaching the till, make an uncomplicated first payment, and keep a backup while I learn how it behaves in my usual settings. If I want the simplest possible option and already have a trusted bank card or mobile wallet, I may prefer to stick with that instead.
As a finance app developed by Road Dogs, MyCard has a focused everyday purpose, but whether it earns a place on my phone comes down to practical fit and its $17.99 price. I would recommend considering it if contactless phone payments are genuinely useful to you and you are willing to make the app part of your checkout routine. I would skip it if I rarely pay in person, want to avoid another paid app, or need a payment method that does not rely on having my phone ready. For me, the sensible approach is to compare it with the card or wallet I already use, try it in a low-stakes setting, and keep whichever option makes paying simpler without adding needless steps.
FAQ
What is MyCard - Contactless Payment and how does it work?
MyCard - Contactless Payment is a mobile application designed to facilitate seamless contactless payments using your smartphone. By linking your credit or debit card to the app, you can effortlessly pay at any contactless-enabled terminal. Simply unlock your phone, hold it near the payment terminal, and wait for the confirmation. It leverages NFC technology to ensure secure and efficient transactions, making it a convenient alternative to traditional card payments.
Is MyCard - Contactless Payment secure to use for transactions?
Yes, MyCard - Contactless Payment prioritizes security with multiple layers of protection. It uses encryption to safeguard your personal and financial data. Additionally, transactions require authentication through fingerprint, PIN, or facial recognition, adding an extra layer of security. The app does not store your card details on the device, reducing the risk of unauthorized access.
Can I use MyCard - Contactless Payment internationally?
MyCard - Contactless Payment can be used internationally, provided that the merchant's payment terminal supports contactless transactions and your card issuer permits international use. Before traveling, it's advisable to check with your bank regarding any potential fees and ensure your card is activated for international payments. This makes the app a versatile tool for travelers who prefer cashless transactions.
What should I do if my phone is lost or stolen?
If your phone is lost or stolen, it's crucial to act quickly to protect your financial information. First, use a device management service to lock or erase your phone remotely. Then, contact your bank to suspend or remove your card from MyCard - Contactless Payment. This will prevent unauthorized transactions, keeping your finances secure. Always ensure your device has a strong password or biometric lock for added security.
Are there any additional fees for using MyCard - Contactless Payment?
Using MyCard - Contactless Payment is generally free, but it's important to verify with your bank or card issuer if any transaction fees apply, especially for international or currency conversion transactions. Some banks may charge for premium services or have limits on free transactions, so understanding your bank's policies will help you avoid unexpected charges. Always review terms and conditions for the most accurate information.