PayPal - Pay, Send, Save
4.2FinanceUpdated October 17, 2026

Screenshots
 Analysis by Mobexer
I see PayPal - Pay, Send, Save as most useful when I need one familiar place to handle online purchases and move money between people, rather than as a complete replacement for a bank. Its strength is convenience across everyday payment tasks; its weakness is that fees, exchange rates, and account restrictions can matter more than the quick interface suggests. I’d recommend it to people who regularly pay online or need to send money to others, provided they check the cost and terms of each transaction instead of assuming every payment works the same way.
Why the all-in-one approach can be handy
PayPal is a finance app from PayPal Mobile, and it brings together several jobs people often handle through separate services: paying at checkout, sending or requesting money, and using pay-in-four options where available. That combination can save time when a merchant already accepts PayPal or when friends use it to settle shared expenses. It is free to download, rated for Everyone, and the current version is 8.97.0, with Android 7.0 as its stated minimum operating-system requirement.
The app has a 4.2 average from around 3.6 million ratings and more than 100 million installs. Those figures suggest that it is a well-established option, not that every transfer is free or every account experience is identical. I treat the broad adoption as a practical advantage: when I need to pay a seller or split a cost, there is a decent chance the other person already knows how PayPal works.
In-Depth Reads on PayPal - Pay, Send, Save
How Tiles Hop EDM Rush Elevates Mobile Rhythm Gaming
Brain Test 2: Tricky Stories - Unraveling Puzzles with a Twist
Hill Climb Racing: The Joy of Simple Digital Adventures
Extreme Car Driving Simulator and the Uncertainty of Recovery
Super Bear Adventure: Navigating Updates with Charm and Challenges
Coloring & Learn: A Creative Boost for Modern Education
How I’d use it in an ordinary week
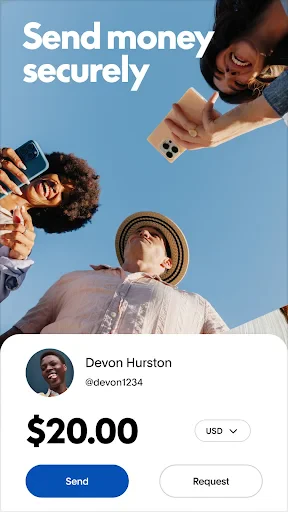
Imagine a friend has paid for a group meal and asks everyone to send their share. A payment app can make settling up quicker than finding cash, and PayPal’s send-and-request functions are built for that kind of exchange. I’d still check the recipient carefully before confirming: a convenient transfer is only helpful if it reaches the right person. For a purchase, I’d also look at the payment method and any displayed charges before tapping pay, especially if the transaction crosses a border.
PayPal can be a useful middle ground between entering card details on multiple shopping sites and using a bank’s own payment tools. When a checkout offers it, paying through an account may mean I do not have to type card information into that merchant’s form. That is convenient, but it is not a reason to skip checking the seller, the amount, or the transaction details. Payment protection is not a guarantee that every disagreement will end in a refund, so I would keep order confirmations and messages if a purchase goes wrong.
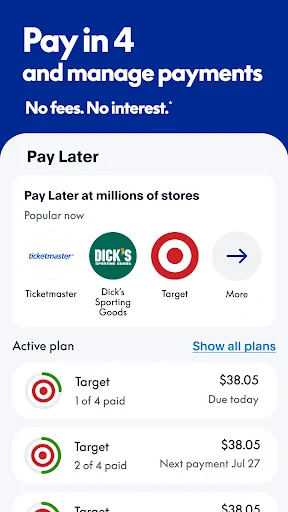
The pay-in-four option may appeal when a purchase is easier to manage in installments than as one immediate payment. I would treat it as a budgeting choice, not extra spending power: before using it, I’d make sure the repayment schedule fits my real cash flow and read the terms shown for that transaction. If I would struggle to cover the installments, paying in full later or choosing a less expensive item is the safer decision.
Where it fits—and where I’d be cautious
Compared with paying directly by card, PayPal can put another familiar step between me and a merchant and can make peer-to-peer transfers more straightforward when both people use the service. Compared with a bank app, it is more oriented toward online checkout and person-to-person payments than everyday account management. A bank’s own app is usually the better place to review the full picture of my deposits, bills, and banking services; PayPal is more useful as a payment layer for particular transactions.
Fresh From the Newsroom
Google Play Services: The Android App That Works Best Unnoticed
Google Photos: Dominating the Mobile Photography Scene
How Booking.com Shapes Modern Travel Habits
What You Give Up When You Switch to Fortnite
How Gallery is Transforming Mobile Photography
How MobiOffice: Word, Sheets, PDF Masters iOS and Android Updates
Getting Started with PayPal
First things first, setting up PayPal is a breeze. You download the app, sign up with your email, link your bank account or card, and voila, you're ready to roll. The user interface is clean and intuitive, so even if you're not tech-savvy, you won't feel lost. With just a few taps, you can send money, request payments, and even pay for purchases in-store using QR codes.
Features That Stand Out
One of the standout features of PayPal is its ability to send money internationally. Whether you're splitting the bill with friends overseas or paying for a service from another country, PayPal makes it easy. The app supports multiple currencies, and the exchange rates are pretty competitive.
Another cool feature is PayPal's Buyer Protection. Ever bought something online and never received it? With PayPal, you can file a dispute, and they’ll have your back. It's like having a safety net for your online purchases.
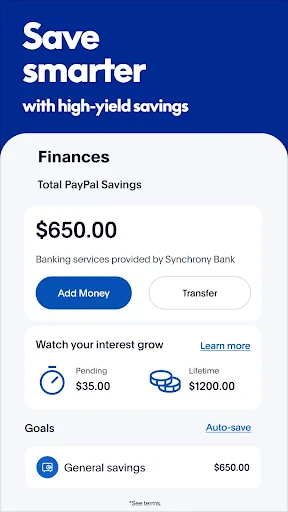
PayPal also offers a savings feature called PayPal Savings. It’s not going to replace your traditional bank savings account, but it’s a nice little addition for those who want to set aside some cash. You can track your savings goals right from the app, which is pretty nifty.
For a shared bill, I’d use the request feature as a clear prompt rather than sending repeated messages: include enough context in the note so friends can recognize the expense, then match incoming payments to the amount due. This small habit makes a social transfer easier to track and reduces confusion when several people owe different shares. For shopping, I’d keep the transaction record in the app and save the merchant’s receipt separately, so I can find both sides of the purchase if I need to follow up.
The international option is attractive when the other person is already set up to receive a PayPal payment, but I wouldn’t assume it beats a specialist remittance service on total cost. The exchange rate and any applicable fee can change what the recipient ultimately gets. Before sending, compare the final amount shown with a bank transfer or dedicated transfer provider, especially for a larger sum or a recurring payment. For a small, occasional transfer where speed and convenience matter most, the extra simplicity may be worth it; for regular support to someone abroad, the cheapest dependable route deserves more attention.
Security and Privacy
Security is a big deal when it comes to handling money online, and PayPal doesn’t disappoint. They’ve got top-notch encryption, and they monitor transactions 24/7 to prevent fraud. Plus, they don’t share your financial details with the merchants. It’s like having an invisible shield that keeps your financial info safe and sound.
For those who are extra cautious, PayPal offers two-factor authentication, adding an extra layer of security to your account. It’s like having a lock with two keys instead of one.
I’d make two-factor authentication part of setup rather than something to remember after a scare, and I’d use a strong, unique password. I also wouldn’t treat a payment notification as proof that a transfer is legitimate: if someone asks me to send money urgently, I’d verify the request through a separate conversation. These habits matter because a secure payment service cannot prevent every mistake a user might make, such as approving the wrong recipient or responding to a misleading request.
Another useful routine is to review account activity after a busy shopping day and check that each payment matches a purchase I recognize. If an unfamiliar charge appears, I’d use the account’s available support and dispute processes promptly, while keeping relevant order details. That is more practical than relying on a general sense that an account is protected. Security tools reduce risk, but staying attentive to transactions is still part of using a finance app responsibly.
What Could Be Better?
While PayPal is pretty fantastic, it's not without its quirks. The fees can be a bit of a pain, especially if you're sending money internationally. And sometimes, the exchange rates aren’t as favorable as you'd like them to be.
There's also the issue of account limitations. If PayPal detects any suspicious activity, they might limit your account, which can be frustrating. It’s like being locked out of your own house because you forgot your keys.
One last thing, customer support can be hit or miss. Sometimes you get a helpful representative, other times you might feel like you're talking to a robot. It’s a bit of a gamble.
Those drawbacks affect different users in different ways. Someone who makes occasional domestic purchases may barely notice the cost questions, while a person relying on international transfers should compare the amount received before committing. And if I depend on uninterrupted access to funds for essential expenses, I would avoid making PayPal the only route for payments or keeping all my practical payment options tied to one account. A limitation can turn an otherwise simple transaction into an urgent support issue.
I’d also choose another option when the recipient does not use PayPal, when a direct bank payment is simpler, or when a dedicated service makes the total cost clearer for a cross-border transfer. For everyday banking, I would stick with my bank’s app; for a particular online checkout or a friend-to-friend payment, PayPal may be the more convenient tool. That distinction is the key to avoiding disappointment: it works best as one useful part of a payment routine, not as the answer to every money task.
Who I’d recommend it to
I’d suggest it to online shoppers who see PayPal at checkout, people who regularly settle small shared expenses, and users who want payment and savings tools within one familiar app. It can also suit someone who values having an established account for occasional international payments, as long as they compare the rate and fees before sending. Its appeal is strongest when the other person or merchant already accepts it and the convenience saves a real step.
I’d be more cautious if you rarely pay online, prefer to keep all transactions directly within your bank, or need the lowest possible cost for frequent international transfers. The same goes for anyone who finds installment payments hard to track: pay-in-four can make a purchase feel smaller than it is, so I would only use it when I can comfortably plan for each payment. PayPal is not automatically the best choice just because it is familiar.
For savings, I’d view PayPal Savings as a convenient place to set money aside and monitor a goal, rather than assume it replaces the account I use for broader banking needs. A practical approach is to decide what the savings pot is for, check the terms shown in the app, and keep essential funds accessible through the financial setup that suits you best. That makes the feature an addition to a plan instead of a reason to move everything into one service.
All in all, PayPal is a solid choice for managing your online transactions. It’s user-friendly, packed with features, and offers a level of security that gives you peace of mind. Just keep an eye on those fees and make sure your account stays in good standing. Happy transacting!
My verdict
I’d keep PayPal available if I shop online, need to request or send money now and then, or want a convenient way to handle a specific payment. I would not rely on it blindly for international transfers, installment spending, or everyday banking without comparing the alternatives and checking the terms each time. Its convenience is real, but it is most valuable when used deliberately. If that matches how you manage money, PayPal Mobile’s free finance app is an easy one to consider; if your priority is direct banking or the lowest transfer cost, another service may fit better.
FAQ
What is PayPal and how does it work?
PayPal is a digital payment platform that allows users to pay, send money, and accept payments without revealing their financial information. Users can link their bank accounts, credit cards, or debit cards to their PayPal account and use it for online shopping, transferring money to friends or family, and receiving payments for goods and services.
Is it safe to use PayPal for transactions?
Yes, PayPal is considered a secure platform for online transactions. It employs encryption and anti-fraud technology to protect user data. Additionally, PayPal offers buyer protection and dispute resolution services, ensuring that users can shop with confidence. However, users should always ensure their account information is kept private and secure.
Are there any fees associated with using PayPal?
PayPal does not charge fees for personal transactions when using a PayPal balance or linked bank account. However, fees may apply for currency conversion, international transactions, and payments made using credit or debit cards. Sellers may also incur fees when receiving payments for goods or services. It's important to review PayPal's fee structure before proceeding with transactions.
Can I use PayPal without linking my bank account or credit card?
While linking a bank account or credit card provides more flexibility and convenience, users can still send and receive money using their PayPal balance. However, limitations may apply, such as withdrawal restrictions or limits on transaction amounts. For a seamless experience, it's recommended to link a funding source to your PayPal account.
How do I resolve issues or disputes with PayPal transactions?
If you encounter any issues with PayPal transactions, you can use their Resolution Center to file a dispute. PayPal provides a step-by-step process to address unauthorized transactions, missing items, or items not as described. They offer mediation between buyers and sellers to facilitate resolutions. Additionally, their customer service is available to assist with any inquiries.
Download