Debbie Rewards
4.9FinanceUpdated November 18, 2026
Screenshots
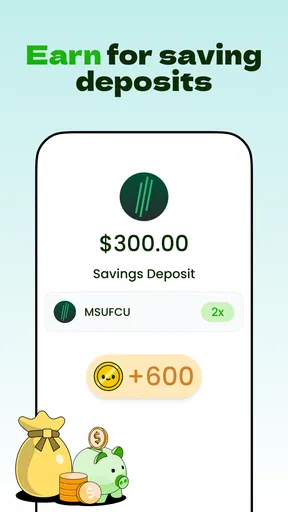
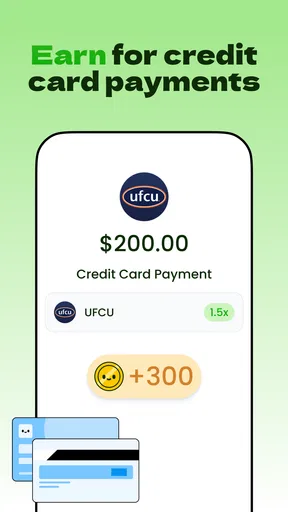
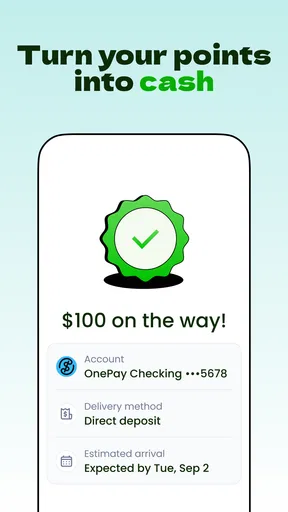
 Analysis by Mobexer
I see Debbie Rewards as a finance app for people who are willing to change a little of their routine in exchange for rewards. Its appeal is easy to understand: it brings paying, saving, and earning into one place. The more important question is whether that combination fits the way you already handle money. I’d consider it if I enjoy trying reward-based financial tools, but I wouldn’t treat the promise of rewards as a substitute for a clear budget or a dependable savings plan.
A useful way to test the fit
Before making it part of your regular money routine, I’d decide what success should look like after a few weeks. That could mean remembering a recurring payment more reliably or giving saving a little more attention. Keep the goal small enough to judge honestly. If the app helps you follow through without creating extra steps, it has earned a place; if you are checking it simply because you hope to see a reward, the routine may not be serving you.
This distinction is especially useful for people who already have several financial apps. A new tool can make a setup feel more active while also scattering information across more screens. I’d avoid entering the same task in multiple places unless there is a clear benefit, and I’d keep whichever tool holds the most dependable record easy to identify. That small bit of organization prevents an incentive app from becoming an accidental second ledger.
A rewards-first approach to everyday money
Debbie Rewards is a free finance app from Debbie Inc., released on February 15, 2023. It is rated for Everyone and runs on Android 7.0 or later. The current version is 2.6.36. Those basics make it approachable for a broad range of Android users, though the age rating alone shouldn’t be mistaken for a recommendation that children use a financial service without an adult’s guidance.
The app’s central idea is more specific than a standard expense tracker. Rather than focusing only on where money went, it ties everyday financial activity to the possibility of earning rewards. That can make routine tasks feel more engaging, especially for someone who already likes setting goals and checking progress. But it also means the app is best judged by how clearly its reward mechanics fit your habits, not simply by how attractive the concept sounds.
In a crowded field of finance apps, the distinction matters. A conventional budgeting app is usually strongest when it helps you see spending patterns and plan ahead. A bank app is usually the place to check balances and make payments. Debbie Rewards takes a different angle: it tries to make financial behavior feel rewarding. That may add motivation, but it does not automatically provide the depth of a dedicated budget or the direct control of a bank’s own tools.
The practical test is whether the reward layer encourages a habit you actually want. If it nudges you to save consistently or pay attention to your money, it may be useful. If you find yourself making choices mainly to chase a reward, the incentive can become a distraction from the financial goal itself. I’d approach it as a companion to sound money habits, rather than the place where every financial decision should begin and end.
Fresh From the Newsroom

 Google Meet
 Review: A Faster Way to Start a Conversation
A practical look at how Google Meet turns an awkward scheduling thread into a useful call—and where its simplicity still leaves room for improvement.

 Annoying Uncle Punch Game®
Annoying Uncle Punch Game Turns One Good Gag Into a Viral Hit
Its slapstick premise is built for quick laughs and shareable chaos. The harder question is whether the joke keeps working after the first round.

 Google Play Games
Make Google Play Games a Better Hub for Your Android Games
A practical guide to turning Google Play Games from a trophy shelf into a dependable hub for finding games, tracking progress, and picking up where you left off.

 Candy Crush Saga
 Makes Every Move Count
A bright puzzle game with a sharper design brain than its sugary surface suggests, Candy Crush Saga still knows how to make one more move feel irresistible.

 Plants vs. Zombies™
Plants vs. Zombies Turns a Calm Lawn Into a Lesson in Strategy
Its garden grid makes every tap legible, but the game’s best design trick is how quickly a calm lawn turns into a lesson in timing, trade-offs, and recovery.

 CodyCross: Crossword Puzzles
CodyCross Makes Solo Solving Feel Like a Shared Pursuit
CodyCross builds its community less through direct conversation than through shared clues, themed worlds, and the small rituals that bring puzzle solvers back.
Read This Next
In Clash Royale, Elixir Is the Real Test of Strategy
The game’s defining feature is not its cards but the shared elixir bar: a small, visible budget that turns quick matches into tense exercises in timing and restraint.
Temu Turns Bargain Hunting Into a Habit, but the Trade-Offs Arrive at the Door
Temu turns low prices into a repeatable browsing habit. Its reach comes from more than discounts, though the trade-offs become harder to ignore once the parcel arrives.
YouTube Music Turns YouTube’s Music Chaos Into Its Greatest Strength
Its biggest trick is not another playlist. It is the way a song can lead from an official recording to the messy, surprising life it has on YouTube.
Picsart AI Turns Quick Ideas Into Finished Images
A lively photo editor for turning quick ideas into finished images, with AI tools that invite experimentation rather than demand design expertise.
Where the concept can be useful
The strongest case for Debbie Rewards is that it gives routine financial actions a reason to feel less dull. Saving often asks for patience, and paying bills can feel like maintenance rather than progress. A rewards-based approach can make the connection between those actions and a longer-term goal easier to notice. That is a meaningful advantage for users who respond to visible milestones or small incentives.
Consider a realistic week: you have a regular bill to pay and are trying to build a saving habit at the same time. Instead of opening a finance app only when something goes wrong, you might use Debbie Rewards as a prompt to make those tasks part of a routine. The useful outcome is not merely collecting a reward; it is remembering to complete a financial task on time and keeping your saving intention in view. That distinction helps prevent the app’s incentive from becoming the whole point.
There is also a helpful behavioral trade-off here. A reward can make a task easier to start, but a habit that depends entirely on an incentive may be harder to maintain if the reward feels less compelling later. I’d use the app to reinforce a routine that already makes sense for my finances, not to justify spending or changing plans just because an action appears to offer something in return.
One practical tip is to decide what you want the app to help with before you make it part of your routine. For example, choose a simple aim such as keeping up with payment tasks or paying more attention to saving. Then assess whether the reward system helps you follow through. This gives you a personal measure of usefulness and makes it easier to spot when the incentive is creating activity without improving your finances.
What to compare before relying on it
Debbie Rewards is not automatically a replacement for a detailed budget. If your main concern is knowing exactly how much you spend by category, forecasting upcoming bills, or reviewing a complete month of transactions, a dedicated budgeting tool may be a better fit. Likewise, if you mainly need to move money or verify a payment, your bank’s own app may be the more direct option. The appeal here is the reward-oriented experience, not a promise that it covers every financial job equally well.
That makes it worth deciding which app should be your source of truth. If you already use a bank app for balances and another tool to track spending, keep those roles clear. Treat Debbie Rewards as an additional way to engage with financial tasks, rather than assuming it replaces records you depend on. This is especially useful if you share bills with another person or plan spending around a strict budget: consistency across your tools matters more than having every feature in one place.
Another non-obvious consideration is how you value convenience. A reward-based process can feel motivating when it fits naturally into something you already do. It is less compelling if you have to keep switching apps, checking details, or reshaping your routine to participate. Before committing, pay attention to whether the actions feel straightforward and relevant to your own goals. An incentive is only a real benefit if the effort and attention it asks of you feel worthwhile.
For someone who is cautious about financial decisions, I’d also separate the idea of “earning” from the idea of reliable income. Rewards are a bonus, not a reason to count on money for bills or savings targets. Build your plan around what you can afford and what you control. If an app’s reward-based framing makes it harder to keep that distinction clear, a simpler budgeting or banking option will be more suitable.
Questions worth settling in your own routine
A natural question is whether rewards can be treated as guaranteed money. I wouldn’t build a bill payment or savings target around them. Think of any reward as a possible extra, and make financial choices based on your regular income and obligations. That approach keeps the app’s motivational value separate from money you need to rely on.
You may also wonder whether it can replace your bank or your budget. I would not assume so. The app’s appeal is its reward-led take on financial habits, while your bank remains the clearer place for account control and a budgeting tool remains better suited to detailed planning. Keeping those roles distinct makes it easier to notice whether Debbie Rewards is helping rather than duplicating work.
If you are deciding whether to keep using it, ask whether the routine is still useful when you ignore the reward for a moment. If the underlying action is sensible and the app helps you remember it, that is a strong reason to continue. If you would not choose the action without the incentive, pause and check that it fits your budget and priorities before proceeding.
Who is likely to get the most from it
I’d recommend giving Debbie Rewards a look if you’re comfortable trying a finance app with an incentive-led approach and you want a little extra motivation around paying and saving. It may suit people who enjoy checking progress and are more likely to follow through when a routine feels engaging. Its free price lowers the barrier to trying it, while the broad Android compatibility makes it accessible to users who are not running the newest operating system.
The app also has a sizable user base: it has over 100,000 installs, with around 15,000 ratings and roughly 3,900 written reviews. Its average rating is 4.9. Those figures indicate that many people have tried it and responded positively, but they don’t tell me whether its particular approach will suit your finances. I’d use them as context, then make the decision based on whether the app’s routine is genuinely useful to you.
It is probably less suitable if you want a comprehensive financial dashboard, dislike rewards as a motivator, or prefer to keep all money management inside your bank’s app. It may also be the wrong choice if you expect an app to make saving effortless without changing your habits. The most it can reasonably do is support actions you choose; it cannot make a financial plan appropriate on your behalf.
If you’re unsure, start with a modest expectation: use the app to see whether its reward-driven approach makes a routine task easier to remember. Avoid reorganizing your whole financial life around it immediately. If it adds useful motivation without creating extra work or encouraging decisions you wouldn’t otherwise make, that is a good sign. If it becomes another notification or another place to check, there is little reason to force it into your setup.
A measured recommendation
My verdict is that Debbie Rewards is most promising as a motivational layer for ordinary financial habits, not as an all-purpose money manager. Its focus on paying, saving, and earning gives it a distinct purpose, and the app’s strong average rating suggests that the approach resonates with many users. The real value, though, depends on whether rewards help you do something financially sensible more consistently.
I’d try it if I wanted a more engaging way to approach routine money tasks and was happy to keep my bank and budgeting tools for the jobs they already handle well. I’d skip it in favor of a dedicated budget or bank app if detailed tracking, direct account management, or a single dependable record is my priority. That is not a knock on the reward concept; it is a matter of choosing the right tool for the job.
Used with clear expectations, Debbie Rewards could make paying attention to everyday finances feel less like a chore. The key is to let your own goals set the direction and treat rewards as an extra nudge, not the reason to spend, save, or pay in a way that does not suit you. For the right user, that balance is what makes this finance app worth considering.
Pros & Cons
Pros
- Earn rewards by completing eligible purchases and activities.
- A simple way to keep track of available offers and savings.
- Reward options can add value for customers who shop regularly.
- Account-based rewards make it easier to keep eligible activity together.
- Useful for checking current promotions before making a purchase.
Cons
- Rewards and offers may be limited to participating locations or purchases.
- Some benefits may require meeting specific terms or spending thresholds.
- Reward availability and value can change over time.
- You may need to share personal information to create an account.
- Occasional users may not earn enough to make the program worthwhile.
FAQ
What is Debbie Rewards, and how does it work?
Debbie Rewards is a rewards app designed to let users earn benefits for completing eligible activities, such as shopping or engaging with offers. The exact tasks, reward amounts, and redemption options can vary by location and may change over time. Before participating, review the offer details in the app so you know what qualifies, how progress is tracked, and whether any conditions apply.
Is Debbie Rewards free to download and use?
The app may be available to download at no upfront cost, but that does not necessarily mean every activity is free of charge. Some offers may involve purchases, subscriptions, or other conditions, while optional in-app purchases could also be available. Check the current app-store listing and read each offer carefully before spending money; never assume that a purchase will be reimbursed unless the terms explicitly say so.
How can I redeem rewards in Debbie Rewards?
Redemption methods and minimum thresholds depend on the rewards currently offered in your account and region. The app may require you to accumulate a certain balance, verify your details, or complete additional steps before a reward can be claimed. Check the redemption screen for eligible options, processing estimates, expiration rules, and any fees. Keep confirmation messages, and contact the app’s support team if a completed redemption does not appear.
Is Debbie Rewards available on Android and iPhone, and where should I download it?
Availability can differ by country, device, and operating-system version, so look for Debbie Rewards in the official Google Play Store or Apple App Store before downloading. Confirm that the developer name and app details match the service you intended to install. Avoid unofficial download sites, which may provide outdated or modified files. If the app does not appear in your store, it may not currently be supported in your region.
What personal information does Debbie Rewards collect, and is it safe to use?
Rewards services may request account details and information needed to track offers, verify eligibility, or deliver redemptions. The specific data Debbie Rewards collects and how it is used should be checked in its privacy policy and the relevant app-store privacy disclosures. Review permissions before granting access, use a unique password, and avoid sharing sensitive information unless it is clearly required for a legitimate feature.