

Vola: Cash Advance & Credit
4.7FinanceUpdated October 5, 2026
Screenshots
Pros
- Fast access to funds after approval
- Simple application process through the mobile app
- May help cover unexpected short-term expenses
- Credit-building options may benefit eligible users
- Repayment dates and amounts are shown in advance
Cons
- Fees can make short-term borrowing expensive
- Approval and advance limits vary by applicant
- Repayment may be required sooner than expected
- Not available in every state or region
- Late payments could affect your credit or account standing
 Analysis By Mobexer
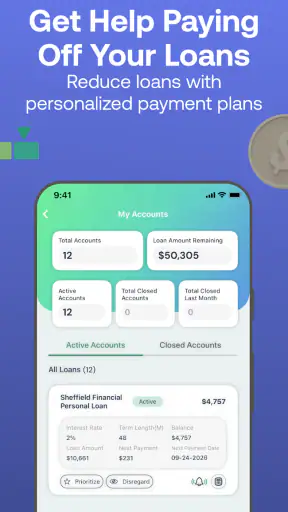
When an unexpected expense lands between paydays, the hardest part is often not the amount itself but the timing. Vola: Cash Advance & Credit is built around that exact problem: giving eligible users access to an advance while also bringing budgeting and spending awareness into the same finance app. I see it as a short-term cash-flow tool rather than a complete replacement for a bank account, credit card, or carefully planned emergency fund.
That distinction matters. The app’s promise is appealing because it focuses on access rather than a traditional credit check, but an advance still has to be handled responsibly. In my experience, the most useful way to judge Vola is to ask a simple question: will it help you bridge a temporary gap without becoming part of your regular monthly budget? If the answer is yes, its combination of cash access and financial tracking can be practical. If you are looking for long-term borrowing or a way to solve persistent overspending, I would look elsewhere.
What the cash-advance feature changes in everyday use
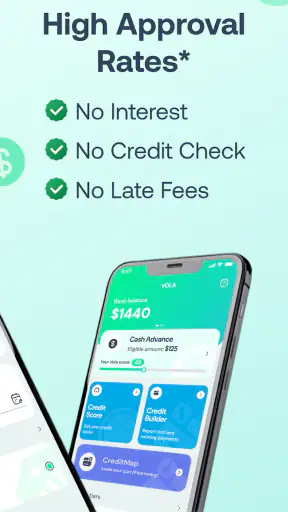
The central capability is an instant cash advance designed for people who need money before their next income arrives. The emphasis on no credit check makes the service potentially more approachable than a conventional loan application, especially for someone with limited credit history or a score that makes ordinary borrowing difficult. That does not make the money free, and it does not remove the need to understand the repayment terms shown in the app, but it can reduce the barrier between an urgent need and a possible solution.
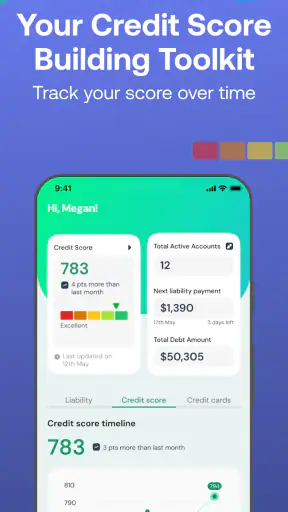
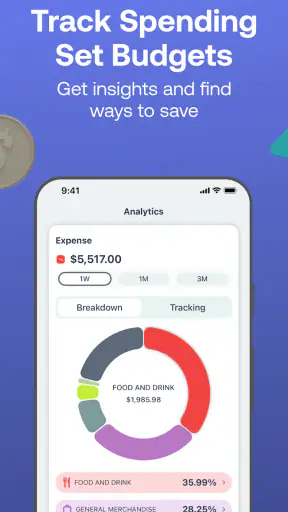
What makes Vola more interesting than a single-purpose borrowing service is the surrounding finance layer. The app also presents tools for budgeting and tracking spending, so the advance is not isolated from the behavior that caused the cash shortage. I appreciate that connection. If I use an advance to cover a grocery trip, transport problem, or bill timing issue, seeing my spending afterward can help me identify whether the problem was genuinely temporary or part of a pattern.
Vola is a finance app from Vola inc., available free of charge and rated for Everyone. It has been available since January 23, 2019, and its current release is version 3.4.15 for devices running operating system version 9 or later. Those details make it accessible to many people using older compatible phones, although I would still check the app’s current device behavior before relying on it during an emergency.
The app has built a substantial audience, with more than 500 thousand installs. Its average rating is 4.7 from roughly 11 thousand ratings, alongside around 2 thousand written reviews. Those figures suggest that many users find the experience useful, but I would not treat popularity as proof that every applicant receives the same access or that every financial situation is suitable. Cash-advance products naturally depend on individual eligibility and account circumstances.
How I would use it before requesting money
I would begin by treating the budgeting and spending views as a preparation step, not an optional extra. Before requesting an advance, I would look at the balance available for essentials, upcoming automatic payments, and the date when regular income is expected. The important question is not simply “Can I get money now?” but “What will my account look like when the advance is due to be repaid?” That small change in thinking is one of the app’s most valuable lessons.
A useful workflow is to separate a genuine timing mismatch from a spending shortfall. Suppose I have enough income to cover rent, food, and transport, but a utility payment arrives several days earlier than expected. An advance may bridge that narrow gap. By contrast, if my normal income cannot cover recurring expenses, borrowing again will only move the problem forward. Vola’s tracking tools can help expose that difference, but they cannot make an unaffordable budget affordable.
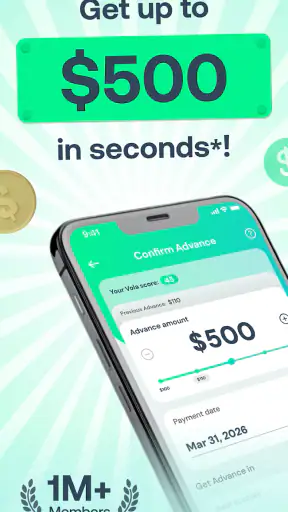
I would also review every screen related to the advance before confirming anything. Pay attention to the amount offered, the repayment date, any applicable cost, and the effect on the next pay cycle. The app’s simple presentation should not encourage a rushed decision. A few minutes spent comparing the advance with delaying a nonessential purchase, asking a provider for a payment arrangement, or using an existing savings buffer may prevent a more expensive habit.
A realistic payday-gap example
Imagine I am paid at the end of the week, but my car needs a repair that cannot wait until then. I open Vola, review my spending, and check whether the amount I need is small enough to repay comfortably from the next income deposit. If the app makes an advance available and the terms fit that plan, the feature could keep the repair from disrupting groceries or transport for the rest of the week.
The responsible part comes afterward. I would record the repair as an unusual expense, then inspect the next few days of spending instead of treating the advance as extra income. If the repayment leaves too little for essentials, the advance was not truly affordable even if it solved the immediate repair. This is where the budgeting side earns its place: it gives the borrowing decision a wider context.
Another realistic use is a delayed payment from an employer or client. In that case, an advance might help with a short gap, but only if the expected income is reliable and the repayment timing is clear. I would not use it for a discretionary purchase that can wait. The convenience is most valuable when the expense is necessary and the timing, rather than the total budget, is the real problem.
Where the app is stronger than ordinary alternatives
Compared with asking a bank for a personal loan, Vola can feel more direct for a modest, urgent need. A traditional loan may involve a formal credit assessment, a longer application process, and a borrowing amount larger than the one I actually need. The cash-advance model is better suited to a narrow payday gap, particularly for someone who may not qualify easily for conventional credit.
Compared with an overdraft, the advantage is the deliberate decision point. An overdraft can happen automatically when a payment clears, leaving me to discover the consequences afterward. With Vola, I can review the amount and connect it to a specific need before proceeding. That said, an overdraft attached to an account with clear, familiar terms may still be preferable for some users, especially if their bank offers a predictable buffer.
Compared with a credit card, Vola is less useful for ongoing flexibility. A credit card can provide a reusable payment method and may offer protections or rewards, depending on the issuer, but it can also encourage balances to linger. Vola makes more sense when I want a defined short-term bridge rather than a revolving line. Anyone who already has a card balance that is difficult to clear should be especially cautious about adding another repayment obligation.
Compared with a budgeting-only app, Vola has a more immediate response to a cash shortage. A budgeting tool can show me exactly where money is going, but it cannot address a bill due tomorrow. The trade-off is that a budgeting-only app may encourage stronger long-term planning without the temptation to borrow. For users whose main issue is organization rather than access to cash, the simpler option may be healthier.
The less obvious value of spending tracking
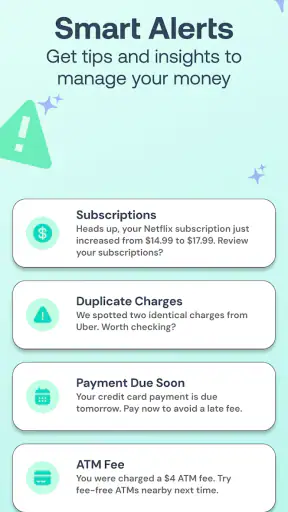
The spending tracker is not merely a decorative feature beside the advance. I would use it to audit the week after borrowing. Look for small purchases that repeat, subscriptions that are easy to overlook, and categories that become unusually high near payday. This can reveal why a supposedly temporary shortage keeps returning. The insight is more useful when I compare it with actual repayment dates rather than judging the month in general terms.
There is also a practical way to use the tracker before an advance: create a short “protected money” mental category for rent, food, transport, and repayment. Even if the app does not replace a full spreadsheet or envelope system, viewing spending through that lens helps prevent the advance from being absorbed into casual purchases. I would rather use Vola to make a narrow correction than to make a larger balance feel available.
For people paid irregularly, the tracking side may be particularly helpful. A monthly budget based on one predictable payday can be misleading when income arrives at different times. Reviewing actual spending between deposits can show the minimum amount needed to get through a low-income period. An advance may help occasionally, but the longer-term answer could be building a buffer during stronger weeks or changing bill dates where possible.
Trade-offs I would consider carefully
The first limitation is psychological: instant access can make borrowing feel like a normal extension of spending. The easier the process feels, the more discipline I need to bring to it. I would set a personal rule before using the app, such as limiting advances to necessary, time-sensitive expenses and never using one to fund entertainment or shopping. The rule matters because the app cannot decide whether my reason is wise.
The second limitation is that avoiding a credit check does not mean avoiding financial consequences. Repayment still affects the money available later, and any costs or conditions displayed during the request need to be read closely. I would not assume that a convenient approval means the advance is inexpensive or suitable. The correct comparison is the total amount I must repay against the alternatives available for that specific expense.
The third trade-off is scope. Vola may be useful for a short cash-flow interruption, but it is not the tool I would choose for consolidating debt, financing a large purchase, or managing a budget that is short every month. A nonprofit debt adviser, a bank product with clearly understood terms, or a structured repayment plan could be more appropriate in those situations. Repeated advances are a warning sign that the underlying budget needs attention.
There is also a practical dependency on phone and account access. If I needed money urgently, I would not wait until the last minute to create an account, review eligibility, or understand how the process works. I would explore the app while my finances were stable, so an emergency would not be the first time I encountered its screens. Keeping another payment method and a small offline record of essential contacts is sensible for any finance service.
Who gets the most from Vola
I think Vola is best for someone with a relatively clear income cycle, a small temporary gap, and enough confidence that repayment will not endanger essentials. It can also suit people who have struggled to access traditional credit and want budgeting visibility alongside a possible advance. The combination is more valuable than the borrowing feature alone because it encourages the user to connect today’s decision with tomorrow’s spending.
It is less suitable for someone with unpredictable income and no reserve, unless the advance is tied to a genuinely dependable incoming payment. I would also advise caution for anyone already juggling several loans, overdrafts, or card balances. Adding another short-term commitment can make the calendar look manageable while making the overall situation worse.
People who want a complete banking replacement may find the app too narrowly focused. Likewise, users who only want expense categorization and do not want access to advances may prefer a budgeting service without borrowing. Vola’s appeal comes from combining both purposes, but that combination is exactly why users need clear boundaries.
My verdict after weighing convenience against control
Vola: Cash Advance & Credit makes the most sense when the problem is timing, not a permanently unbalanced budget. I like that the app places cash access beside budgeting and spending tracking, because an advance should always be considered in the context of the next few weeks. The no-credit-check approach may widen access, but it should never be confused with a free or consequence-free solution.
My practical recommendation is to install it before an emergency, inspect the budgeting tools, and understand the advance terms before deciding whether you need them. Use the smallest amount that solves a necessary problem, protect money for essentials, and check the following pay cycle rather than assuming the issue is finished. That workflow turns the app from a quick borrowing button into a short-term planning aid.
For a one-off bill arriving at the wrong time, I can see why users rate it highly and why the app has attracted a large audience. For recurring shortages, large borrowing, or debt that is already difficult to control, I would choose a different path. Used with restraint, Vola is a useful finance app for bridging a narrow gap; used as regular income, it risks hiding the very budget problem its tracking features are meant to reveal.
FAQ
What is Vola: Cash Advance & Credit, and how does it work?
Vola: Cash Advance & Credit is a financial app designed to help eligible users access money before their next paycheck and monitor aspects of their personal finances. After creating an account, you typically provide information such as income, employment, and bank details so the service can assess eligibility. Available features, advance amounts, repayment terms, and approval decisions may vary depending on your financial profile and location.
How much money can I receive through Vola, and how quickly is it deposited?
The amount available through Vola depends on factors such as your income, banking history, account activity, and eligibility information. Some users may receive a smaller initial advance, with potential increases over time if they meet the service’s requirements. Delivery speed can also differ: standard transfers may take longer, while faster options may involve an additional fee. Always review the final timing and cost before confirming.
Does Vola charge fees, interest, or a subscription for its services?
Before using Vola, carefully check the pricing information shown in the app because costs can depend on the feature and transfer option you select. Cash advance services may include membership or subscription charges, expedited-transfer fees, or other applicable costs, while the exact structure can change. Review the agreement, repayment amount, renewal terms, and cancellation policy so you understand the total expense before accepting an advance.
What are the eligibility requirements for using Vola?
Eligibility requirements may include being at least the required legal age, living in a supported area, having a regular source of income, and connecting an eligible bank account. Vola may also evaluate account activity and other financial information to determine whether its services are available to you. Meeting the basic requirements does not guarantee approval, and the app may request identity or income verification during registration.
Is Vola safe to use, and what should I know about privacy and repayment?
Vola may use security measures and encrypted connections to protect information submitted through the app, but no financial service is completely risk-free. Read its privacy policy to understand how banking, identity, and transaction data are collected and shared. Repayment is generally scheduled according to the terms displayed before acceptance, so maintain sufficient funds and review notifications to avoid failed payments, extra charges, or possible account restrictions.











