

Uthrive: Rewards & Cashback
4.2FinanceUpdated October 2, 2026
Screenshots
Pros
- Earn cashback and rewards from eligible purchases.
- Simple interface makes offers easy to browse and use.
- Useful for comparing available deals before shopping.
- Rewards can add value to purchases you already plan to make.
- Regular promotions may provide extra earning opportunities.
Cons
- Cashback availability varies by retailer
- location
- and promotion.
- Some offers may require activation before completing a purchase.
- Rewards can take time to become available or payable.
- Terms
- exclusions
- and minimum withdrawal limits may apply.
- Tracking issues could require receipts or support requests for verification.
 Analysis By Mobexer
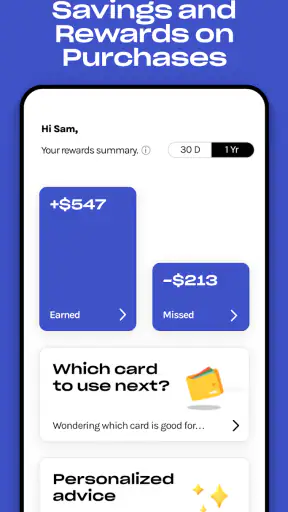
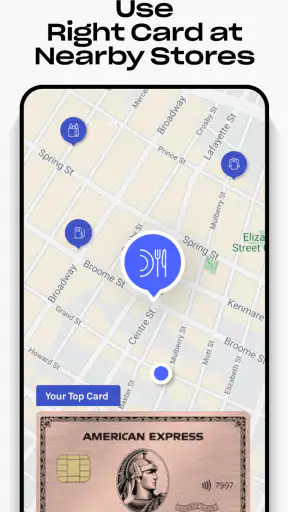
I went into Uthrive: Rewards & Cashback expecting a simple finance app that might save me a little effort when I used a credit card. Its central idea is straightforward: help users find cashback opportunities, activate eligible offers, and make better use of rewards already connected to their spending. That makes it more interesting than a basic balance checker, but it also means its value depends heavily on how consistently I use the recommendations and whether the available offers match my normal purchases.
My first impression was positive because the app focuses on a task people often postpone. Cashback programs can be useful, yet they are easy to forget, especially when offers are spread across different card accounts or apps. Uthrive, developed by Uthrive.club, tries to put that activity in one place. It is free to download, although it includes optional in-app purchases ranging from a small amount to a considerably higher amount per item, so I would pay attention to any purchase prompt rather than assuming every part of the experience is cost-free.
The app belongs to the finance category and is rated for Everyone, which fits its accessible presentation. It has reached over ten thousand installs and holds a 4.2 average from roughly 281 ratings, with 87 written reviews. Those figures suggest a modest but real user base rather than a heavily established financial platform. I would treat that as a reason to test it carefully with my own spending habits, not as proof that it will produce the same results for every cardholder.
How Uthrive feels after the first week
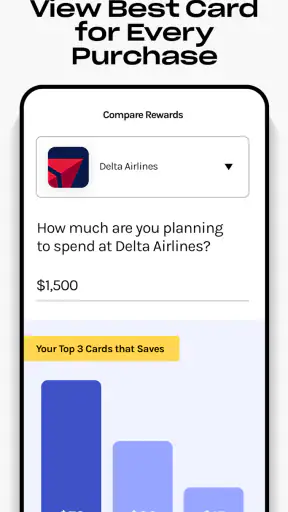
The strongest part of the first-week experience is the possibility of turning a passive rewards program into an active routine. Instead of waiting for a statement and wondering whether I received the best return, I can check for relevant offers before shopping. That small change in timing matters. A cashback offer is usually useful only when I remember it before making the purchase, so opening the app during a weekly planning session is more valuable than browsing it randomly after I have already spent the money.
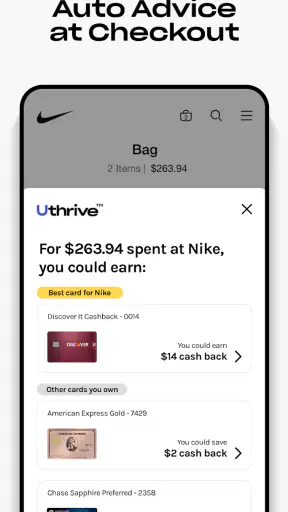
I found the automatic activation concept appealing because it addresses the most annoying part of rewards programs: forgetting to enroll. The practical benefit is not that every purchase suddenly becomes more rewarding. The benefit is that fewer eligible opportunities can slip past unnoticed. I would still read the terms of any offer carefully, because activation alone does not make an unrelated purchase qualify, and a reward is not the same thing as an immediate discount at checkout.
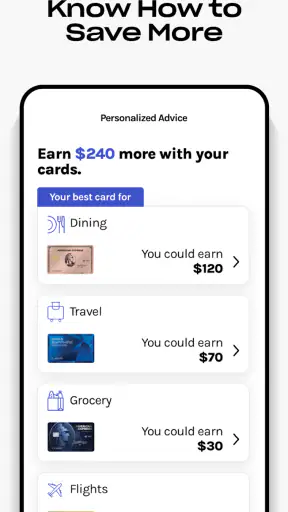
A realistic example is a household preparing for a busy week. Before ordering groceries, buying household supplies, or paying for a planned online purchase, I could check Uthrive to see whether one of my cards has a relevant cashback opportunity. If an offer fits a purchase I was already going to make, it can be a useful reminder. If I have to change stores, spend more than planned, or buy something unnecessary just to chase a reward, the calculation becomes much less attractive.
That distinction is one of the first lessons I would give a new user: use the app to improve purchases you already intend to make, not to justify extra purchases. Cashback tools can make spending feel productive, and that psychological effect is easy to overlook. The app is most helpful when it supports a budget rather than competing with one.
During the opening week, I would also decide which cards and shopping habits deserve attention. Someone who uses one card for nearly everything may find the process simple. Someone who rotates several cards, shops across many categories, or has irregular spending may see more potential but will need more discipline. Uthrive is not a replacement for understanding a card’s own rewards rules. It works best as a layer that helps surface opportunities, while the card issuer remains the place to verify account details and final reward posting.
What makes the early novelty useful
The app’s early appeal comes from visibility. Rewards that normally remain scattered across card programs become something I can actively review. That can reveal a useful pattern: some offers look attractive in isolation but do not matter to my actual routine, while a smaller offer on a purchase I make regularly may be more valuable over time.
I would keep a simple mental filter when reviewing opportunities. First, is the purchase already planned? Second, does the offer require a threshold or special condition that changes the real cost? Third, will using the offer complicate my card strategy? This takes only a moment, but it prevents the common mistake of treating the largest advertised reward as automatically the best choice.
Another non-obvious advantage is that the app can act as a prompt for reviewing neglected rewards habits. I may discover that I have been using a card without checking its available benefits, or that I have mentally assigned a card to one category while ignoring another. Uthrive does not need to make a dramatic change to be useful; reminding me to look before spending can be its most practical contribution.
Whether the value survives from month to month
After the first week, the question changes from “What offers can I find?” to “Will I keep opening this app?” That is where the long-term experience becomes more personal. Cashback is recurring by nature, but the app’s usefulness will rise and fall with the quality and relevance of the offers I see. If my usual retailers and categories are represented, a monthly check can be worthwhile. If the available opportunities rarely match my life, the app may become another notification or finance shortcut that I stop noticing.
I would not judge its value by one unusually good offer. A better test is to use it across several ordinary spending cycles and compare the effort with the rewards actually earned. That means checking before planned purchases, recording whether an offer was activated, and confirming later that the reward appeared where expected. This is especially important for users who want a precise picture of their finances rather than a general feeling that they are saving money.
For a person who already tracks card rewards manually, Uthrive may reduce some of the searching involved. For someone who never checks rewards at all, it may create a helpful habit. The middle ground is less certain: users who occasionally remember to check another rewards portal may not gain enough convenience to justify maintaining another finance app unless Uthrive consistently finds opportunities they would otherwise miss.
The app can also be useful for planning rather than reacting. Before a larger planned purchase, I would compare the available cashback opportunity with the card’s ordinary rewards and any restrictions attached to the offer. The important point is to consider the complete return, not just the headline amount. A smaller reward that works cleanly with an existing card may be preferable to a larger one that forces an inconvenient payment method or encourages spending beyond the budget.
That workflow is more advanced than simply opening the app and tapping an offer. I would create a monthly rhythm: review available opportunities near the start of the month, check again before unusual purchases, and then verify the result when the card statement or rewards balance updates. This keeps the app connected to real financial decisions instead of turning it into a passive list of promotions.
How it compares with ordinary alternatives
The usual alternative is to rely on each card issuer’s own application. That approach has an important advantage: it is the most direct place to see account activity, official reward rules, and posted earnings. If I care mainly about account management, Uthrive would not replace the issuer’s app. I would still use the official card application for balances, payments, statements, and confirmation of rewards.
Another alternative is manual tracking with notes or a spreadsheet. That offers more control and can be better for someone who wants to compare annual fees, category bonuses, and household spending in detail. The trade-off is time. Uthrive is more appealing when I want a quicker reminder system rather than a complete personal finance workbook.
Compared with browsing retailer promotions one by one, the app’s advantage is convenience and concentration. Compared with a full budgeting application, its focus is narrower. It is not the tool I would choose to plan debt repayment, monitor cash flow, or build a complete spending plan. Its role is closer to a rewards assistant, and that narrower purpose is both its strength and its boundary.
The maintenance burden and where fatigue appears
The app is not completely hands-off, even though automatic offer activation is part of its appeal. I still need to check whether an opportunity fits a purchase, understand its conditions, and confirm that the reward was applied. That creates a maintenance burden that may feel small at first but becomes noticeable if I am checking several cards and shopping categories every week.
One source of fatigue is offer mismatch. Seeing many opportunities that do not apply to my normal spending can make the app feel busy without making it useful. Another is the need to remember that cashback often has conditions. Thresholds, eligible merchants, qualifying transactions, or timing rules can turn a seemingly simple reward into something I need to monitor. I would rather ignore an offer than distort my shopping to satisfy it.
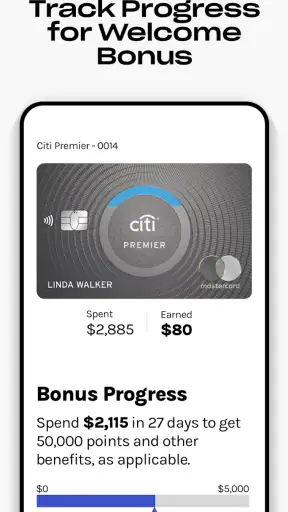
There is also a mental accounting problem. A cashback promise can feel like money already earned even when the purchase has not happened or the reward has not posted. I would avoid counting expected rewards in my budget. Treating them as a bonus after confirmation keeps the app from encouraging overspending and makes the results easier to evaluate honestly.
Users concerned about privacy or account connections should take the setup seriously and read the permissions and connection explanations shown during onboarding. Financial convenience always deserves a careful look at what is being connected and why. I would begin with the smallest practical setup, observe how the app behaves, and avoid linking accounts I do not intend to use with its rewards features.
In-app purchases are another reason to stay attentive. The app is free to download, but optional purchases can cost from ten cents to nearly seventy dollars per item. I would not buy anything merely because it promises to improve a reward outcome without first calculating whether the expected benefit exceeds the cost. For many users, the free experience may be enough to test the concept, and that test should come before spending extra money.
Device compatibility is relatively broad because the current version, 2.3.7, requires Android 6.0 or later. That makes it accessible to people using older Android devices, although I would still keep the application updated when updates are available. The app was released on November 4, 2021, so I would judge it by its current behavior rather than by how long it has existed. Longevity in an app store does not automatically mean that every offer will remain relevant to a particular user.
Who is likely to keep using it
I think Uthrive is best suited to a cardholder who already spends regularly, wants reminders before purchases, and is willing to perform a quick verification step afterward. It is especially sensible for someone who finds rewards programs confusing but does not need a full budgeting platform. The app can also suit a careful shopper who plans purchases in advance and can resist changing behavior just to chase a promotion.
I would be more cautious recommending it to someone who uses cash almost exclusively, rarely shops through eligible channels, or wants a completely automatic financial system with no review. It is also not my first choice for someone whose main goal is debt reduction or detailed household budgeting. In those cases, a budgeting tool or the card issuer’s own application may deliver more direct value.
People who already use a highly organized spreadsheet may find Uthrive redundant unless its offer discovery saves meaningful time. The deciding question is not whether cashback sounds attractive. It is whether the app changes my behavior in a controlled way: do I check before planned spending, choose the right card without overspending, and verify the result afterward? If the answer is no, the app’s presence on my phone is unlikely to matter.
My long-term verdict on keeping it installed
My view is that Uthrive: Rewards & Cashback can earn lasting space on a phone, but only as a lightweight habit rather than a set-and-forget money machine. Its automatic activation idea tackles a genuine problem, and its focused approach is easier to understand than a broad personal finance platform. The first-week appeal is real because it gives rewards a visible place in my shopping routine.
The long-term test is stricter. I would keep it installed if monthly checks regularly surface offers for purchases I already planned and if confirming the resulting rewards takes little effort. I would remove it if the offers feel unrelated, if the maintenance becomes distracting, or if I start spending more simply because a reward is available. That is not a failure unique to this app; it is the central trade-off of cashback tools.
My recommended approach is to start free, connect only what is necessary, and use it for a defined trial period tied to normal spending. Check before planned purchases, read the conditions, keep the budget in charge, and verify rewards after they post. Do not treat the app’s reward language as a reason to buy something you would not otherwise buy, and do not count expected cashback as available money.
In the end, I see Uthrive as a useful companion for organized shoppers, not a replacement for a card issuer’s app or a complete financial planner. It earns its place when it prevents forgotten offers without creating extra spending or constant checking. For me, that makes it worth trying, with the understanding that its lasting value comes from disciplined use rather than novelty.
FAQ
What is Uthrive: Rewards & Cashback?
Uthrive: Rewards & Cashback is a shopping rewards app designed to help users earn cashback, discounts, and other benefits when making purchases through participating retailers and offers. After installing it, users can browse available deals, review the terms, and access a merchant through the app or follow the required steps to qualify. Rewards depend on the retailer, promotion, and applicable conditions.
How do I earn cashback with Uthrive?
To earn cashback, you generally need to find an eligible offer in Uthrive, read its requirements carefully, and complete the purchase using the specified link, method, or tracking process. Some offers may require activating a deal before shopping, while others can involve submitting proof of purchase or connecting a supported payment method. Not every transaction qualifies, so checking the offer details first is essential.
When will my Uthrive cashback become available?
Cashback may not appear immediately after a purchase. In many cases, the transaction first enters a pending status while the retailer verifies the order, confirms that it was not returned or canceled, and reports the commission. The waiting period can vary considerably by merchant and offer. Users should also keep receipts, order confirmations, and other purchase records until the reward is approved.
Can I withdraw rewards earned through Uthrive?
Uthrive’s withdrawal options, minimum payout requirements, and supported payment methods may depend on your location, account status, and the current reward program. Before relying on the app for a specific payout method, open the rewards or cashout section and review the latest rules. You should also check whether rewards expire, whether fees apply, and whether identity or payment verification is required.
Is Uthrive safe and worth downloading?
Uthrive can be useful for people who regularly shop through cashback partners and are comfortable comparing offers before purchasing. However, users should review the permissions requested, privacy policy, retailer exclusions, and tracking requirements before signing up. Cashback is not guaranteed on every order, and the app should be treated as a rewards tool rather than a source of guaranteed income. Downloading it from an official app store is recommended.











