

Upgrade - Boost Money
4.1FinanceUpdated October 5, 2026
Screenshots
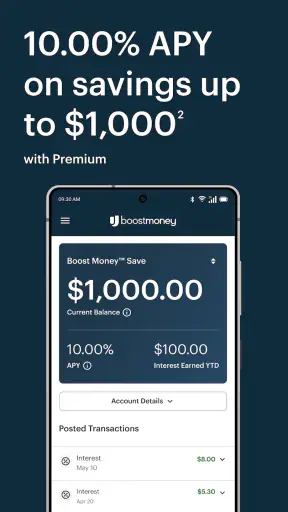
Pros
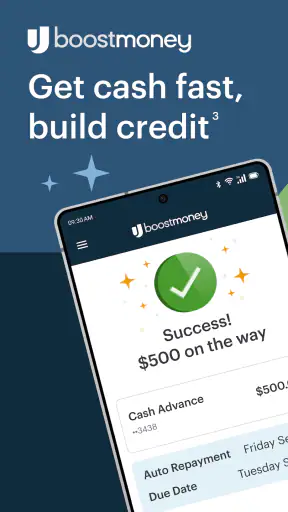
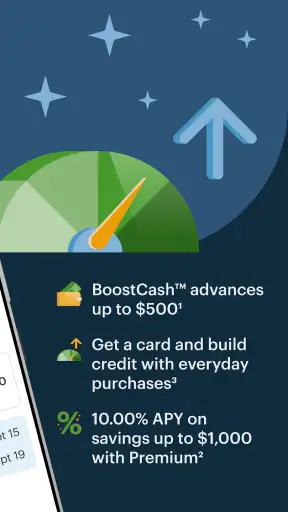
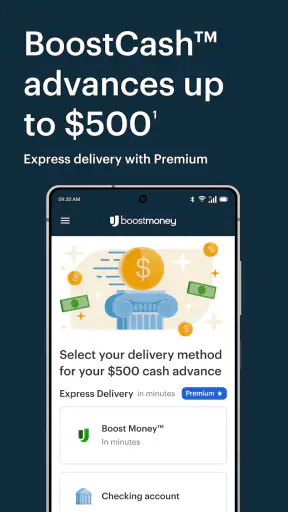
- Simple interface makes account upgrades easy to understand.
- Useful for tracking upgrade progress and available benefits.
- Clear presentation of costs helps with budgeting decisions.
- Convenient access to upgrade options from a mobile device.
- May help users compare plans before committing to one.
Cons
- Some features may require an active subscription or extra payment.
- Benefits can vary depending on the selected plan or account type.
- Not all upgrade details may be available without signing in.
- Frequent notifications could feel intrusive for some users.
- The app may offer limited value if you rarely change plans.
 Analysis By Mobexer
I tested Upgrade - Boost Money as a finance app with a household in mind, rather than treating it as just another place to look at a balance. Its promise is simple: help you spend, save, and build credit from one mobile experience. In practice, that combination makes it most interesting for someone trying to bring everyday money habits into one routine, especially when a partner or another trusted person is involved in planning. It is free to install, rated for Everyone, and developed by Upgrade, Inc.
My first impression was that the app is easier to understand when I give it one clear job. If I open it expecting a complete family banking system, shared budgeting workspace, or replacement for every financial product I already use, the experience feels more limited. If I use it as a personal money hub and decide carefully which parts of my household finances belong there, the purpose becomes much clearer. That distinction matters because shared money is rarely just about convenience; it is also about boundaries, visibility, and trust.
How Upgrade - Boost Money fits into real household routines
A realistic use case is a couple coordinating monthly spending while keeping some personal purchases separate. One person might use the app to monitor their own spending and savings goals, while both people discuss larger household decisions elsewhere. This can reduce the need to switch constantly between unrelated tools, but it does not automatically turn two individual financial lives into one shared account structure. I found that the best results come from agreeing in advance on what the app is being used for.
For example, a household could decide that one person checks upcoming spending in the app each evening, then brings only the important points to a weekly conversation. That is more practical than expecting both people to watch every transaction together. It also avoids a common mistake: treating access to a financial app as permission to inspect every detail of another adult’s spending. The app can support coordination, but the household still needs its own rules about privacy and responsibility.
I also like the idea of using the spending side for short, concrete decisions rather than vague goals. Instead of saying, “We should spend less,” I would use a regular review to identify one category that needs attention and one amount that should be protected for saving. The credit-building focus adds another layer, but it should not encourage anyone to spend simply to create activity. A credit-related tool is only useful when it fits a sustainable payment habit.
That is one of the less obvious trade-offs here. Combining spending, saving, and credit can make a routine feel more complete, but it can also blur three different decisions. Spending answers what I buy now, saving answers what I reserve for later, and credit answers how financial behavior may be viewed over time. I would keep those questions separate during a household discussion, even if the app presents them close together.
One account does not have to mean one household wallet
When several people use the same device, I would be especially deliberate about account boundaries. A shared phone or tablet can make financial access convenient, but convenience is not the same as shared authorization. Before signing in, I would decide whose account is active, who is allowed to handle the device, and whether notifications or visible balances could expose information that should remain private.
This is also where the app’s Everyone content rating needs sensible interpretation. It describes the suitability of the app’s content, not the financial independence of every person who can open it. A child may be able to view an app intended for a general audience, but that does not make the child an appropriate account holder or decision-maker. I would keep adult financial responsibility with an adult and avoid treating a shared device as a substitute for supervision.
My practical setup would be simple. I would install the current release, version 1.3.0, on the person who actually manages the relevant finances, then use the device’s own privacy protections and sign-out habits when necessary. I would not leave an account open merely because the phone stays in the kitchen. A household with separate users should also avoid casually passing around an unlocked device during money conversations.
Another useful boundary is deciding what the app will not manage. I would not assume that every bill, savings goal, or shared purchase belongs inside this one service. Some households already use a bank account for joint bills, a spreadsheet for irregular expenses, and a separate savings method for long-term plans. Upgrade - Boost Money can be part of that arrangement without becoming the only source of truth.
Coordination works best with a small, repeatable routine
I found that a short review schedule would make more sense than constant checking. A household could choose one day to look at spending, confirm what needs to be saved, and discuss whether any credit-related action is appropriate. The point is not to turn money into a daily inspection exercise. It is to create a predictable moment when both people know which decisions are being made and which remain personal.
For shared expenses, I would use a written note or household conversation to record who is responsible for what. I would not rely on memory just because one person can see activity in the app. Visibility does not automatically explain whether a purchase was planned, reimbursed, or unusual. That distinction becomes important when one person is coordinating a household but another person makes the actual purchase.
A helpful workflow is to separate “review,” “decision,” and “action.” First, look at the spending information. Second, agree on whether anything needs to change. Third, carry out only the agreed action, such as moving attention toward savings or adjusting the next week’s spending. This prevents an emotional reaction to one purchase from becoming a larger financial decision.
For a person living alone, that same workflow can be even lighter. I would use the app as a checkpoint after payday or before a large planned expense. The benefit is not that the application makes every choice for me; the benefit is that it gives the routine a recognizable place. If I already have a reliable bank app and a budgeting method that I use consistently, the extra value may be modest.
That comparison with usual alternatives is important. A traditional bank app is often the natural choice for checking balances and moving money connected to an existing account. A spreadsheet can be better for detailed household planning, especially when several people need to edit categories or forecast irregular costs. A dedicated budgeting service may suit someone who wants deeper planning across many accounts. Upgrade - Boost Money is more appealing when spending, saving, and credit-building are the central combination I want to keep together.
Credit-building needs patience and restraint
The credit angle is the part I would approach most carefully. It can be attractive to someone who wants to improve their financial profile while managing everyday spending, but the app should not be viewed as a shortcut. I would read every explanation inside the product, understand what action is being requested, and make sure any payment or spending commitment fits my normal budget before proceeding.
In a household, this deserves a separate conversation because one person’s credit objective can affect how the household thinks about purchases. A partner might see a new financial product as a way to make progress, while the other person sees it as an unnecessary obligation. Neither view should be dismissed. The right choice depends on whether the arrangement is understandable, affordable, and useful for the person whose credit history is involved.
My strongest tip is to avoid changing several money habits at once. If I begin using the app, I would first observe how it fits my existing routine. Then I would decide whether the saving side is actually helping me reserve money, and only afterward consider whether the credit-focused tools deserve a place in my plan. This staged approach makes it easier to identify what is useful and what is simply adding complexity.
I would also avoid judging success by how often I open the app. A finance app can become a source of anxiety if checking turns into reassurance-seeking. The better measure is whether I understand my next financial action and complete it on time. For shared use, the measure is whether the household has fewer misunderstandings, not whether everyone sees the same screen.
Trust, age, and the limits of shared access
The Everyone rating makes the app approachable from a content perspective, but money conversations still need age-appropriate guidance. I would be comfortable showing an older child general lessons about saving or explaining why credit matters, but I would not hand over control of an adult account simply because the application is easy to open. Financial literacy and financial authorization are different things.
For teenagers, I would prefer a supervised learning conversation that uses examples rather than exposing private account information. We could discuss the difference between spending money and saving money, or why borrowing should be planned. I would keep personal credentials, payment decisions, and account recovery details with the responsible adult. This approach preserves trust without confusing education with access.
Shared-device use also raises ordinary privacy issues. Notifications may appear in front of other household members, and an unlocked screen may reveal balances or activity. I would check the phone’s own lock and notification settings, avoid saving passwords where another user can reach them, and sign out when the device is not private. These are not special app features; they are sensible habits around any financial service.
Adults sharing an account should be equally clear. If two partners want a joint financial workflow, they should confirm whose name and responsibility are attached to each action instead of assuming that shared use creates equal rights. If they want separate finances, they should keep separate logins and discuss only the information needed for the household plan. In my view, this is a stronger arrangement than giving everyone unrestricted access and trying to resolve confusion later.
What the rating and scale suggest for a new user
The app has an average rating of 4.1 from around 170 ratings, with more than 50 written reviews, and it has passed 50 thousand installs. I read that as a sign of an established but still relatively small presence rather than proof that it will suit every financial situation. Ratings can tell me how other users feel overall, but they cannot decide whether the spending and credit combination matches my needs.
Its free price lowers the barrier to trying it, which is useful for someone comparing finance tools. Still, “free” should not make me skip the details of any financial arrangement connected with the service. I would examine the in-app terms, understand any consequences before accepting an offer or setting up an action, and avoid assuming that no download charge means no possible financial commitment.
The release date is February 27, 2026, so I would give the app a little extra attention during setup and make sure my device meets its minimum operating-system requirement of iOS or Android 12. That requirement is straightforward for many current phones, but it matters if I am trying to install the app on an older household device. A shared device that cannot run it reliably is not a practical coordination tool, no matter how appealing the concept sounds.
The developer, Upgrade, Inc., gives the product a recognizable identity within the finance category, but I would still judge it by the clarity of the experience and the suitability of its financial tools. I would not choose it solely because it combines several money themes. The combination is useful only when I can understand what each part does and keep my household expectations realistic.
Where I would choose another option
I would skip this app if my main need is detailed joint budgeting with multiple editors, custom categories, long-term forecasting, or a full household ledger. In that situation, a spreadsheet or a budgeting tool designed around collaboration may make responsibilities easier to see. I would also look elsewhere if I only need basic account access and my existing bank application already handles that cleanly.
I would be cautious if my finances are already difficult to manage. Adding a credit-focused product while balances, bills, or repayment dates are unclear could create more mental load. In that case, I would first simplify my obligations and build a dependable payment routine. An app should support a stable plan, not become the plan itself.
It may also be the wrong fit for a family that expects built-in child accounts, automatic parental controls, or a formal shared-device mode. I would not assume those arrangements exist just because the content rating is suitable for everyone. Families needing those specific boundaries should choose a service that clearly centers them, rather than trying to recreate them through informal rules.
On the other hand, I can see the appeal for an adult who wants one focused place to connect ordinary spending with saving and credit awareness. The app is especially reasonable for someone who prefers a guided mobile experience over building a spreadsheet from scratch. It is also useful as a discussion anchor for a couple, provided both people understand that coordination still requires conversation and that access should be intentional.
My household verdict
After using it with shared-use questions in mind, I see Upgrade - Boost Money as a focused finance app rather than a complete household management system. Its strongest idea is bringing spending, saving, and credit-building into the same personal routine. Its main weakness is the temptation to treat that combination as a replacement for clear financial agreements, privacy boundaries, or detailed joint planning.
I would recommend trying it to an adult who wants to make those three areas part of one regular review, especially if a free finance app is preferable to starting with a paid tool. I would set expectations before involving another household member: decide who owns the account, what information is shared, which purchases remain private, and when money will be discussed. Those decisions will have more impact than simply installing the app.
For a shared device, my recommendation is conditional but positive. Keep adult credentials protected, use the phone’s privacy controls, and treat the Everyone rating as a content label rather than permission for unsupervised financial access. For a household that needs formal family controls or deep collaborative budgeting, I would choose a more specialized alternative. For a household seeking a straightforward personal money routine that can support calm coordination, Upgrade - Boost Money is worth considering.
My final advice is to begin with observation, not major financial changes. Use the app to understand your spending pattern, decide whether the saving workflow genuinely helps, and approach credit-building only after the household understands the responsibility involved. If it makes money conversations clearer and actions easier to follow, it earns a place in the routine. If it creates more confusion than structure, the better decision is to return to a simpler tool that everyone can use confidently.
FAQ
What is Upgrade - Boost Money, and how does it work?
Upgrade - Boost Money is a financial app designed to help eligible users manage borrowing, spending, and credit-building features in one place. Depending on your location and eligibility, it may provide access to personal loans, an Upgrade Card, checking-related services, or other money tools. Available products, limits, rates, and terms can vary, so review the full offer before accepting anything.
Is Upgrade - Boost Money safe to use?
The app uses account security measures such as encrypted data transmission, identity verification, and protected login features to help safeguard personal and financial information. However, no online service is completely risk-free. Download it only from the official Google Play Store or Apple App Store, use a strong password, enable available security options, and avoid sharing verification codes with anyone.
Can Upgrade - Boost Money improve my credit score?
Upgrade - Boost Money may help support credit-building when you use an eligible credit product responsibly and the provider reports account activity to credit bureaus. Making payments on time and keeping borrowing under control can be beneficial, while missed payments, high balances, or new applications may negatively affect your credit profile. Results are not guaranteed and depend on your complete credit history.
Are there fees or interest charges in Upgrade - Boost Money?
Some features may involve interest, origination fees, late-payment charges, annual fees, or other costs, depending on the product and the offer presented to you. The app should display important pricing information before you proceed, but you should carefully check the annual percentage rate, repayment schedule, minimum payments, and total cost. Never accept an offer without understanding its terms.
Who can use Upgrade - Boost Money, and what information is required?
Eligibility depends on factors such as your age, residence, income, credit history, identity, and the specific product you request. During registration or an application, you may be asked for contact details, government identification, employment or income information, and permission to verify your credit. Approval is not automatic, and some services may be unavailable in certain states or countries.











