

UNest: Invest & Save for Kids
3.8FinanceUpdated October 2, 2026
Screenshots
Pros
- Simple way to start investing for a child’s future
- Automated deposits help maintain consistent saving habits
- Portfolio options are designed with long-term goals in mind
- Family and friends can contribute to a child’s account
- Educational tools make investing easier for beginners
Cons
- Investment returns are not guaranteed and can lose value
- Fees may reduce growth
- especially with smaller balances
- Account availability and features may depend on your location
- Withdrawals may involve restrictions or tax considerations
- Requires personal and financial information during setup
 Analysis By Mobexer
Saving for a child is easy to postpone because the goal feels distant, while everyday expenses are immediate. UNest: Invest & Save for Kids takes a more structured approach: it helps families put money into a custodial investment account created for a child, rather than leaving the whole plan as an intention. After spending time with this finance app, I see its main value as a combination of convenience and education. It gives parents a simple place to begin, but it is not a substitute for learning how custodial investing works or deciding whether this account type fits the family.
My overall view is positive for parents who want a straightforward child-focused investing routine. The app is free to download, has an Everyone age rating, and comes from UNest Holdings, Inc. Its store summary focuses on saving, investing, and building wealth through a UTMA custodial account. That description is brief, but the important point is the account structure: money placed there is intended for the child, so this is a longer-term family decision rather than just another savings pocket.
How UNest turns a vague saving goal into a family routine
The account structure matters more than the colorful promise
The strongest part of the experience is the way it frames investing around a child’s future. A parent who keeps money in a normal bank account may feel responsible but still lack a repeatable process. A dedicated custodial account creates a clearer mental boundary. Instead of asking whether there is spare cash at the end of each month, I would use UNest around a fixed family habit: decide an amount, add it consistently, and treat the money as belonging to the child’s future.
That distinction is important because a UTMA custodial account is not simply a parent’s emergency fund with a child’s name attached. The adult manages the account while the child is young, but the assets are held for the child. I would therefore pause before opening one and think about the long-term commitment, the child’s likely needs, and how this money fits beside ordinary savings. The app makes the process feel approachable, but the legal and financial meaning of the account still deserves adult attention.
For a first-time investor, the appeal is not that UNest turns investing into a game. Its appeal is that it gives the family a specific destination for contributions. That can be more useful than a general investing service where a parent must create a separate goal, choose a label, and explain the purpose later. Here, the child is central to the workflow from the beginning.
A practical scenario where the app earns its place
Imagine a parent who receives occasional cash gifts from relatives for a child. Without a dedicated plan, those gifts may disappear into household spending or sit unused in an ordinary account. With UNest, the parent can treat each gift as a contribution toward a future purpose, such as education, a first car, or another major milestone. The exact goal can remain flexible, but the habit becomes visible and easier to maintain.
I also think it suits families who want children to understand that money can be saved for more than immediate purchases. A parent could use the account as the starting point for conversations about patience, market movement, and why investing is different from keeping cash. The app itself should not be expected to teach every financial concept, but its child-centered structure gives those conversations a natural subject.
A useful habit is to review the account during a calm monthly money check rather than opening it whenever markets are moving sharply. That keeps the focus on the family objective instead of short-term emotion. For this kind of account, consistency and a sensible time horizon matter more than reacting to every change on the screen.
What the numbers suggest about its position
UNest has reached more than one hundred thousand installs and holds an average rating of 3.8 from roughly two and a half thousand ratings. I read that as evidence of a real audience, but not as proof that every family will find the experience smooth. The rating is respectable while still leaving room for complaints, account-specific friction, or expectations that were not met.
The app has accumulated around four hundred thirty written reviews, which makes the overall picture more useful than a single enthusiastic comment. Still, finance apps deserve a more careful reading than entertainment apps. A minor inconvenience in a game may be harmless; a confusing step involving a child’s account can make a parent hesitate. I would judge UNest by clarity, confidence, and whether the account arrangement matches the family’s needs, not by popularity alone.
The day-to-day strengths are mostly about focus
One thing I appreciate is the narrow purpose. UNest is not trying to be a complete household banking dashboard, a budgeting replacement, or a general-purpose trading terminal. For a parent who wants a child-specific investing destination, that focus can reduce distraction. The question is not “What should I do with every dollar?” but “What am I deliberately setting aside for this child?”
That focus also makes it easier to separate short-term and long-term money. I would keep emergency savings and near-term bills in appropriate cash accounts, then use the custodial account only for money that can remain invested for the child’s future. This separation is one of the app’s most useful practical lessons, even though it requires the parent to make the distinction before contributing.
Another non-obvious advantage is psychological: a named child-focused goal can make irregular contributions feel meaningful. A parent may be more likely to remember a small gift or bonus when it has a clear destination. The app does not need to replace every financial tool to be useful; it only needs to make this one commitment easier to remember and manage.
Where the experience needs a careful adult behind it
The biggest limitation is that simplicity can hide important decisions. A beginner may see an easy path and assume that opening the account is the whole job. It is not. Parents still need to understand who owns the assets, how withdrawals should be considered, and what happens when the child reaches the relevant age under the applicable rules. I would not open a custodial account casually just because the setup feels less intimidating than a traditional brokerage process.
This is also not the right place for money that a parent may need next month. Investment values can move, and a child’s account should be treated as a long-term purpose rather than a convenient reserve. If the family has high-interest debt, no emergency cushion, or unstable income, directing every spare dollar toward a child’s investment account may be the wrong order of priorities. Generosity toward a child should not create financial stress for the household.
Parents should also avoid assuming that a custodial account is automatically the best way to fund education. It may offer flexibility because the money is for the child’s benefit, but that flexibility comes with ownership implications. A parent comparing UNest with an education-specific account should look at the intended use, control, tax treatment, and how much decision-making authority the family wants to retain. The app’s child-focused design is appealing, but the account type should lead the decision.
Costs deserve attention before the first contribution
The app is free to download, but it includes in-app purchases ranging from $4.99 to $149.99 per item. That makes it especially important to read the current in-app terms before committing money or selecting an optional service. A free download and an affordable overall experience are not automatically the same thing.
I would compare any recurring or optional cost with the amount being invested. A charge that seems small in isolation can matter if contributions are modest, particularly over a long period. The right question is not simply whether UNest is free to install, but whether the complete cost structure is clear and reasonable for the family’s planned use. In a child-investing app, transparency around charges is part of trust.
This is one area where a conventional brokerage or bank savings product may be preferable for some users. A parent who already understands investing and wants maximum control may value a broader platform, a wider range of account types, or a different fee arrangement. UNest’s advantage is approachability and purpose, not necessarily being the most flexible choice for an experienced investor.
Who will get the most from it
I would recommend UNest first to parents or guardians who want to start a child-focused investing habit without building a complicated system themselves. It is particularly suitable for someone who keeps saying, “I should save for my child,” but has not turned that thought into a dedicated account. The app’s focused purpose can provide the nudge and the structure.
It may also work well for relatives who regularly give money and want those gifts to support a longer-term goal. In that situation, the important benefit is not a clever feature but the ability to direct generosity toward an account created for the child. I would still make sure every adult involved understands that custodial money is not the same as a private gift fund controlled indefinitely by the donor.
Families should be comfortable with investment risk and with leaving the money alone for the intended horizon. If a parent wants a guaranteed balance, easy access, or a simple place for next year’s expenses, a savings account is likely a better fit. If the parent wants to trade actively, analyze investments in depth, or manage several kinds of accounts from one dashboard, a full-service brokerage may be more appropriate.
I would also hesitate to recommend it to anyone who dislikes reading account terms. Finance apps can make the first steps friendly, but friendliness should not replace comprehension. Before adding money, I would confirm the contribution process, understand the available account arrangement, check the applicable charges, and discuss the plan with the other decision-makers in the family.
Small habits that make the setup more useful
My first practical tip is to decide the purpose before deciding the contribution. “For the future” is a reasonable starting point, but a more concrete intention helps prevent withdrawals for unrelated spending. The goal might be broad, yet it should still answer why this money belongs in a custodial account instead of an ordinary savings account.
My second tip is to choose a contribution rhythm that survives a difficult month. A smaller amount that can be maintained is more useful than an ambitious promise that gets abandoned. I would review the amount after major household changes, but I would avoid changing it merely because the market has had a good or bad week.
Third, I would keep a simple offline note explaining the family’s intention for the account. That note can record who contributes, what the money is meant to support, and which questions should be revisited as the child grows. This is not a replacement for the app; it is protection against forgetting the reasoning behind the account years later.
Finally, I would use the account as a teaching prompt rather than handing a child a screen full of financial language. A parent can explain that the money is invested, that values may rise and fall, and that the purpose is long-term. This approach turns UNest into part of a family money conversation instead of treating it as an invisible automatic transfer.
Compatibility and maintenance considerations
The current version is 3.8.1, and the app requires Android 7.0 or later. That makes it accessible to many Android users, though anyone with an older device should check compatibility before planning around it. The developer is UNest Holdings, Inc., so users who need help should keep their account details organized and use the app’s current support route rather than relying on outdated instructions found elsewhere.
Because this is a finance app, I would update it through the official app marketplace and avoid installing modified copies. I would also use a strong device passcode and treat notifications carefully, especially on a shared phone. These are ordinary precautions, but they matter more when an app is connected with a child’s financial future.
The Everyone rating makes the app broadly suitable from a content perspective, but that should not be confused with a child independently managing the account. The responsible adult remains the person who must understand the account, supervise contributions, and decide how to discuss the money with the child. The age label describes the app’s content suitability, not the removal of adult financial responsibility.
My final recommendation
After weighing the convenience against the responsibilities, I see UNest as a useful starting point rather than a complete financial answer. Its best quality is focus: it encourages a parent to create a child-specific investing habit and gives that goal a clearer home than an undirected savings plan. For families with a stable foundation and a genuinely long-term objective, that can be meaningful.
Its weakness is equally clear. The approachable presentation may tempt some users to move too quickly through a decision that involves ownership, access, investment risk, and possible charges. I would not recommend opening an account without understanding those points, and I would not use it for emergency money or a near-term purchase.
My verdict is that UNest: Invest & Save for Kids is worth considering if you want a simple, child-centered route into long-term investing and are willing to do the adult homework that the app cannot do for you. It is less compelling for experienced investors seeking broad control, for families needing immediate access to cash, or for anyone looking for a guaranteed savings product. Used with realistic expectations, it can turn a good parental intention into a more consistent financial habit.
The app is free to download, but I would review the in-app purchase details before using it seriously. Its 3.8 average from about 2.5K ratings suggests a generally useful experience with noticeable room for improvement, while its 100K+ installs show that the concept has found a substantial audience. For me, the deciding factor is not those figures; it is whether the family understands the custodial commitment and can leave the money working toward the child’s future.
FAQ
What is UNest: Invest & Save for Kids?
UNest is a family-focused investing and saving app designed to help parents and relatives build money for a child’s future. It generally uses an investment account structure intended for minors, allowing adults to contribute regularly or make one-time deposits. The app presents the process in a simplified way, but users should still review the account type, investment choices, fees, and tax treatment before opening an account.
How does investing through UNest work?
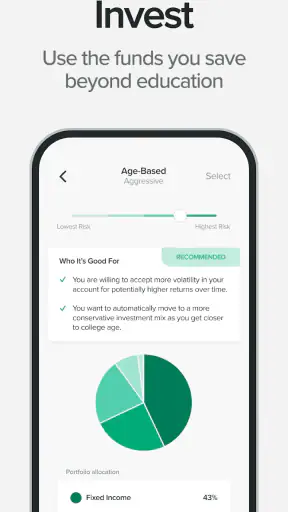
After creating an account and providing the required personal and child-related information, you can fund the account through recurring contributions or individual deposits. UNest invests the money according to the portfolio or risk option selected in the app, rather than keeping every contribution as cash. Because investments can rise or fall in value, the balance is not guaranteed, and the final amount depends on contributions, market performance, time, and applicable fees.
Is UNest safe and is the money guaranteed?
UNest uses standard security measures intended to protect account information and financial transactions, but no online service can eliminate every cybersecurity risk. Investment accounts are also different from bank savings accounts: market losses are possible, and investment balances are not guaranteed to grow. Before depositing money, check the current disclosures, custodial arrangements, regulatory information, and any applicable investor protection limits.
What fees does UNest charge?
The total cost of using UNest can include a subscription or management fee, fund-related expenses, and other charges depending on the account and services available at the time you enroll. Fees can reduce long-term returns, especially when contributions are small or the account is held for many years. Always review the latest pricing page and account agreement in the app before confirming your investment.
Can I withdraw money from a UNest account whenever I want?
Withdrawals are subject to the rules of the account opened through UNest, so access may not be as flexible as money held in a regular savings account. If the account is established for a child, legal ownership and withdrawal requirements can affect who may request funds and how they can be used. Taxes, penalties, processing times, and market conditions may also apply, so read the withdrawal terms carefully before investing.











