

Ualett
4.6FinanceUpdated October 5, 2026
Screenshots
Pros
- Fast access to earned wages through the Ualett app.
- Simple application process with minimal paperwork.
- Useful for managing cash flow between regular paydays.
- Designed with gig workers and independent earners in mind.
- Funds can help cover unexpected short-term expenses.
Cons
- Availability and features may vary by state or location.
- Early wage access fees can reduce the amount you receive.
- Not a replacement for stable
- long-term financial planning.
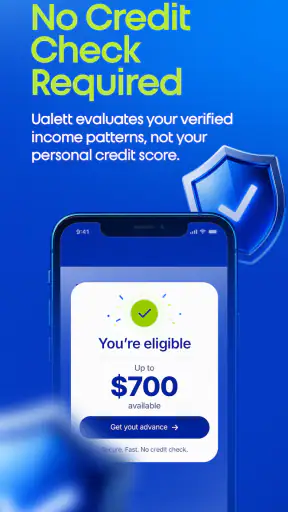
- Eligibility may depend on income history and account activity.
- Late repayments or fees could make borrowing more expensive.
 Analysis By Mobexer
For people who earn money through driving, deliveries, freelance jobs, or other flexible work, managing cash flow can be harder than earning it. Income may arrive at different times, while fuel, phone bills, repairs, and everyday expenses still need attention. Ualett is a finance app built around that kind of working life, and I found its focus more practical than a general budgeting app that assumes a regular paycheck.
The app is developed by Cabicash Solutions, Inc and is available for free. That makes it easy to try without committing money upfront, which matters when your income changes from week to week. It is rated for Everyone, runs on Android 8.0 or later, and the current version is 2.73.0. Those details make it accessible to a broad range of users, although the usefulness of any finance app still depends on whether its workflow matches the way you actually get paid.
How Ualett fits into a gig worker’s finances
My first impression is that Ualett is best understood as a focused financial tool for people outside the traditional payroll routine. Instead of treating a user as someone who receives the same amount on a fixed schedule, its identity is tied to gig work. That distinction is important. A delivery driver, rideshare worker, courier, or independent contractor often needs to think in terms of daily earnings, operating costs, and timing rather than simply waiting for a monthly salary.
The app has attracted more than 500 thousand installs, with an average rating of 4.6 from roughly 7.6 thousand ratings. That level of adoption suggests that its intended audience is not a tiny niche, while the rating indicates that many users find the overall experience useful. I still would not treat a rating as proof that every financial situation will work smoothly. Finance tools are especially dependent on personal circumstances, eligibility, and the way a person receives income.
What I like about the concept is that it starts with the reality of irregular work. If I finish a shift and need to decide whether today’s earnings can cover fuel, groceries, or a bill, a tool designed for gig workers feels more relevant than a conventional banking app that mainly shows balances and transactions. The value is not just in having another place to look at money; it is in having a financial workflow that acknowledges how variable earnings can be.
What the free price really means
Ualett is free to download and use as an app, so there is no purchase price standing between you and a first look. That is a genuine advantage for someone who wants to test the experience before making it part of a regular money routine. It also means the app can be considered alongside existing financial tools without requiring an immediate paid commitment.
Still, “free” should not automatically be read as “every possible financial action costs nothing.” The app itself has no stated purchase price here, but financial services can involve conditions outside the basic download. I would read any in-app terms carefully before relying on a particular transaction, transfer, advance, or account-related action. This is not a criticism unique to Ualett; it is simply a sensible habit whenever an app interacts with real money.
That distinction affects the value calculation. The free access makes experimentation low-risk from a software-cost perspective, but it does not remove the need to understand how the service works for your own circumstances. If you only want a simple spending log, a standard budgeting app may offer enough. If you want a tool specifically intended for gig-worker cash flow, Ualett is easier to justify trying because the entry cost is not a subscription or one-time purchase.
Where the app can be useful during a real workday
Imagine I start a weekday with a nearly empty fuel tank and several delivery blocks ahead. My income will depend on how much work I accept and how long the shift lasts, while fuel is an immediate expense. In that situation, a gig-focused finance app can help me think about available money in relation to the work producing it. I would use it as a checkpoint before and after the shift: first to consider what I need to spend to work, then to review what is actually available afterward.
The important habit is separating earning money from spendable money. A driver who brings in a strong amount during an afternoon may still need to reserve part of it for fuel, maintenance, taxes, or a phone plan. Ualett does not replace that judgment, but its audience and positioning make it a more natural companion for this kind of calculation than a generic account screen.
A second useful scenario is an irregular week. Suppose I work heavily over a weekend, then have fewer jobs for several days. A normal monthly budget can hide that uneven rhythm, because it encourages me to compare broad totals rather than the timing of cash. With Ualett, I would be looking for a way to keep my working income and immediate obligations in view together. That can make decisions such as accepting another shift or delaying a nonessential purchase more deliberate.
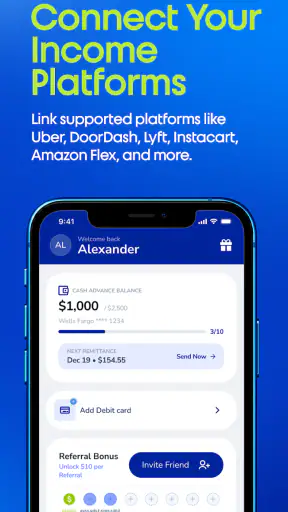
There is also value in reducing the mental friction of switching between work platforms and personal finances. Gig workers often collect earnings from more than one source. Even when an app cannot replace those platforms, having a finance-oriented place to organize the money conversation can be helpful. I would not assume that it automatically consolidates every income source; instead, I would treat it as a focused tool whose usefulness depends on the financial connections and actions available to me after setup.
Practical habits that make the service more useful
The first habit I recommend is checking the app at a consistent point in the work cycle rather than opening it only when money feels tight. For example, reviewing it after a shift can help turn an emotional impression of “I made a lot today” into a more realistic view of what remains after work-related spending. Consistency matters more than checking repeatedly.
The second is to keep a separate mental or written reserve for operating costs. A gig worker should not treat every incoming dollar as personal spending money. Fuel, repairs, insurance, taxes, and equipment can arrive at inconvenient times. Ualett may help with the financial side of this routine, but it cannot decide how much each person should reserve. That decision remains personal and depends on the vehicle, job type, location, and obligations.
The third is to use it as a decision aid rather than a promise of extra income. A finance app can make money easier to organize, but it cannot guarantee more jobs, higher pay, or protection from a slow week. I see the strongest use case as improving awareness around timing and availability. That is less flashy than expecting the app to solve financial pressure, but it is more realistic and more sustainable.
Where the trade-offs become important
The biggest trade-off is specialization. Ualett’s gig-worker focus is its reason to exist, but it may also make it less attractive to someone with a conventional salary, a simple checking account, or no need to manage irregular earnings. If my financial life is already predictable and well organized, I might get more value from a broader banking app, a spreadsheet, or a traditional budgeting service that offers deeper household planning.
Another limitation is that a focused app should not be mistaken for a complete financial plan. I would still want separate habits for tax preparation, long-term savings, debt management, and emergency planning. Someone who expects one app to handle every part of personal finance may find that Ualett is not enough on its own. Its strength is relevance to gig work, not necessarily universal coverage of every financial task.
There is also a learning curve whenever money moves through a new service. Before depending on it for an urgent bill or a work expense, I would test the normal flow with a small, noncritical need and make sure I understand how balances, transfers, and timing work. A free app can be inexpensive to try, but a misunderstood financial process can still create stress. That is why I would keep an existing backup method available until I was comfortable.
Users should also consider whether they want a mobile-first financial experience. If I prefer visiting a branch, speaking with a person for every decision, or managing everything through a long-established bank, Ualett may feel too specialized or unfamiliar. On the other hand, someone who already handles work from a phone may appreciate having a finance tool that fits that routine.
Who is most likely to get real value?
I would recommend giving Ualett a serious look if your earnings come from gig platforms, driving, delivery work, or other independent jobs and you regularly deal with uneven cash flow. It is particularly appealing if you want to try a dedicated tool without paying an upfront app price. The combination of a free app and a clearly defined audience makes the experiment reasonable.
It may also suit someone who is new to gig work and needs a more deliberate money routine. New workers often focus on gross earnings and overlook the cost of staying available for work. A finance app designed with this audience in mind can encourage better questions: what can I spend today, what should remain available for work, and how does a strong shift compare with a slow one?
I would be more cautious if your main requirement is advanced household budgeting, investing, detailed tax records, or a complete business-account system. Those needs can call for specialized tools or professional guidance. Ualett can sit alongside them, but I would not choose it as the only financial resource for a complicated financial life.
It is also not the obvious choice for someone who rarely uses app-based services or who has a stable paycheck and no irregular income to manage. In that case, the gig-worker orientation may add little. A regular bank account with clear budgeting features could be simpler, and simplicity is valuable when a specialized feature does not solve a real problem.
What I would check before relying on it
Before moving important money into any finance app, I would confirm the account or service requirements, the timing of money movement, and the exact terms attached to any financial feature I plan to use. I would also make sure the app supports my work pattern rather than assuming that the phrase “built for gig workers” means every platform or job type will be handled identically.
I would keep notifications and review habits practical. Too many alerts can make money management feel noisy, while too few can cause me to miss a change that matters. My preferred approach would be a brief review after work and a longer check once a week, with the app supporting that routine rather than replacing it.
Privacy and device security deserve attention as well. Since this is a finance app, I would use a strong device lock, avoid signing in on shared phones, and install updates through the official app store. The current release is 2.73.0, and keeping software current is a sensible part of protecting access to any financial account.
My verdict on value and fit
After looking at the app as a working tool rather than a simple download, I see its main value in focus. Ualett is not trying to be a generic money tracker for everyone; it is aimed at people whose income is connected to flexible work and whose financial decisions change with each shift. That makes it more relevant than a standard banking interface when the central problem is irregular cash flow.
The free price is a strong reason to try it, but not a reason to stop reading the terms of any financial service inside it. I would judge the app by whether it helps me understand and manage money from gig work more clearly, not by expecting it to create income or replace every other financial tool.
My buy-or-skip decision is straightforward: I would try Ualett if I were a gig worker who wanted a dedicated finance app and had no interest in paying upfront for experimentation. I would skip it if my finances were already predictable, if I needed comprehensive business accounting, or if I preferred a conventional bank-centered setup. With a 4.6 average from about 7.6 thousand ratings and a growing user base, it has enough evidence of practical appeal to deserve a fair trial, while its specialized purpose makes it important to choose it for the right reason.
My final recommendation is to treat Ualett as a focused companion for irregular work income, not as a complete replacement for financial planning. For the right user, that focus is exactly what makes the app worthwhile. For everyone else, a broader and more familiar finance option may be the better fit.
FAQ
What is Ualett and how does it work?
Ualett is a financial app designed to help users manage and access money-related services from a mobile device. Depending on your location and eligibility, it may provide features such as account management, payments, transfers, or access to financial products. After downloading it, you generally need to create an account, verify your identity, and follow the instructions available in the app.
Is Ualett available to everyone?
Availability depends on your country, age, residency, and the eligibility requirements established by Ualett or its financial partners. Some services may only be offered in selected regions, while additional verification may be required before you can use certain features. Before registering, check whether Ualett supports your location and review the applicable terms, fees, and account conditions.
Is Ualett safe to use?
Ualett should be used with the same care as any financial application. Download it only from an official app store, confirm that the developer information is correct, and avoid sharing passwords, verification codes, or banking details with anyone. The app may use account verification and security protections, but users should also enable device security and monitor transactions regularly.
Does Ualett charge fees for its services?
Possible costs can vary according to the service you use, your location, transaction type, and the financial institution involved. Some actions may be free, while others could include transfer, withdrawal, currency conversion, subscription, or service fees. Always review the fee information shown in the app and the official terms before confirming a transaction or accepting a financial product.
What information is required to create a Ualett account?
When registering, Ualett may request personal information such as your full name, email address, phone number, date of birth, and residential details. Financial services commonly also require identity verification using an official document and, in some cases, additional checks. Make sure the information is accurate, use a secure connection, and read the privacy policy before submitting your data.











