

Trump Accounts: Official App
4.8FinanceUpdated October 5, 2026
Screenshots
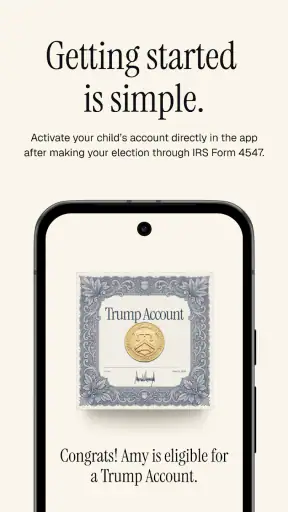
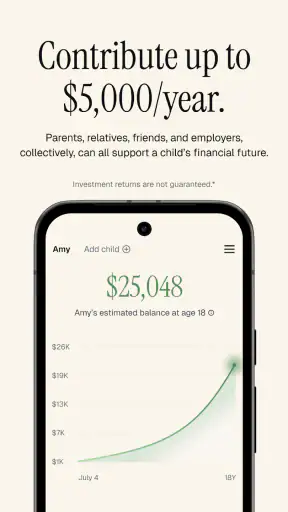
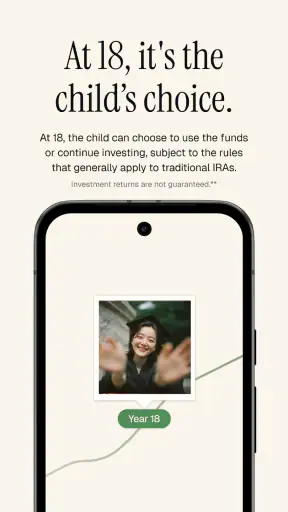
Pros
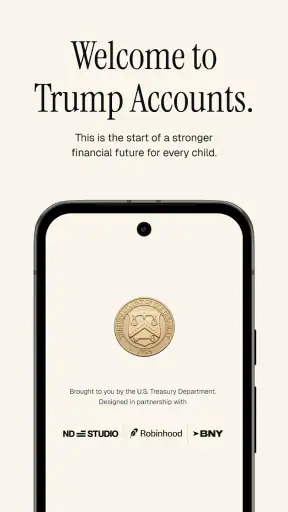
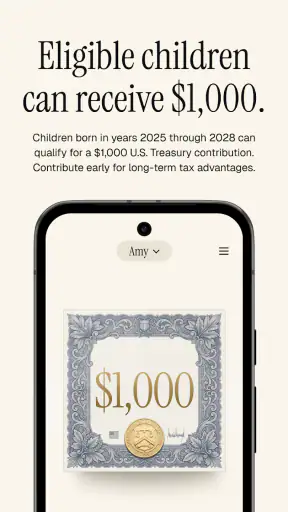
- Official platform for managing Trump Account enrollment and information.
- Clear guidance on eligibility
- contributions
- and account-related requirements.
- Provides access to government-backed updates and official announcements.
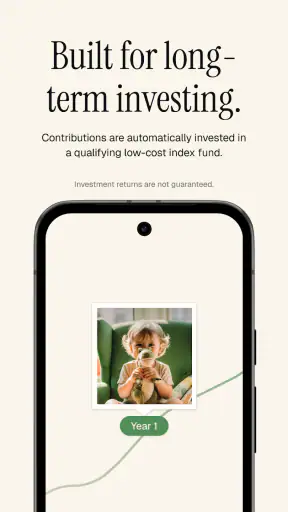
- Useful educational resources for families planning long-term savings.
- Helps users track the steps needed to open or manage an account.
Cons
- Availability and features may depend on current government program rules.
- Some account actions may require identity verification or additional documentation.
- The app may offer limited functionality beyond information and account management.
- Investment details and potential returns may not be fully explained in the app.
- Users may need a separate financial institution for certain account services.
 Analysis By Mobexer
I approached Trump Accounts: Official App as a practical finance tool rather than a general-purpose banking app. Its focus is narrow: helping families think about a child’s long-term financial future through the Trump Accounts program. That focus is both its clearest strength and its biggest limitation. If you are looking for a simple place to manage this particular account, the app has an appealing purpose. If you want everyday banking, investing across several products, or detailed financial planning, you will probably need something else alongside it.
The application comes from the Department of the Treasury, is free to use, and carries an Everyone age rating. It is listed in the Finance category, with the short description “Trump Accounts” and the broader store summary “Invest in your child’s future.” Those phrases describe the direction accurately, but they do not tell you what using the app feels like. My impression is that this is best treated as an official access point for a specific family-finance task, not as a replacement for your existing bank or brokerage app.
How the app feels in its current state
The first thing I noticed is how much the app’s value depends on your personal situation. A parent, guardian, or family member who needs to deal with a Trump Account has a clear reason to open it. Someone without a connection to that program may find the scope too limited to justify keeping another finance app on a phone. That makes the decision fairly straightforward: the app is useful when its purpose matches your need, but it does not try to be everything.
Its public reception is encouraging. The app holds an average rating of 4.8 from roughly 3,100 ratings, and it has more than 500,000 installs. Those figures suggest that many people are finding the official route worthwhile, although ratings alone cannot tell me whether a user’s particular account question will be resolved quickly. Finance applications often receive positive reactions for convenience while still leaving room for frustration around identity checks, eligibility, or account-specific issues.
I would also separate the app’s official status from the quality of every individual interaction. Being developed by the Department of the Treasury gives it an important trust advantage over an unofficial tool using similar language. It reduces the risk of confusing a government account with a third-party financial product. At the same time, an official app can still feel procedural. You may need to read instructions carefully, enter personal information accurately, and keep records of what you submit.
That last point matters more here than it does with a casual budgeting app. When an app relates to a child’s financial account, small details can have consequences. I would avoid rushing through setup while distracted, and I would keep any confirmation screens or reference information that appears during the process. This is not a feature claim; it is simply sensible behavior when using an official finance service connected to a minor.
A focused tool instead of a full financial dashboard
It is tempting to compare this application with familiar banking apps, but the comparison needs care. A bank app usually brings together checking, savings, transfers, cards, statements, and alerts. An investment app may offer market information, portfolios, and trading tools. A budgeting app may concentrate on spending categories and monthly planning. This Treasury application occupies a different lane, centered on Trump Accounts rather than a broad view of household money.
That narrow design can make the experience less confusing for the right user. You are not opening it to browse unrelated financial products or sort through a large collection of tools. You are opening it to handle a defined account-related purpose. The trade-off is that you should not expect it to show your complete family balance sheet or replace the financial app you already use for bills, savings, and daily spending.
A realistic example would be a parent who hears about a Trump Account, wants to understand the next step, and prefers to begin with the government’s own application rather than a search result from an unfamiliar provider. In that situation, I would start here, read each screen slowly, and then return to my regular bank or planning app for the wider household picture. The two tools serve different jobs. Trying to force this app to handle both jobs would make the experience feel more limited than it needs to be.
What the version and release information tell us
The current version is 2026.34.0, and the app is marked as released on May 27, 2026. Those details place the review in an early stage of the product’s public life. I would interpret the version number as evidence that the app is being maintained, not as proof that every desired feature has already arrived. A current release can improve reliability or clarify a workflow without turning a focused government service into a complete financial platform.
The minimum operating-system requirement is Android 7.0. That is helpful for people using older Android hardware, especially families who do not replace phones frequently. Still, compatibility does not guarantee an equally smooth experience on every device. Screen size, system updates, security settings, and the phone’s general condition can affect how comfortable a finance workflow feels. I would make sure the device itself is protected with a screen lock and current security updates before using the app.
Because the release is recent, existing users should pay attention to the practical effect of updates rather than assuming that a new version automatically changes the account itself. An app update may alter navigation, improve explanations, or address technical problems while leaving the underlying eligibility and account rules unchanged. That distinction is important: the software is the door you use, but it is not necessarily the same thing as the financial program behind the door.
What changes mean for someone already using it
If you already installed the application, the sensible approach is to check the version shown on your device and compare the current screens with the instructions you saved earlier. Do not rely on memory if a button moves or a label changes. Finance interfaces can make a small wording adjustment feel significant, particularly when you are deciding whether to submit information or continue an enrollment step.
I would also avoid creating duplicate attempts simply because a familiar screen looks different after an update. Before starting over, look for an existing status, confirmation, or account-history area within the workflow. Repeating an action can create confusion about which submission is current. The safest habit is to document what you have already done and proceed from the existing account path whenever the app presents one.
Another useful habit is to review the information you enter on behalf of a child before moving forward. Names, dates, addresses, and relationship details deserve a second look. I would not treat autofill as automatically correct, particularly if the phone has information for several family members. A quick review can prevent an avoidable correction later and is more valuable here than saving a few seconds during setup.
Families may also share responsibility for a child’s finances. In that case, decide in advance who will manage the app activity and how the other adult will be kept informed. The application should not become the only record of what the family believes has happened. Keeping a simple private note with dates and confirmation details can make future conversations much easier, especially if more than one adult is involved.
The practical gaps I would keep in mind
The main gap is breadth. This is not the app I would choose for tracking household spending, comparing ordinary savings accounts, monitoring a retirement portfolio, or planning a complete education budget. Its purpose is more specific. You may still need your bank, a spreadsheet, or a separate planning tool to answer questions such as how this account fits into your monthly contributions and other goals.
Another possible source of friction is the difference between information and action. An official app can guide you through a process, but that does not mean every question about eligibility, timing, tax treatment, or family circumstances will be answered by a single screen. When a situation is unusual, I would read the official guidance carefully and seek qualified advice where appropriate instead of making a major financial decision based only on a brief in-app explanation.
I would also avoid judging the service solely by how polished the interface looks. A finance app can appear simple because it hides complexity, or appear complicated because it exposes every requirement. What matters is whether you can understand what each step does, recognize when an action is complete, and find a reliable way to address a problem. If you reach a point where the wording is unclear, pausing is better than guessing.
For users who want instant access to broad investment choices, this may feel restrictive. For users who are uncomfortable with financial technology, the official focus may be reassuring, but the responsibility to protect login information and verify details remains. I would skip this app if your only goal is general money management, or if you are expecting a child-focused investing dashboard with extensive charts and portfolio analysis.
Small workflows that make the experience safer
One non-obvious advantage of a focused app is that it can encourage a cleaner routine. I would use it during a quiet moment, with the child’s relevant information available, rather than while commuting or switching between several tasks. Before opening the app, I would write down the exact question I need answered. That prevents aimless tapping and makes it easier to notice whether the current screen actually addresses the issue.
A second useful workflow is to separate research from submission. First read the available explanations and identify what the app is asking for. Then gather the necessary details and return to complete the process. This two-pass method is slower than filling every field immediately, but it reduces the chance of entering a guess or confusing one family member’s information with another’s.
A third trade-off concerns convenience versus record keeping. Digital applications are fast, but a screenshot or private note of a completed step can be valuable if you later need to remember what happened. I would store such records securely and avoid keeping sensitive personal information in an exposed photo folder. The point is not to create paperwork for its own sake; it is to maintain a clear timeline for a financial process involving a child.
Finally, I would check the app deliberately rather than constantly. A finance app can invite unnecessary worry when users repeatedly reopen it without a specific reason. A scheduled review, combined with your normal household planning routine, is more useful than frequent refreshing. This approach also helps you distinguish a real account update from ordinary impatience about when something will appear.
Who should use it, and who should choose another tool
I would recommend the app to a family that wants an official starting point for a Trump Account and values dealing directly with the Department of the Treasury. It is especially suitable when the immediate task is understanding the program’s app-based workflow, checking progress, or managing the account-related steps presented to you. The free price removes one obvious barrier, and the Everyone rating makes it broadly accessible from an age-label perspective.
I would not recommend relying on it alone for a complete family-finance system. Parents who need spending controls, shared budgets, detailed investment research, or consolidated account views will be better served by pairing it with established tools in those areas. That is not a criticism of the application’s purpose. It is a reminder that a specialized government service should be judged by the job it is designed to perform.
Compared with an unofficial guide or a general finance app, the strongest reason to choose this one is its direct connection to the named program and its government developer. Compared with a traditional bank app, its advantage is focus rather than range. Compared with a financial adviser, it offers convenience but not personalized judgment. Those differences make the choice clearer: use this application for official account-related access, and use other resources when you need broader interpretation or planning.
What I would watch as the product matures
Since the app is still associated with a relatively recent release, I would watch how future versions handle clarity, continuity, and support. The most valuable improvements would be the ones that help users understand where they are in a process, what has already been completed, and what action is expected next. In a child-finance workflow, plain explanations are more important to me than decorative design.
I would also pay attention to whether updates make the experience easier for families with more than one child or more than one responsible adult. Those situations are where a narrowly focused account tool can become confusing if the app does not clearly distinguish people, tasks, and statuses. I am not assuming that such functions exist or will arrive; I simply see them as areas that would matter greatly to real households if the product expands.
Another thing worth watching is the balance between accessibility and security. Supporting Android 7.0 opens the door to older devices, but financial software must also remain careful about protecting sensitive activity. The best evolution would preserve broad compatibility while making secure use straightforward for ordinary families, without burying important warnings in technical language.
My overall view is positive but deliberately measured. Trump Accounts: Official App is a free, official Finance application with a clear purpose, a strong average rating, and a growing user base. Its current version shows an active product rather than a forgotten listing, while its limited scope means it should be placed beside—not substituted for—your regular banking and planning tools. The right way to use it is as a focused official doorway into a child’s account process, supported by careful record keeping and realistic expectations.
If that is exactly what you need, I think it is a sensible app to try first. I would install it from the official app store, verify that the developer is the Department of the Treasury, and take the setup one step at a time. If your goal is broader investing or everyday money management, I would skip it as your main finance app and choose a tool built for those jobs instead.
FAQ
What is the Trump Accounts: Official App used for?
Trump Accounts: Official App is designed to provide information and guidance about Trump Accounts, including their purpose, eligibility, enrollment process, contribution rules, and related updates. After reviewing the app, its main value appears to be educational and informational rather than serving as a complete banking application. Users should read the available explanations carefully and confirm important details through official government or financial sources before making decisions.
Who may be eligible to open or receive a Trump Account?
Eligibility can depend on factors such as the child’s age, citizenship or residency status, date of birth, family circumstances, and applicable program rules. The app may explain general requirements, but it should not be treated as a final eligibility determination. Before downloading or submitting information, parents and guardians should review the latest official conditions because legislation, enrollment windows, and qualification rules may change over time.
Can I open or manage an account directly inside the app?
The app may help users understand the process and direct them to the appropriate official resources, but it may not provide every function associated with opening, funding, or managing an account. Depending on the current version, you could be redirected to a website or another authorized service to complete an application. Check the app description, permissions, and official instructions before entering personal or financial information.
Is Trump Accounts: Official App safe to use?
The app should be downloaded only from a recognized Google Play or Apple App Store listing and checked for its verified publisher, privacy policy, update history, and requested permissions. Avoid unofficial copies, websites promising guaranteed benefits, or messages asking for passwords and payment details. Even when an app appears official, never share sensitive information unless you have confirmed that the destination is an authorized government or financial service.
Does the app provide financial advice or guarantee account benefits?
Trump Accounts: Official App should be viewed as an informational tool, not as a substitute for personalized financial, tax, or legal advice. Information about contributions, investment treatment, withdrawals, and potential benefits may depend on current regulations and individual circumstances. The app cannot guarantee approval, returns, or eligibility. Users should consult official documentation and a qualified professional before making long-term financial decisions.











