

Together Loans
4.3FinanceUpdated October 5, 2026
Screenshots
Pros
- Simple way to compare loan offers in one place.
- May help users find options suited to different credit profiles.
- Application process can be completed online.
- Useful repayment and borrowing information for planning.
- Saves time compared with contacting multiple lenders individually.
Cons
- Approval and terms depend on third-party lenders.
- Interest rates may be higher for applicants with weaker credit.
- Loan availability can vary by location.
- Submitting details may result in lender marketing contacts.
- Not suitable for users seeking guaranteed approval or instant funds.
 Analysis By Mobexer
Managing a loan is rarely something I want to turn into a household group project, but it often affects more than one person. A payment may come from a shared budget, a partner may need to know what is due, or someone else may help keep track of the account. Together Loans is built for that practical part of borrowing: it puts the loan-management task on a mobile device instead of making me rely on scattered messages, saved documents, or repeated trips through a browser.
I reviewed it as a finance app from Transform Credit Inc, and my first impression is that its value depends less on entertainment or extra tools and more on whether I already have a loan with the service. It is free to install, has an Everyone age rating, and is intended for managing an existing loan rather than acting as a general-purpose budgeting app. That distinction matters. If I want spending categories, bill reminders across several providers, or a complete household budget, this is not the app I would choose. If I need a focused place to stay connected with a Together Loans account, the narrower design makes sense.
How it fits into a shared household
The most realistic use case is a couple or household where one person is the named borrower but the repayment affects both people. Imagine that I handle the loan account while my partner manages the monthly household budget. The app can serve as the account-facing tool for me, while we use our normal conversation or budgeting method to decide how the payment fits into the wider month. That separation is useful because it avoids pretending that a loan-management app is also a shared finance hub.
I would not treat the app as a replacement for communication. A second person should not assume that installing it automatically gives them access to the borrower’s account, nor should the borrower hand over sign-in details simply because both people contribute money. The safer household habit is to keep the account with the person responsible for it and share only the information needed for planning, such as the upcoming payment details viewed by the account holder. Convenience should not blur account ownership.
On a shared device, I would be especially deliberate. A phone used by several family members can expose financial information through an open session, visible screens, or saved access. I would open the app only when I am ready to deal with the loan, close it when finished, and avoid leaving account pages visible. Those are simple habits, but they matter more here than decorative customization would. The app’s focused purpose means the information on screen may be quite personal even when the interface itself feels straightforward.
There is also a useful division of responsibilities. The borrower can use the app to check the account and handle the loan-related task, while another household member can keep a separate note of the amount that needs to be reserved in the shared budget. I prefer this arrangement to passing the phone around, because it creates a clear boundary between viewing an account and discussing a payment. It also reduces the chance that one person makes assumptions based on an old conversation rather than checking the current account.
What the app is actually good at
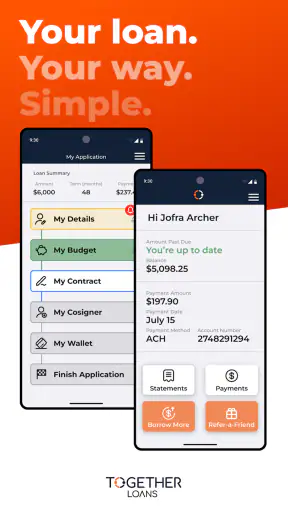
Together Loans is best understood as a companion for an existing loan relationship. The store summary describes it as a way to manage a loan in one place, and that focus comes through in how I would use it: open the app when I need to deal with the loan, review the information available to me, and leave once the task is complete. I would not download it expecting a marketplace for comparing lenders, a credit-building course, or a full financial dashboard.
That narrow purpose is a strength for people who dislike hunting through email threads or mobile websites. A dedicated app gives the loan its own place on the phone, which can make a recurring financial responsibility easier to remember. It also gives me a more direct routine: check the account, confirm what needs attention, and return to the household budget. The benefit is not that it solves every money problem; it is that it can reduce friction around one specific obligation.
At the same time, I would keep expectations realistic. A loan app cannot make a payment affordable, remove the need to read account information carefully, or replace the terms and notices associated with borrowing. I would still review any amount, date, or instruction before acting. The app is a tool for access and management, not a substitute for understanding the agreement behind the account.
Setting it up without creating account confusion
My preferred setup begins with identifying the correct borrower and the correct Together Loans account before anyone else in the household gets involved. The person whose name is attached to the loan should take responsibility for installing and signing in. That sounds obvious, but shared phones, family email addresses, and autofill can make financial accounts confusing very quickly. Keeping the initial setup with one responsible adult gives the household a clear starting point.
I would also avoid treating the app like a shared family profile. If two adults need to coordinate, I would agree on a simple routine instead: one person checks the account, then reports the relevant information through the household’s usual private channel. I would not create improvised workarounds, such as storing credentials in a group chat or leaving the app signed in for someone else. Those shortcuts may feel efficient, but they make it harder to know who has seen or changed something.
Before relying on it during a busy payment period, I would open the app calmly and learn where the important account information appears. I would check that the account shown is the one I expect, make sure I understand which screens are informational and which may lead to an action, and confirm that I can find help or support when needed. Doing this before a deadline is a better test than waiting until I am distracted or rushing.
The technical requirements are modest. The app was released on April 2, 2024, and the current version is 9.1.2, with Android support beginning at version 7.0. That makes it accessible to many older Android phones, although I would still keep the app and operating system reasonably current where possible. Compatibility alone does not guarantee a smooth experience on every device, so I would test it on the phone that will actually be used for the account rather than assuming a family tablet will behave identically.
Because the app is free, the decision to try it does not add a purchase cost. That does not mean using it is financially consequence-free: the loan itself remains the important commitment, and any action taken inside a finance app deserves attention. I like that the download barrier is low, but I would not let “free” encourage casual installation on every household device. One carefully managed device is usually better than several loosely controlled copies.
Boundaries that make shared use safer
For a household, I would establish three boundaries before regular use. First, decide who owns the login and who is responsible for checking the account. Second, decide how information will be shared without sharing credentials. Third, decide what happens if the account shows something unexpected: pause, verify the details, and contact the appropriate support channel rather than guessing.
This approach is particularly helpful when one person is comfortable with apps and another is not. The less confident person does not need to navigate the account alone just to contribute to the budget. They can participate in the financial decision while the borrower handles the account access. Conversely, the account holder should not assume that a partner knows the current situation merely because the household discussed it last week. Coordination works best when the person with access checks the current information before reporting it.
I would also keep the app separate from children’s devices. The Everyone rating describes the content suitability, not permission to let a child manage an adult loan account. A child may use the same phone for unrelated tasks, but that does not make the financial account a shared child-facing space. The adult account holder should remain in control of access and decisions.
Coordinating payments and household decisions
The app becomes most useful when it is part of a repeatable household routine. For example, I might check the loan account at the same time I review the month’s essential bills, then tell my partner what amount needs to be included in the shared plan. I would record that figure in the household budget separately rather than relying on memory. This creates two checkpoints: the app provides the account information, and the budget shows whether the household is prepared for it.
A less obvious benefit of this separation is that it helps distinguish account facts from household guesses. Someone might remember that a payment was “about the usual amount,” while the account may show a different figure or a new message. Checking first prevents the budget conversation from being based on an outdated assumption. In my view, this is where a focused loan app can be more useful than a general notes app: it gives the responsible borrower a direct place to verify the account before coordinating with everyone else.
I would not use the app as the only record of household planning. If my partner contributes half of a repayment, that agreement belongs in our shared budget or conversation, not in the loan account itself. Keeping those roles distinct avoids a common mistake: assuming that the lender’s account reflects how a couple divides costs internally. The lender sees the borrowing relationship; the household decides how to manage its shared money.
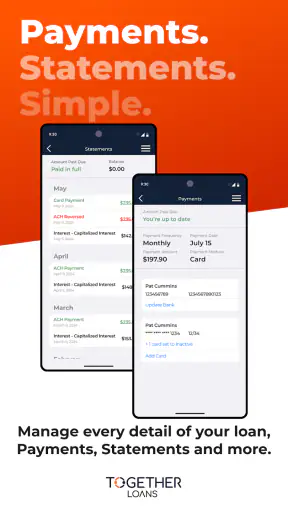
Another practical workflow is to check the account before moving money, not after. If the household uses a joint account, I would confirm the amount and timing first, then make sure the necessary funds are available. I would avoid making last-minute changes while distracted, especially on a shared phone where another person may be waiting to use the device. The app can shorten the route to the information, but it does not remove the need for a deliberate final check.
For people who manage several financial products, Together Loans should occupy a clearly labeled place in the larger system. I would use it for this loan and a separate budgeting tool, bank app, or spreadsheet for the full household picture. That may sound less convenient than one all-in-one app, but it is more honest about what each tool knows. A general finance app may be better for seeing income, savings, utilities, and subscriptions together; Together Loans is more appropriate when the immediate task is the loan account itself.
Where it differs from usual finance alternatives
Compared with a mobile browser, a dedicated app can feel more direct because I do not have to remember which website to open or search through bookmarks. The trade-off is that it adds another installed app and another account surface to maintain. If I rarely need to check the loan, the browser may be sufficient. If I return to the account regularly, having a dedicated icon can make the routine easier.
Compared with a banking app, Together Loans is more specialized. A bank app may show transactions and balances across accounts, but it may not provide the same focused route to managing a Together Loans account. On the other hand, the bank app is usually where I understand whether the household actually has enough money available. I would use both when necessary rather than expecting one to replace the other.
Compared with a budgeting app, the difference is even clearer. Budgeting software helps me plan, categorize, and review broader spending; this app is centered on the loan relationship. If my main question is “Can we afford all our bills this month?”, I need the budget. If my question is “What do I need to know or do regarding this Together Loans account?”, this app is the more relevant starting point.
That specialization is also the main reason some people should skip it. Someone who does not have a Together Loans account will gain little from installing it. Someone looking for loan comparisons, debt payoff projections across multiple lenders, or household expense tracking will probably be happier with a different finance tool. I would recommend it only when its specific account-management role matches the user’s situation.
Age, trust, and responsibility
The Everyone rating makes the app broadly suitable from a content perspective, but finance requires a more careful interpretation than a typical casual app. A young person might be able to view the app without encountering unsuitable entertainment content, yet that does not mean they should be responsible for an adult loan. I would keep access with the borrower or another trusted adult who understands the account and the consequences of acting on it.
Trust matters between adults too. A partner may be fully involved in the household finances but still not be the account owner. I would explain that boundary openly instead of making access feel secretive: one person manages the login, both people discuss the budget, and neither person assumes authority they do not have. This arrangement is not about withholding information; it is about reducing accidental changes and protecting sensitive account details.
For a shared-device household, I would pay attention to ordinary moments that are easy to overlook. Do not open the account while someone else is watching if the screen contains private details. Do not leave the phone unlocked on the account page. Do not ask a child to “just check the payment” because they happen to be holding the device. These are not special features of the app, but they are realistic ways household convenience can turn into poor account hygiene.
I also appreciate that the app’s identity is easy to explain to another household member: it belongs to the loan-management part of the family’s finances, not to the entire financial life of the home. That clarity helps prevent overreliance. If I need a complete view of debt, I would gather information from each relevant provider. If I need to plan cash flow, I would use the household budget. If I need to interact with this particular loan, I would start here.
What the public response suggests
The app has an average rating of 4.3 from over six hundred ratings, with more than two hundred written reviews, and it has passed one hundred thousand installs. I read those figures as evidence that it has found a real audience, not as proof that every household will have the same experience. Ratings can reflect different devices, account situations, and expectations, so I would use them as a confidence signal rather than a guarantee.
The developer, Transform Credit Inc, gives the app a clear connection to the loan service it supports. That is reassuring for someone who wants a dedicated account companion rather than an unrelated third-party organizer. Still, I would pay attention to the identity of the account and the information shown during setup. In finance, recognizing the correct service is part of responsible use, particularly when a family member is helping with installation.
The version information also matters when troubleshooting. If the app behaves differently after an update, I would note that I am using version 9.1.2 before seeking help. I would describe the device and the exact step that caused trouble rather than simply saying that the app “does not work.” That kind of detail makes support conversations more productive and helps the household avoid repeated attempts that could create more confusion.
My household verdict
After looking at Together Loans through the lens of shared use, I see it as a focused tool rather than a family finance command center. I would recommend it to the person who already manages a Together Loans account and wants a dedicated mobile route for keeping up with it. Its free availability, accessible Android requirement, and clear connection to Transform Credit Inc make it easy to consider, while the focused purpose keeps the experience from becoming overloaded with unrelated budgeting features.
I would not recommend using it as a shared login, handing it to a child, or treating it as proof that the whole household’s finances are organized. The strongest setup is simple: the borrower keeps account control, another household member can help plan the money, and the app is checked before decisions are made. That workflow respects both privacy and the practical need to coordinate repayments.
My final opinion is positive but deliberately narrow. Together Loans can remove some everyday friction when the task is managing a Together Loans account from a phone. It is less suitable for comparing loans, planning a complete budget, or combining several financial providers. If you need a dedicated account companion rather than an all-purpose money manager, it is a sensible app to try. If your household’s real problem is broader cash-flow planning, I would pair it with a proper budgeting method instead of asking this one app to do a job it was not designed to handle.
FAQ
What is Together Loans, and how does it work?
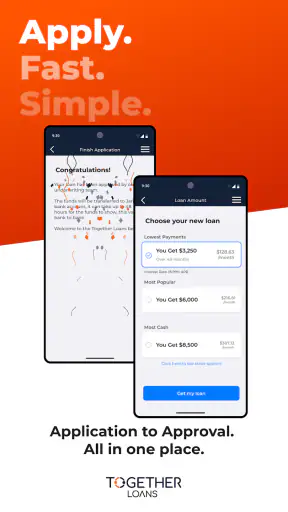
Together Loans is a loan-broker service that helps users compare borrowing options from a panel of lenders. After submitting an application, you provide information about your income, expenses, employment, and requested amount. The service may use this information to search for suitable offers, but approval, interest rates, fees, and repayment terms are decided by the individual lender, not by the app itself.
Can I apply for a Together Loan if I have a poor credit history?
Together Loans may consider applications from people with less-than-perfect credit, although eligibility is never guaranteed. Lenders usually assess your complete financial situation, including income, existing commitments, payment history, and affordability. A poor credit score can lead to higher interest rates or less favorable terms, so review every offer carefully and avoid applying for more than you can comfortably repay.
Will using Together Loans affect my credit score?
The effect on your credit record depends on how the application is processed and which lender you ultimately choose. An initial eligibility search may use a soft credit check that is not visible to other lenders, while a formal application can involve a hard search that may appear on your credit report. Read the service’s explanation before submitting final consent.
Are Together Loans free to use, and are there any additional charges?
Loan-broker services commonly allow users to submit an application without paying an upfront fee, but this does not mean the borrowing itself is free. The selected lender may charge interest, arrangement fees, late-payment fees, or other costs. In some cases, a broker may receive a commission from a lender. Always check the representative APR, total repayment, and full terms before accepting.
Is Together Loans safe, and what should I check before accepting an offer?
Before using Together Loans, confirm that you are dealing with the official service and review its privacy, regulatory, and customer-support information. Never share banking passwords or security codes, and be cautious of anyone requesting an upfront payment to guarantee approval. If an offer is presented, compare the total cost, repayment schedule, cancellation rights, and consequences of missed payments before signing.











