

Sunbit
3.9FinanceUpdated October 2, 2026
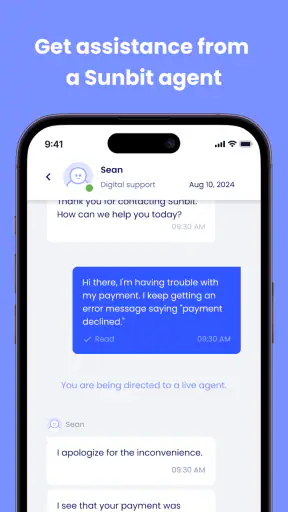
Screenshots
Pros
- Quick application process with a simple
- user-friendly interface.
- Prequalification can be checked without immediately affecting your credit score.
- Offers flexible payment plans for eligible purchases.
- Useful for covering unexpected expenses at participating merchants.
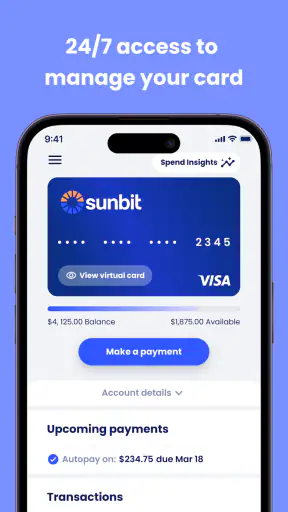
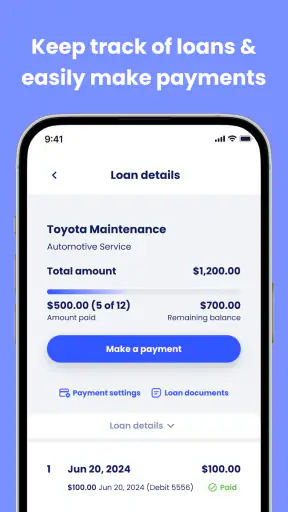
- Payment details and upcoming installments are easy to track in the app.
Cons
- Availability is limited to participating merchants and selected service providers.
- Approval
- rates
- and loan terms vary based on individual credit profiles.
- Some plans may include interest or fees that increase the total cost.
- Missed payments could lead to penalties and negatively affect your credit.
- Not all purchases or users qualify for Sunbit financing.
 Analysis By Mobexer
Managing a payment plan is usually the kind of task I want to finish quickly, without searching through emails or trying to remember which purchase is connected to which account. Sunbit is built for that narrow but useful purpose: it is a free finance app from Sunbit for managing a Sunbit Card and payment plans while away from a browser or a store counter. After spending time with it, I see it less as a general money-management tool and more as a companion for people who already use Sunbit’s credit or financing services.
That distinction matters. If you are looking for budgeting, bank-account aggregation, investment tracking, bill negotiation, or broad personal-finance planning, this is not the app I would choose. Its value comes from keeping Sunbit-related information in one place and making account follow-up more convenient. The app is available to everyone by age rating, costs nothing to install, and has reached over 500 thousand installs. Its average rating is 3.9, which suggests a generally useful experience with enough room for individual frustrations to show through.
What the app is really for
The simplest way to understand Sunbit is to think of it as a control panel for an existing financial relationship. The developer is Sunbit, and the app focuses on the company’s card and payment plans rather than trying to replace your everyday bank. That makes the first decision easy: if you do not have a Sunbit Card or an associated plan, there may be very little reason to keep it installed.
For an existing customer, the practical benefit is having a dedicated place to check the status of a plan and handle account-related tasks from a phone. I like this focused approach because it avoids the clutter found in larger finance apps. At the same time, the narrow scope means the experience depends heavily on how well it reflects the account information you actually need. A polished dashboard cannot compensate for a payment service that does not fit your circumstances.
One realistic use case is a purchase divided into scheduled payments. Instead of relying on memory, a user can open the app before payday, review the relevant plan, and confirm what needs attention. That small habit can reduce the chance of overlooking an obligation. I would still compare the displayed information with my own bank records, especially when a payment is important, because a finance app should support careful checking rather than replace it.
The app was released on May 23, 2021, and the current version is 2.6.37. It requires Android 8.0 or newer, so people using older phones may need to check compatibility before planning around it. Those details are not exciting, but they are useful: a finance tool should be available on the device you actually carry, and an update number can help when troubleshooting with support or deciding whether your installation is current.
Trust starts with a narrow purpose
My first trust test for a finance app is whether its purpose is clear. Sunbit passes that basic test because it does not present itself as an all-purpose financial command center. The app’s role is tied to Sunbit Card management and payment plans. That limited scope makes it easier to understand why I am opening it and what kind of information I should expect to see.
There is also a useful psychological advantage to separation. Keeping a Sunbit plan in its own app can make it easier to distinguish that obligation from checking-account activity, subscriptions, and household bills. The trade-off is that I must switch between apps when building a complete monthly picture. Someone who wants one combined balance sheet may prefer a conventional budgeting app, provided that app supports the accounts and services they use.
I would not judge trust solely by the rating. The app has around 1.4 thousand ratings and 615 reviews, enough to show that people have formed varied opinions, but not enough for me to treat the score as a complete account of every device and situation. A finance app can work smoothly for one customer and become frustrating for another because of login state, account status, or a payment that needs clarification.
The better question is whether the app gives me enough control to inspect what is happening. I want to see the relevant plan, understand which action I am taking, and avoid accidental changes. When reviewing any financial service, I also pay attention to whether the interface encourages confirmation rather than rushing me through a sensitive step. That is more meaningful than a bright design or a long feature list.
Account controls deserve deliberate use
When I use Sunbit, I would treat the sign-in process and account controls as part of the financial task, not as a minor doorway. I would avoid logging in on a shared device, review the account context before making a payment-related choice, and sign out or protect the phone when other people can access it. These are simple habits, but they matter more here than in a casual shopping app.
A useful workflow is to open the app with a specific question in mind: Which plan am I checking? What amount or schedule am I verifying? Am I only reviewing information, or am I about to change something? This prevents the common mistake of tapping through a finance interface without noticing which account or plan is active. I find that purposeful use is especially valuable in a focused app because the screen may feel simple even when the underlying action has consequences.
I would also keep notifications and messages from the service in context. If a reminder brings me into the app, I would open the app directly rather than relying on an unexpected message or link. That approach reduces the risk of confusing a genuine account task with a fraudulent request. The app itself should be the place where I verify the situation before acting.
Another practical tip is to save confirmation details in a personal record after an important action, without storing more sensitive information than necessary. A note with the date, plan name, and a short description can make later reconciliation easier. I would not treat a screenshot as a substitute for an official record, but it can help me remember what I reviewed while I compare it with my bank activity.
Data-sensitive moments are the real test
Finance apps naturally bring sensitive moments into ordinary routines. Opening an account overview, reviewing a payment plan, or handling a card-related task can reveal information that I would not want displayed in public. I therefore use Sunbit in a private setting, keep the phone’s lock protection active, and avoid discussing account details where someone nearby can read the screen.
I am careful with permissions and data practices because those choices affect trust directly. Before granting access, I would read the permission prompt and ask whether it is necessary for the task I am trying to complete. I would not assume that every requested permission is essential, and I would not grant access automatically just because an app belongs to a financial company. The relevant principle is simple: give the app only the access you understand and are comfortable authorizing.
App permissions can change with updates or with the operating system, so I would periodically review them in the phone’s settings rather than relying on memory. This is a more reliable habit than guessing from the app’s category. It also gives me a way to withdraw access I no longer want, when the operating system allows that choice.
I would apply the same caution to personal data entered into support forms or account fields. Before submitting anything, I would check that I am in the correct Sunbit account area and that the information is relevant to the problem. I would avoid placing card details, passwords, or identity information into a general note or an unrelated message. A focused financial app deserves focused handling from the user.
There is a trade-off here. A finance app becomes more convenient when it remembers account context and reduces repeated steps, but convenience can make me less attentive. I prefer to pause before any action involving money, verify the plan displayed, and read the final confirmation carefully. That extra moment is worthwhile even when the interface feels familiar.
Where user agency matters most
The strongest reason to use Sunbit is the ability to check a Sunbit relationship when it suits me, rather than waiting until I am back at a computer or speaking with someone at a point of sale. That gives me more control over timing. I can review a plan before making a household decision, investigate a question when I notice it, and keep the account separate from unrelated financial tools.
However, access is not the same as complete control. The app can help me interact with Sunbit, but it does not make a payment plan automatically affordable. I still need to consider my income, upcoming bills, and the consequences of adding another obligation. This is where a regular budgeting app or a simple spreadsheet may be better: those tools can place a Sunbit payment beside rent, utilities, groceries, and other commitments.
I would also avoid using the app as my only reminder system. A phone calendar or personal budget can provide a second view of important dates, while the Sunbit app remains the place to inspect the related plan. This two-layer approach is useful because it separates planning from account verification. The calendar helps me remember; the finance app helps me check.
For families, shared finances create another boundary. I would not assume that installing the app on a shared phone is a good idea, because account visibility and device access can become confusing. Each person should understand whose account is signed in and who can see the screen. If that cannot be kept clear, using a private device is the safer arrangement.
People who want a simple way to follow one Sunbit Card or payment plan are the best match. The app is also sensible for users who prefer mobile access and want a dedicated place for Sunbit tasks. I would skip it if I had no Sunbit account, needed a full household budget, wanted investment tools, or expected it to manage unrelated financial products.
How it compares with ordinary alternatives
The usual alternative is a web browser. A browser can be more flexible, especially when I need to read detailed account information, manage several services, or work on a larger screen. Sunbit’s app is more convenient for quick checks on a phone, but I would choose the browser when the task involves careful comparison, extensive reading, or troubleshooting that is easier with multiple tabs.
A banking app is another alternative, although it serves a different purpose. A bank app may show the payment leaving my account, while Sunbit is the more relevant place to understand the associated Sunbit plan. Neither view is complete on its own. I would use the bank app to verify the transaction and Sunbit to review the financing context, then investigate any mismatch rather than assuming one screen tells the entire story.
Budgeting apps offer broader organization. They can help me see whether a payment fits into a monthly plan, but they may not provide the same direct connection to Sunbit account activity. For someone managing several obligations, the best setup may be to use a budgeting tool for the big picture and Sunbit for the specific account. That means maintaining two sources, but it also avoids forcing one app to do a job it was not designed for.
Customer support remains an important alternative when something looks wrong. An app is useful for self-service and routine review, but a disputed transaction, unclear account status, or problem that survives a restart should not be handled by repeatedly tapping the same screens. I would record the relevant details first, avoid sending unnecessary sensitive information, and use the official support route associated with the account.
Small frictions I would plan around
The biggest limitation is the app’s specialization. It does not replace a bank, a budget planner, or a complete financial dashboard. That can make it feel indispensable for one narrow task and unnecessary for everything else. I would not install it expecting to organize my entire financial life.
Another friction is the need to maintain accurate personal habits around it. A payment plan can be easy to overlook if I only open the app when a reminder appears. I would schedule a regular review, compare important activity with my bank records, and keep a separate monthly overview. The app can make checking easier, but it cannot create discipline on my behalf.
Compatibility is also worth checking. The current version is 2.6.37 and supports Android 8.0 or later, so an older device may be a practical barrier. I would update through the normal app-store process, review any new permission requests, and avoid installing copies from unfamiliar sources. For a finance app, the installation path is part of the trust decision.
The rating of 3.9 is neither a warning to avoid the app nor proof that every interaction will be smooth. I read it as a reason to keep expectations realistic. The focused purpose is attractive, but account-specific issues can still affect the experience. I would install it because I need Sunbit access, not because I expect a perfect substitute for every other money tool.
My cautious recommendation
After reviewing Sunbit as a finance companion, I think it earns a place on the phone of an active Sunbit Card or payment-plan customer who values quick account access. Its free price removes the installation barrier, and its focused design makes sense when the task is specifically connected to Sunbit. I appreciate that I can approach it as a dedicated account tool rather than a service pretending to manage every part of my finances.
My recommendation comes with clear boundaries. I would use it alongside a bank app for transaction checking and alongside a budget or calendar for broader planning. I would protect the device, inspect permissions, verify the selected plan before acting, and keep a second record of important payment activity. Those steps preserve user agency instead of turning convenience into blind trust.
For someone without a Sunbit relationship, I would pass. For someone who wants investments, spending categories, shared household planning, or a unified view of many accounts, I would choose a broader finance product. But for the specific job of keeping track of Sunbit Card activity and payment plans from a mobile device, Sunbit is a practical, appropriately focused option. Use it as a verification and account-management tool, not as your entire financial plan.
FAQ
What is Sunbit, and how does it work?
Sunbit is a financing and payment platform that lets eligible customers apply for installment plans when purchasing products or services from participating merchants. The application process is usually completed online or at the point of sale, where you provide personal and financial information for an eligibility decision. If approved, you review the available terms before accepting the agreement.
Does using Sunbit affect my credit score?
Sunbit may use different types of credit checks depending on the application stage and your circumstances. Checking whether you qualify may not have the same effect as formally accepting financing, but users should read the disclosures shown during the application carefully. Payment activity and missed payments can also have consequences, so review the full agreement before proceeding.
What can I use Sunbit financing for?
Sunbit is commonly offered through participating businesses for purchases and services such as automotive repairs, dental treatment, vision care, medical services, and other approved expenses. Availability depends on the merchant, location, purchase amount, and your eligibility. The app itself does not necessarily provide financing for every type of purchase, so confirm that your preferred business supports Sunbit.
Are there fees or interest charges with Sunbit?
Costs vary according to the merchant, your application, the selected payment plan, and the terms you are offered. Some plans may advertise low or no interest, while others can include an annual percentage rate or other applicable charges. Before accepting, check the total repayment amount, payment schedule, late-payment policy, and any disclosures presented in the agreement.
Is Sunbit safe to use, and what should I check before downloading it?
Sunbit uses account and identity-verification measures to process applications, but you should still download the official app from a trusted store and verify the developer name. Avoid sharing login details through unofficial links or messages. Before applying, review the privacy policy, permissions, lender or financing disclosures, eligibility requirements, and customer-support options to make an informed decision.











