

Sumio: Net Worth Tracker
3.8FinanceUpdated October 2, 2026
Screenshots
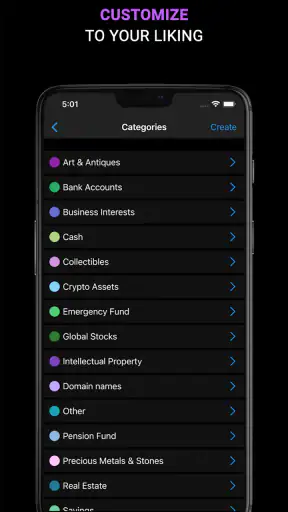
Pros
- Clear net worth overview with assets and liabilities in one place.
- Useful charts help visualize financial progress over time.
- Supports multiple account types for a broader financial picture.
- Simple interface makes regular wealth tracking easy.
- Helpful for setting goals and monitoring personal finance habits.
Cons
- Manual updates can become time-consuming without automatic account syncing.
- Some advanced features may require a paid subscription.
- Financial data may feel limited for users with complex investments.
- Currency and account support can vary by region.
- Entering sensitive financial information may raise privacy concerns.
 Analysis By Mobexer
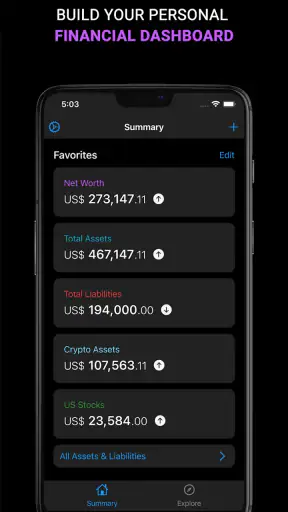
Managing money often becomes difficult for a simple reason: the important information is scattered. A bank account sits in one place, investments somewhere else, property or valuable possessions are remembered separately, and debts are easy to overlook. Sumio: Net Worth Tracker takes a more focused approach by putting those pieces into a personal finance view built around net worth, assets, investments, stocks, and funds.
I found the idea more useful than a basic expense tracker because it encourages a longer-term question: am I actually becoming financially stronger? Instead of only checking what I spent today, I can look at what I own, what I owe, and how my investment portfolio fits into the bigger picture. Sumio is a free finance app from Fiduciary, with optional in-app purchases ranging from $2.99 to $29.99 per item. It is rated for Everyone, so its presentation is approachable rather than aimed only at experienced investors.
The app has an average rating of 3.8 from 78 ratings and has passed 10K+ installs. Those figures suggest a smaller user base than the biggest budgeting services, but they also help set expectations: I would treat Sumio as a focused tracking tool, not as a complete replacement for a bank, broker, tax service, or professional financial adviser.
Getting from installation to a useful financial snapshot
What the app is really for
Sumio makes the most sense when I want a clear estimate of my overall financial position. The central task is not entering every coffee or grocery purchase. It is recording the parts of my financial life that contribute to net worth and keeping an eye on how those parts change over time.
That distinction matters for first-time users. If I expect automatic everyday budgeting, bill reminders, or a full banking dashboard, I may find the experience narrower than expected. If I want a calm place to review savings, investments, funds, stocks, assets, and liabilities, the concept is much easier to appreciate.
My advice is to begin with a modest goal: create a reasonably accurate snapshot, not a perfect financial archive. The first successful result should be a believable net-worth figure that helps me understand where I stand. I can improve the details later.
How I would approach the first setup
After installing the app, I would gather the figures I already know before trying to build a detailed portfolio. A recent bank balance, an approximate investment value, major savings, and significant debts are enough to create a starting point. I would avoid delaying the process while searching for every old statement or trying to value every possession down to the last coin.
The most useful setup habit is to separate categories mentally before entering anything. Cash and savings are not the same as investments. A stock holding is not the same as a fund. A valuable asset should not be counted like available spending money. Keeping those distinctions clear makes the final number more meaningful and prevents me from drawing the wrong conclusion from a single total.
I also recommend choosing a consistent valuation date in my own notes. If I enter a current account balance today but use an old investment statement from months ago, the result can look precise while actually mixing different moments. Sumio can still be useful in that situation, but the comparison becomes less reliable. Consistency is more important than false precision.
The current version is 1.9.18, and the minimum operating system is Android 7.0. That makes the app accessible to people using older Android devices, although I would still keep the phone and app updated when possible. A finance tracker is most helpful when it remains available during regular review sessions, rather than becoming something I install once and forget.
The first meaningful action: build a net-worth baseline
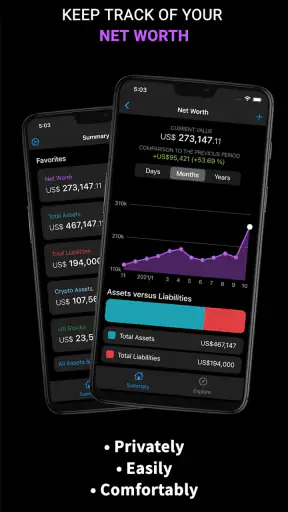
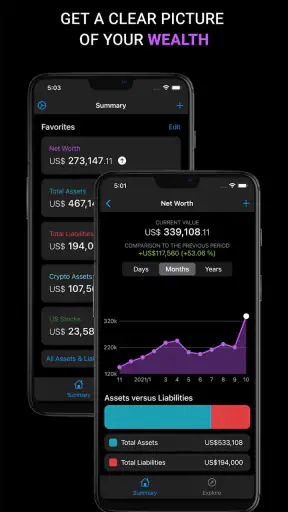
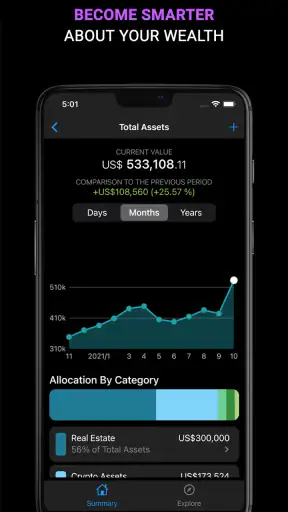
Once the main accounts and holdings are represented, I would pause and inspect the total rather than immediately adding more information. This is the moment when Sumio starts earning its place on my phone. The number gives me a baseline against which future updates can be compared.
For example, imagine I check my finances at the end of the month and discover that my cash savings rose, but my investment value fell. A simple bank-balance app might show only the first part. A portfolio-only tool might show only the second. A net-worth tracker helps me see both movements together. That does not tell me whether a financial decision was good or bad, but it gives me a more honest view of the month.
There is a useful psychological benefit here. When I track only expenses, progress can feel invisible because responsible choices do not always produce an immediate reward. A net-worth baseline creates a broader measure. Paying down debt, adding to savings, or maintaining investments can become visible even when my daily spending looks ordinary.
The first win is not entering everything; it is creating a snapshot I can trust enough to revisit. I would save a note about what the snapshot includes, especially if I leave out a small account or an asset that is difficult to value. That reminder prevents me from comparing a partial starting point with a complete later update as though they were identical.
Tracking investments without confusing performance and progress
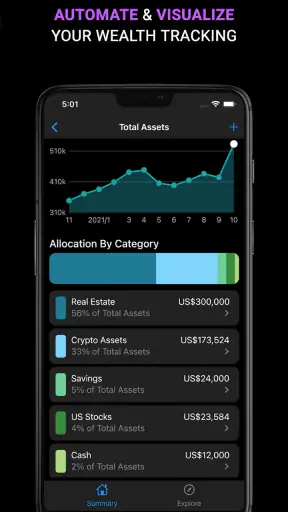
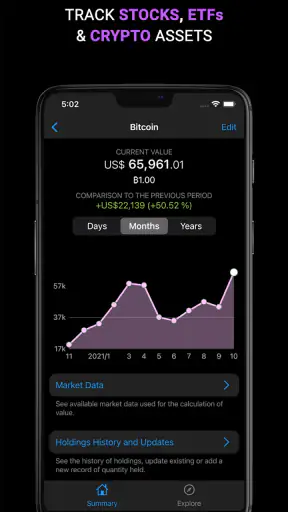
Sumio is particularly interesting for people who hold several types of investments. Stocks and funds can be viewed as parts of a wider portfolio rather than isolated numbers. That wider view helps answer practical questions: how much of my net worth is exposed to investments, how much remains in cash, and whether my financial progress depends too heavily on one area?
I would not use the total portfolio value as a direct measure of skill. Market prices move, and a higher number can reflect market conditions rather than a better decision. The app is more valuable as a record of the relationship between my holdings and the rest of my finances. If my portfolio grows while debt also grows, the headline number alone may hide an uncomfortable trade-off.
A good workflow is to update the figures on a regular schedule instead of reacting to every market movement. Checking constantly can turn a tracking tool into a source of anxiety. Reviewing after a meaningful interval gives the numbers more context and encourages decisions based on direction rather than a single fluctuation.
Another practical tip is to keep contributions separate in my own thinking from market gains. If the portfolio is worth more because I added money, that is different from earning a return. Sumio can help me observe the changing value, but I should interpret the change carefully. For a detailed return calculation, tax-lot analysis, or specialist investment research, a dedicated brokerage or portfolio application may be a better companion.
Assets and debts require honest estimates
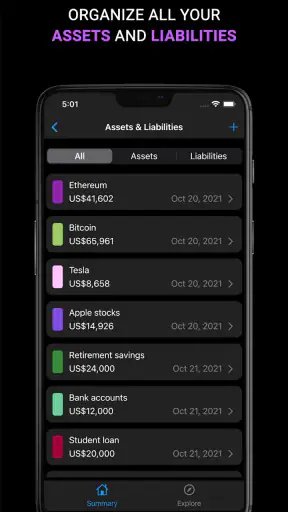
The asset side of net worth can tempt me into optimistic guesses. A car, electronics, collectibles, or property may have a purchase price that no longer reflects its realistic value. I would use a conservative estimate and update it only when there is a sensible reason to do so. Inflating assets makes the final total feel better but makes the tracker less useful.
Debts deserve the same attention. A credit balance or loan should be represented as an obligation, not mentally offset with money I hope to earn later. This is one of the strongest reasons to use a net-worth tool instead of looking only at savings. A person with substantial investments can still have fragile finances if repayment responsibilities are ignored.
For a household, I would decide whether the app is tracking only my finances or a shared picture. Mixing personal and household figures without a clear rule can make future changes difficult to interpret. If I include a partner’s account, shared property, or joint debt, I would apply the same approach each time. The app can show the result, but the quality of that result depends on the boundaries I choose.
Common points of confusion during regular use
The first confusion is usually the difference between net worth and spendable money. A home, long-term investment, or vehicle may contribute to net worth while remaining difficult to use for an unexpected bill. I would never treat the total shown by Sumio as my emergency cash balance. It is a measure of financial position, not a permission slip to spend.
The second issue is timing. If I update a bank account weekly but an investment only occasionally, the overall figure may jump even though my underlying situation has not changed dramatically. That is not necessarily an app problem; it is a consequence of uneven updates. I would record when major figures were last checked and avoid reading too much into short-term movement.
The third is currency and valuation context. When finances involve different countries, assets, or accounts, I would pay close attention to the units I am entering and keep a private note explaining any conversion. A total without context can look polished while hiding assumptions. This is especially important for investments whose value changes independently of my local currency.
Another point worth remembering is privacy in everyday use. A finance tracker contains sensitive information even when it does not move money itself. I would use a secure device lock, avoid entering data while someone is looking over my shoulder, and think carefully before sharing screenshots. Sumio is a viewing and tracking aid in my routine; it is not a substitute for the security controls of a bank or investment provider.
Where it differs from ordinary alternatives
A spreadsheet gives me maximum control. I can create custom formulas, add notes, and build elaborate charts. That flexibility is valuable for people who enjoy maintaining their own financial system, but it also creates more work and more opportunities for formula mistakes. Sumio offers a more focused path for someone who wants the net-worth concept without designing a workbook from scratch.
A standard budgeting app is usually better when the main problem is overspending. Those services tend to emphasize categories, transactions, monthly limits, and cash flow. Sumio is a better fit when I already understand my daily spending reasonably well and want to monitor the bigger balance sheet. Some people will benefit from using both: one for behavior at the point of purchase and one for long-term financial position.
Brokerage apps are stronger for placing trades, reading market information, and viewing detailed holdings. Sumio’s appeal is broader context. It can help me see an investment account alongside savings, debts, and other assets, whereas a broker naturally centers on the investments held there. I would not expect a net-worth tracker to replace the tools provided by the institution where my assets are actually held.
Manual tracking also has a trade-off. It can feel slower than an automatically connected service, but it may encourage me to understand what I own rather than blindly accepting a synchronized total. For users who want live balances with minimal effort, an account-aggregation service may be more convenient. For users who prefer deliberate reviews and a clear personal inventory, Sumio’s focused approach can be less distracting.
Who will get the most from it
I think Sumio is a good match for a first-time investor, someone consolidating accounts, or anyone who has reached the point where a simple bank balance no longer describes their finances. It is also useful for people preparing for a major life decision, such as moving home, changing jobs, or reviewing whether their savings and investments are moving in the right direction.
It can be especially helpful if I feel financially busy but cannot explain whether I am progressing. Entering the major pieces forces a useful inventory. I may discover that my savings are healthy but my debt is growing, or that my investments are concentrated while my cash reserve is thin. Those are not answers in themselves, but they are better questions than “how much money is in my main account?”
I would skip it if I want an automated, transaction-by-transaction budget and do not want to maintain figures myself. I would also look elsewhere if I need professional-grade investment analysis, tax reporting, trading, or detailed household permissions. The app’s value comes from its focused overview, not from trying to become every financial tool at once.
How I would make the habit stick
The best next step after setup is to choose a review rhythm that feels easy to maintain. I would use the same general point in each month, update the figures that have genuinely changed, and write down a short explanation for any large movement. That explanation is often more useful than the number itself because it connects the result to an action, a market change, a repayment, or a new asset.
I would also create two mental views: total net worth and liquid net worth. The first includes the broader picture; the second focuses on money and investments that could realistically support near-term needs. Even if I use Sumio primarily for the total, keeping those concepts separate stops a valuable but illiquid asset from giving me a false sense of security.
After several reviews, I would look for patterns rather than chase a perfect score. Is debt shrinking? Are contributions consistent? Is cash being left idle while short-term obligations increase? Is one holding dominating the investment picture? These questions turn Sumio from a static calculator into a decision aid, while still leaving the actual financial choices in my hands.
Fiduciary has kept the app free to download, with optional purchases available inside it. I would start with the basic experience and decide only after understanding whether the workflow fits my habits. The age rating of Everyone also makes it approachable for a broad audience, but younger users should still treat the figures as an educational overview and involve a trusted adult when financial decisions carry real consequences.
My final view after using the concept in daily life
Sumio: Net Worth Tracker is most convincing when I use it as a financial checkpoint rather than a constant dashboard. Its strength is the simple shift from isolated balances to a combined picture of assets, investments, funds, stocks, and obligations. That perspective can expose progress that a spending tracker misses and risks that a portfolio app hides.
It is not the right answer for everyone. Manual upkeep may feel like friction, and people seeking detailed budgeting, automatic bank synchronization, trading tools, or tax features should choose a more specialized service. But for a first-time user who wants to understand the shape of their finances without building a spreadsheet, Sumio offers a straightforward place to begin.
My recommendation is to install it with one small target: enter enough information to produce a sensible baseline, inspect what that number includes, and return for a consistent review later. If you treat the total as a guide rather than a verdict, the app becomes much more useful. That is where I see its real value: not in promising instant financial control, but in making the bigger picture visible enough for better decisions.
FAQ
What is Sumio: Net Worth Tracker used for?
Sumio: Net Worth Tracker is a personal finance app designed to help you monitor your overall financial position in one place. You can record assets such as cash, bank accounts, investments, property, and digital currencies, then subtract debts and liabilities to estimate your net worth. It is especially useful for people who want a clearer long-term view of their financial progress rather than only tracking monthly spending.
Can I connect my bank and investment accounts to Sumio?
Sumio may support account connections or manual financial entries depending on your country, device, subscription, and the services available through the app. Before relying on automatic synchronization, check which institutions and account types are supported in your region. Manual tracking is also available for assets or liabilities that cannot be connected, although it requires you to update balances and transactions yourself.
Is Sumio: Net Worth Tracker free to download and use?
The app can generally be downloaded without an upfront purchase, but some features may require a paid plan or subscription. Premium access can include expanded tracking options, more detailed insights, additional account support, or advanced organization tools. Review the pricing, trial period, renewal terms, and cancellation instructions in the App Store or Google Play before starting any subscription.
How secure is my financial information in Sumio?
Because Sumio deals with sensitive financial information, security should be considered before adding accounts or balances. If you connect external institutions, review the permissions and the provider used for synchronization, and enable device security such as a passcode or biometric lock. Avoid entering information on an unsecured network, and read the app’s privacy policy to understand how data is stored, processed, and shared.
Is Sumio suitable for budgeting, investing, or tax advice?
Sumio is primarily focused on tracking net worth and organizing a broad picture of your finances. It can help you observe assets, debts, and changes over time, but it should not be treated as a replacement for a full budgeting service, professional investment management, or tax advice. Always verify balances and calculations, and consult a qualified financial professional before making important financial decisions.











