

Subscription Manager: Reko
4.2FinanceUpdated October 2, 2026
Screenshots
Pros
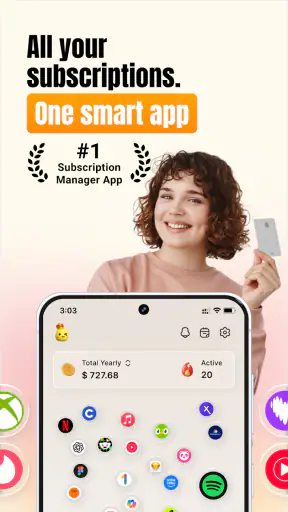
- Tracks recurring payments and renewal dates in one place.
- Supports custom billing cycles for subscriptions and memberships.
- Clear overview helps identify unused or expensive services.
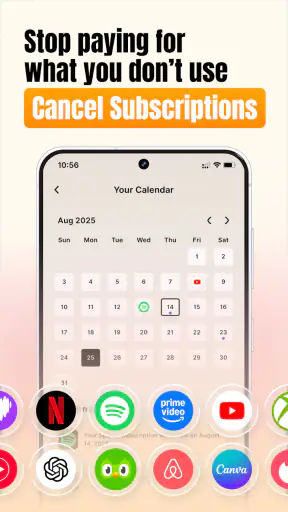
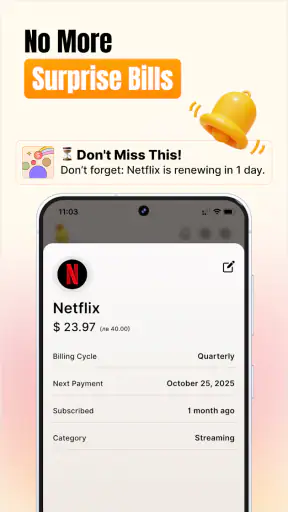
- Useful reminders can reduce missed cancellations and charges.
- Simple interface makes adding and reviewing subscriptions quick.
Cons
- Some advanced features may require a premium subscription.
- Manual entry can be time-consuming for users with many services.
- No guarantee that every regional provider is supported.
- Reminder accuracy depends on correctly entered billing information.
- Privacy-conscious users may hesitate to store financial details.
 Analysis By Mobexer
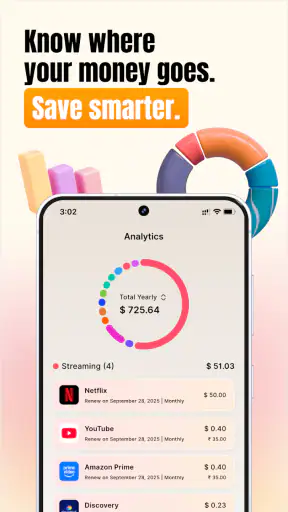
Managing subscriptions sounds simple until several small charges begin landing on different days, each with its own renewal cycle. Subscription Manager: Reko is a finance app from Playground Studio LLC built around that exact problem. I found its appeal in the way it turns scattered subscription reminders into something I can review in one place, rather than relying on memory, email searches, or separate calendar entries.
The app focuses on recurring commitments: subscriptions, bills, renewals, and trials. That makes it more specialized than a general budgeting app, but also more useful when the main question is, “What am I still paying for, and when will it renew?” It is available for free, has an Everyone content rating, and runs on Android devices using version 7.0 or later. Its current version is 3.0.11, and the app was released on May 13, 2025.
I would not describe Reko as a complete replacement for a bank app or a full household budget. Its strength is narrower and more practical: it gives recurring expenses a dedicated home. If you have ever started a free trial, forgotten about it, and noticed the charge only afterward, that focus is immediately understandable.
How Reko handles recurring money commitments
A focused alternative to a general finance app
Most banking apps show transactions after they happen. General budgeting tools help categorize spending across groceries, transport, rent, and entertainment. Reko approaches the problem from a different direction by asking you to think ahead about the payments that repeat. That distinction matters because a future renewal is easier to act on before it leaves your account.
In my view, the app is most useful as a planning layer. I would use it alongside a bank account, not instead of one. The bank remains the source for completed transactions, while Reko can serve as a forward-looking list of services and bills that deserve attention. This separation keeps the purpose clear and avoids expecting one small app to perform every financial task.
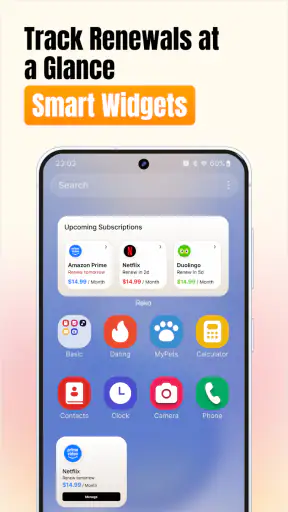
The store summary emphasizes finding subscriptions, cancelling app subscriptions, and tracking bills, renewals, and trials. I read that as a workflow centered on awareness and action. The app is not merely a list of monthly charges; its practical value comes from helping me notice a commitment before the next payment date becomes an unpleasant surprise.
The first setup is where the value is created
An organizer like this is only as useful as the information entered into it. The first session may require patience because I need to identify the services I actually use, distinguish active subscriptions from forgotten trials, and enter the renewal details carefully. That work is not glamorous, but it is the point at which Reko can expose spending that has become invisible through repetition.
I would begin with the services I know are recurring, then check recent bank or card activity for anything I missed. After that, I would review the list by renewal date rather than by brand. This is a small but important habit: seeing several payments clustered around the same period can reveal a cash-flow problem even when each individual charge seems affordable.
A useful second pass is to mark subscriptions that are seasonal, temporary, or tied to a specific project. A service used only during a short course or a holiday can easily become permanent by accident. Keeping those commitments visible gives the app a role beyond simple record-keeping.
Free access and paid value
Reko is listed as a free app, so there is no purchase required simply to install it and evaluate whether its approach suits me. That makes the decision relatively low-risk for someone who wants a dedicated subscription tracker rather than another paid budgeting product. The listing also shows in-app purchases ranging from $4.49 to $8.99 per item.
Those purchases are worth considering as optional value rather than an automatic requirement. I would first use the free access to see whether maintaining the list fits my routine. If the app becomes the place where I reliably catch renewals and review recurring costs, a paid item may feel reasonable. If I rarely open it or already manage everything effectively through a calendar and spreadsheet, spending more would not solve the real problem.
The important distinction is that the free entry point lets me test the workflow, while the paid items represent an additional choice rather than a reason to assume the app is fully paid. I would judge that value by consistency: does Reko make me take action earlier, or does it merely duplicate information I already track elsewhere?
A realistic everyday scenario
Imagine I sign up for a short trial on a Monday, renew a streaming service later that week, and have a utility bill due near the end of the month. Without a dedicated view, these commitments may live in different emails, app stores, and account pages. I could remember the trial for a few days, then lose track of it among ordinary notifications.
With Reko, I would record the trial when I start it, add the recurring service, and include the bill in the same review routine. Before the next renewal period, I could scan the list and decide which services still deserve the money. The benefit is not that the app makes the cancellation decision for me; it is that the decision becomes visible at a useful time.
That workflow is especially valuable after moving, changing jobs, or returning from travel. Those transitions often introduce temporary subscriptions and new bills. A dedicated list can prevent temporary arrangements from quietly becoming part of the permanent monthly budget.
Where it fits beside familiar alternatives
A calendar is often enough for people who have only a few annual renewals. A spreadsheet is more flexible for users who want custom formulas, shared household planning, or detailed spending analysis. A bank’s recurring-payment view may be better for discovering charges automatically because it reflects actual account activity.
Reko makes more sense when I want a purpose-built interface for subscriptions and trials without building the structure myself. Compared with a calendar, it keeps related commitments together. Compared with a spreadsheet, it should require less maintenance once the entries are organized. Compared with a bank app, it can be used for planning rather than waiting for a transaction to appear.
The trade-off is that a focused tracker may not replace the broader visibility of a full financial tool. If I need income planning, debt repayment, investment tracking, or shared budgets, I would choose a more comprehensive finance app. Reko is strongest when the recurring-payment problem is the specific problem I want to solve.
Three habits that make the app more useful
First, I would use it during a monthly “renewal audit,” not only when a charge looks suspicious. A regular review turns the app into a decision tool. I would ask whether each service was used during the previous period, whether a cheaper plan is available directly from the provider, and whether the next renewal still matches my priorities.
Second, I would enter trials immediately rather than waiting until the final day. The practical advantage of early entry is psychological as much as organizational: the trial becomes a commitment with a deadline, not a free benefit that feels unrelated to future spending. This is one of the clearest ways a subscription tracker can prevent avoidable charges.
Third, I would separate essential bills from optional subscriptions in my own review routine. A renewal for a necessary service deserves a different decision from an entertainment subscription I barely use. Even if the app presents both within the same finance category, my personal review should distinguish “must keep” from “keep only if worthwhile.” That makes cancellation decisions faster and less emotional.
What may feel inconvenient
The biggest limitation is the need for accurate upkeep. A tracker cannot know that I cancelled a service unless I update the record or otherwise follow the app’s workflow. If I change plans, pause a subscription, switch billing providers, or receive a promotional period, the details can become outdated. The convenience of a central list depends on my willingness to maintain it.
That manual responsibility also means I would not treat the app as proof that every recurring charge has been found. I would still compare the list with bank statements and email receipts, especially during the initial setup. A tracker can organize known commitments very well while still missing a forgotten service that I never entered.
Another possible friction is the boundary between tracking and cancellation. The store summary presents cancellation as part of the app’s purpose, but I would still expect the actual cancellation process to involve the relevant app store or service provider. In practical terms, Reko can help me identify what needs attention, while the provider remains the place where the subscription status is ultimately changed.
The in-app purchase range also deserves a measured approach. Since the app is free to try but includes paid items, I would avoid paying immediately simply because the feature set sounds useful. I would first establish a routine and confirm that the app reduces missed renewals or saves review time. The purchase is easier to justify after that test than before it.
Who will get the most from Reko?
I think Reko is a good match for people with several digital subscriptions, recurring household bills, or a habit of starting trials and forgetting them. It may also help anyone who has recently realized that small recurring charges are taking up more of the budget than expected. The app’s narrow focus can be an advantage for users who find full budgeting tools too complicated.
It is particularly suitable for someone who prefers a visual checklist of future commitments. Instead of analyzing every past transaction, that person can concentrate on upcoming renewals and decide what deserves another billing cycle. The app may also suit a user who wants to begin organizing finances without committing to a large, feature-heavy system.
Families and couples should think carefully about shared responsibility before relying on it. A single personal list can become incomplete when several people subscribe to services independently. It may still be useful as a household reference, but only if everyone agrees on who records changes and who checks the upcoming renewals.
Who should choose something else?
I would skip Reko if my main goal were automatic account synchronization, detailed spending categories, investment management, or a full debt-payoff plan. Those needs go beyond subscription organization. A bank tool may be more appropriate for transaction discovery, while a comprehensive budgeting platform may offer better support for income, savings, and shared financial goals.
I would also hesitate if I dislike manual entry and rarely review financial information. The app can remind me to look at commitments, but it cannot create a lasting habit on my behalf. Someone with only one or two recurring payments may get more convenience from a calendar reminder, especially if those payments are already easy to see in a bank account.
People who need iOS-specific guidance should check the platform availability before deciding, because the app information identifies it as an Android finance app with a minimum operating-system requirement of 7.0. For Android users on supported software, the technical entry barrier is modest; the more important question is whether the focused workflow matches their needs.
How established does it feel?
Reko has an average rating of 4.2 from around 275 ratings, with 10 written reviews, and it has passed 10K+ installs. Those figures suggest an app with an existing user base but not the scale of a dominant mainstream finance service. I would interpret that as a reason to evaluate the experience personally rather than relying on popularity alone.
The developer is Playground Studio LLC, and the current version is 3.0.11. A current version number can be reassuring when an app deals with an area that benefits from ongoing maintenance, although the real test for me remains whether the interface stays clear and the tracking workflow remains dependable over time.
The Everyone rating makes the app broadly approachable from a content perspective. That does not mean every financial situation is equally well served, however. A simple subscription list is helpful for awareness, but serious financial decisions still require checking original account records and provider terms.
My buy-or-skip verdict
I would recommend trying Reko if recurring charges are the specific source of financial clutter. The free access makes it sensible to test without committing money first, and the focused design should appeal to anyone who wants a clearer view of subscriptions, bills, trials, and renewals. My strongest recommendation is to use it as part of a repeatable review habit rather than as a one-time cleanup tool.
I would consider an in-app purchase only after confirming that the free experience genuinely improves my routine. The listed paid items cost between $4.49 and $8.99 each, so the value depends on whether the added capability saves time or prevents a costly forgotten renewal. I would not buy simply because I want a more complete finance system; Reko is not intended to replace one.
My final view is that Reko earns its place as a focused subscription organizer, not as an all-purpose money manager. It is most convincing when I have several recurring commitments and need a single place to review them before they renew. It is less compelling for someone who already has reliable calendar reminders, automatic bank tracking, or a detailed budgeting setup. For the right user, that narrow purpose is exactly what makes the app useful.
FAQ
What is Subscription Manager: Reko used for?
Subscription Manager: Reko is designed to help you organize and monitor recurring payments in one place. You can record services such as streaming platforms, cloud storage, memberships, software plans, and other subscriptions, then review their prices and renewal dates. This makes it easier to understand where your money goes and avoid forgetting upcoming charges.
Can Subscription Manager: Reko remind me before a subscription renews?
The app is intended to help users keep track of renewal schedules and may provide reminders or notifications for upcoming payments, depending on the features available in the installed version and your device settings. Before relying on it for important billing dates, check that notifications are enabled and that each subscription has the correct renewal date, billing cycle, and reminder preference.
Does Subscription Manager: Reko connect directly to my bank account?
Subscription Manager: Reko primarily works as a personal subscription-tracking tool, so you should not assume that it automatically detects every payment from your bank or credit card. In many cases, subscription details need to be entered or maintained manually. This can take a little time initially, but it also gives you control over the information stored in the app.
Is Subscription Manager: Reko free to download and use?
The availability of free and premium features can vary by platform, app version, region, or subscription plan. Before downloading, review the current Google Play Store or App Store listing for pricing, in-app purchases, trial conditions, and renewal terms. If the app offers a premium plan, remember that deleting the app usually does not cancel an active store subscription.
Is my subscription information safe in Subscription Manager: Reko?
Because you may enter prices, renewal dates, service names, and other personal budgeting information, it is worth reviewing the app’s privacy policy and requested permissions before use. Avoid entering sensitive banking credentials unless the official listing clearly explains why they are needed. Also protect your phone with a lock screen and keep the app updated to benefit from security and stability improvements.











