

Split Pay: Split Bills in Two
4.8FinanceUpdated October 5, 2026
Screenshots
Pros
- Quickly divides bills between two people
- Useful for meals
- trips
- and shared everyday expenses
- Simple interface with minimal setup required
- Helps avoid awkward manual calculations
- Makes each person’s share clear before paying
Cons
- Designed mainly for two-person splits
- May not support complex custom arrangements
- Both users may need to confirm the final amounts
- Limited usefulness without accurate bill details
- Availability of payment features may vary by region
 Analysis By Mobexer
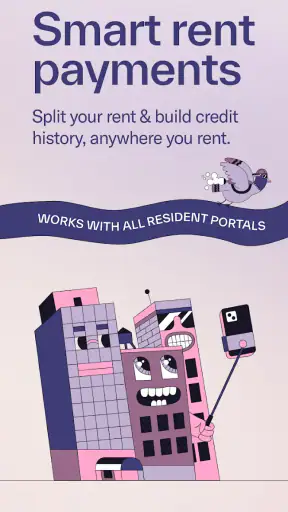
I usually judge a finance app by what it lets me control, not by how polished its first screen looks. With Split Pay, I found a focused tool built around dividing large household payments into smaller parts. Its store summary points to rent, mortgage, and car payments, and that narrow purpose is important: this is not trying to replace a full budgeting app or become a general banking dashboard.
Split Pay is a free finance app from Split Pay, available for users aged Everyone. It has earned a 4.8 average from around 3.3 thousand ratings, with more than 100 thousand installs. Those figures suggest that the idea is easy for people to understand, but they do not remove the need to think carefully about how a payment tool fits into your own financial routine.
My overall impression is that the app makes sense for someone who wants a simpler way to approach a recurring bill, especially when a single due date creates pressure. I would still treat it as a payment-management aid rather than a complete financial plan. The difference matters, because splitting the timing of a payment can improve cash flow without reducing the total amount you owe.
What Split Pay is really useful for
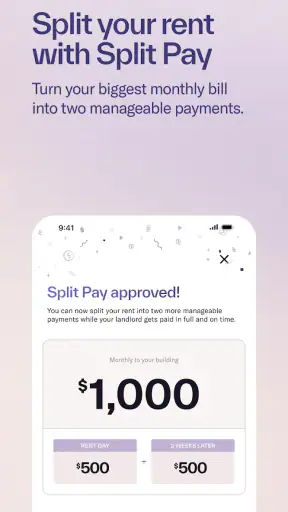
The best way to understand this app is to imagine a normal month. Your rent or mortgage is due at one point, your salary arrives at another, and your other commitments land somewhere in between. Instead of treating the large payment as one isolated event, Split Pay is designed around the idea of handling it in two parts.
That can be useful for people paid on a regular schedule who prefer to reserve money gradually. For example, I can imagine using the first part of a paycheck to prepare one portion of the housing payment, then using the next part to complete the remaining portion. The benefit is not that the bill becomes cheaper; the benefit is that the payment feels less like one sudden hit to the account.
This approach also suits couples or housemates who already share responsibility for one major expense. Rather than relying on a spreadsheet and separate reminders, a dedicated app can give the split-payment routine a clear home. The practical value depends on whether everyone involved follows the same arrangement, so I would agree on dates and responsibilities before making it part of a household system.
Car payments are another sensible use case. A fixed vehicle payment can compete with groceries, utilities, insurance, and fuel during a busy month. Dividing the preparation for that payment may make the budget easier to manage, particularly for someone who prefers small, planned actions over one large transfer.
There is an important trade-off here. A split schedule can create a stronger habit, but it can also make your finances feel more complicated if you already have many scheduled transactions. I would use it for one or two significant obligations first. Adding every bill at once could defeat the simplicity that makes the concept appealing.
A calmer way to handle a large due date
The most useful change is psychological as much as practical. When I see a large recurring payment approaching, I tend to think about the amount that must be available on the final date. A two-part approach changes the question to: what should I set aside now, and what remains for later?
That makes Split Pay particularly relevant for people who are paid twice during a billing cycle. It can also help someone who has irregular spending around a fixed obligation, although I would be more cautious in that situation. If income changes from week to week, a rigid split may not match reality, and the app should not be treated as permission to promise money you do not yet have.
A useful habit is to check the full month before committing to a split. Look at the payment date, expected income, essential spending, and any automatic withdrawals. Then decide whether the two portions leave enough room for everyday needs. This small review prevents a common mistake: focusing on the divided bill while forgetting that the rest of the month still has to work.
I also recommend keeping a simple note outside the app with the original total and the final deadline. That gives you a quick reference if you need to explain the arrangement to a partner, landlord, lender, or anyone else connected with the payment. The split is a planning method; it should never make you lose sight of the actual obligation.
Where it fits beside ordinary alternatives
The usual alternative is a banking app with scheduled transfers, a calendar reminder, or a spreadsheet. Those options can be enough when you only need to remember a date. A spreadsheet gives you more freedom and can include income, bills, savings, and debt in one place, but it also requires more manual upkeep.
Split Pay has a more specific appeal because its purpose is easier to understand than a general budget workbook. If your main problem is preparing for rent, a mortgage, or a car payment in two stages, a focused tool may feel less demanding than building a complete financial system. On the other hand, someone who wants category tracking, long-term forecasting, or a broad view of spending may be better served by a full budgeting app or their bank’s own tools.
I would also distinguish it from borrowing or credit. Splitting the preparation for a payment is not the same as receiving extra money. If your account cannot cover the eventual bill, changing the timing does not solve the shortfall. That is the central limitation to keep in mind, and it is why I see this as a cash-flow organizer rather than a solution for unaffordable expenses.
Trust, controls, and moments that deserve care
For a finance app, trust starts with clear user choices. I pay attention to when an app asks me to create an account, connect financial information, approve a payment, or allow notifications. Each step should have a clear purpose. With a tool centered on major household payments, I would not rush through setup simply because the concept sounds convenient.
The app is maintained by Split Pay and was released on December 5, 2023. Its current version is 2.0.4, and it requires an operating system version 10 or newer. Those details matter when deciding whether an older phone can run it and when checking that you are using the current build available for your device.
I would begin by reading every setup screen rather than tapping through automatically. Pay attention to the payment amount, the two portions, the relevant dates, and any confirmation before accepting an action. If a screen presents a choice about notifications, account access, or payment authorization, I would make that choice deliberately instead of assuming the default is right for me.
The safest workflow is to verify the total, timing, and destination before confirming anything. This is especially important for rent, mortgage, and vehicle obligations, where a missed or misdirected payment can have consequences beyond a minor inconvenience.
Account control should come before convenience
Before relying on the app for a critical payment, I would make sure I understand how to review or change the arrangement. Can I see what is scheduled? Can I correct an amount before it is processed? Can I stop using the split plan without losing track of the original bill? These are the practical questions I would answer through the visible controls and help information inside the app.
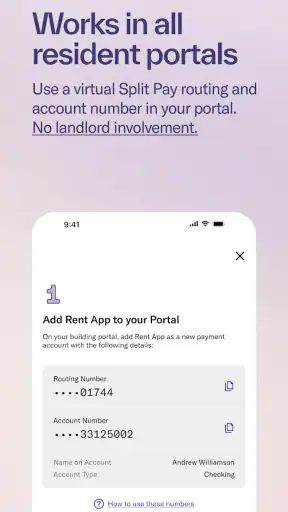
I would also confirm which account or payment method is involved whenever the app presents that information. A familiar name on a screen is not enough; the final details should match the account I intend to use. If another person shares responsibility for the bill, I would show them the plan rather than assuming they understand it automatically.
Notifications deserve the same attention. Reminders can be helpful, but they can also expose financial information on a lock screen or create unnecessary noise. I would choose notification settings that fit my privacy needs and review them after the first payment cycle. A reminder is valuable only if it arrives at a useful time and does not make sensitive details visible to anyone nearby.
My advice is to start with a payment that you can monitor closely, not the most complicated obligation in your life. Watch how the two-part process fits your bank balance and your household routine. Once you understand the flow, you can decide whether it deserves a place in more important monthly planning.
Data-sensitive moments to handle carefully
Finance apps naturally bring sensitive moments into everyday tasks. Entering a housing payment, reviewing an account, or discussing a vehicle obligation can reveal information about your finances. I would read the app’s privacy and account screens before entering more information than the task requires, and I would avoid using a shared device unless I am comfortable with the account being accessible there.
I would also keep my phone protected with its normal device security and avoid handing an unlocked device to someone else while the app is open. That is basic advice, but it becomes more important when an app is connected to recurring payments. A strong device passcode and careful sign-out habits reduce avoidable exposure.
When the app asks for access or permission, I would consider whether the request matches the action I am trying to perform. If I am only reviewing a split schedule, I should not casually approve something I do not understand. The right choice may differ from person to person, but the principle is consistent: use only the access and account connections you understand and genuinely need.
I would be particularly careful with messages that appear to demand an urgent payment or ask for credentials outside the normal app flow. Even when a finance tool is legitimate, users can encounter misleading messages elsewhere. I would return to the app through the normal device icon and verify details there instead of acting from an unexpected prompt.
Who should use it, and who should skip it
Split Pay is a good match for someone with a predictable large payment who wants to prepare in two stages. It may also suit a household that needs a shared routine for one major expense and prefers a focused finance tool over a broad budgeting platform. The free price makes it easy to try without adding another subscription decision to the monthly budget.
I would be more cautious if your income is highly irregular, your payment dates change often, or you already struggle to track several transfers. In those situations, a complete budget with a clear cash-flow forecast may be more useful. The same is true if your main goal is debt reduction, investment planning, expense categorization, or monitoring all accounts in one place.
Someone who expects the app to reduce the amount owed should skip it, or at least reset that expectation. The value is in organizing timing and attention. It cannot replace sufficient income, a realistic budget, or communication with the party receiving the payment.
For couples and housemates, I would establish responsibility in writing, even if that is only a shared note. Decide who checks the schedule, who confirms the money is available, and what happens if one person is late. The app can support the routine, but it cannot resolve disagreement about who owes what.
My practical routine for trying it
I would start by selecting one recurring obligation and writing down its full amount and due date. Next, I would compare the suggested two-part approach with the dates when money actually enters my account. If the split creates a shortage before the final date, I would not proceed simply because the schedule looks tidy.
After setting it up, I would check the arrangement again before each portion is due. I would compare the displayed details with my own bank records and keep the original bill available. This double-check is not wasted effort during the first cycle; it is how I learn whether the app’s workflow fits my real life.
Once the first cycle is complete, I would ask three questions: did the reminders arrive when useful, did the two portions match my income pattern, and did I always understand what action was being taken? If the answer to any of these is no, I would return to a calendar or banking routine rather than forcing the app into my finances.
The app’s Everyone age rating makes it broadly approachable, but financial responsibility still depends on the individual user. A younger user or anyone sharing responsibility for a household payment should involve the person who ultimately controls the bank account and the bill. Easy navigation does not remove the need for adult oversight when the payment is significant.
A cautious verdict after looking at the whole experience
I like the clarity of the idea. Split Pay takes a stressful type of financial task and frames it as two planned steps, which can be easier to follow than one large deadline. The strong user response, including a 4.8 average from roughly 3.3 thousand ratings, supports the impression that the concept resonates with many people.
Still, I would not use it as my only financial control center. Its focused approach is an advantage for rent, mortgage, and car-payment planning, but that same focus makes it less suitable for anyone seeking a complete picture of spending and savings. A bank app may be better for direct account oversight, while a full budgeting tool may be better for long-term planning.
My recommendation is to try it with a manageable recurring payment, read each control carefully, and keep an independent record of the original amount and deadline. Treat every account connection and notification choice as a decision, not a formality. If the two-part routine genuinely matches your income schedule, it can make a major payment feel more organized without adding much mental clutter.
In the end, I see Split Pay as a useful specialist rather than a universal finance solution. It is free, available for modern devices, and aimed at a clear everyday problem. I would recommend it to someone who wants structure around one large payment and understands that splitting the timing is not the same as lowering the cost. Used with that awareness, it can be a practical addition to a careful household routine.
FAQ
What is Split Pay: Split Bills in Two used for?
Split Pay: Split Bills in Two is designed to make shared expenses easier to manage. It can help divide a restaurant check, household purchase, trip cost, or other payment between two people. Instead of calculating each person’s portion manually, you enter the bill details and use the app to work out how much each participant should contribute.
Can Split Pay divide a bill equally and unevenly?
The app is mainly intended for splitting a bill between two people, and its usefulness depends on the payment options available in the version you install. For a simple 50/50 split, the calculation should be straightforward. If one person paid more, ordered different items, or needs to cover a different share of tax or tip, check the available fields carefully before relying on the final amount.
Does Split Pay: Split Bills in Two include tips, taxes, or additional charges?
Shared bills often include more than the original item prices, so it is important to confirm how Split Pay handles tips, taxes, service fees, and other extras. Depending on the app’s current design, these amounts may need to be entered separately or included in the total manually. Always compare the result with the receipt to avoid an incorrect split.
Is Split Pay: Split Bills in Two free to download and use?
The availability of free features, advertising, and optional paid tools can vary by platform and app version. Before downloading, review the Google Play Store or Apple App Store listing for the current pricing information, in-app purchases, and subscription details. Also check whether the basic bill-splitting calculator works without payment, an account, or an internet connection.
Is Split Pay safe for entering payment or personal information?
A bill-splitting app should generally only require the amounts needed for the calculation, but you should still review its privacy policy and requested permissions before use. Avoid entering card numbers, banking credentials, or sensitive financial information unless the official listing clearly explains why it is necessary. Download the app only from a trusted store and keep it updated.











