

Simple Checkbook Ledger
3.4FinanceUpdated October 2, 2026
Screenshots
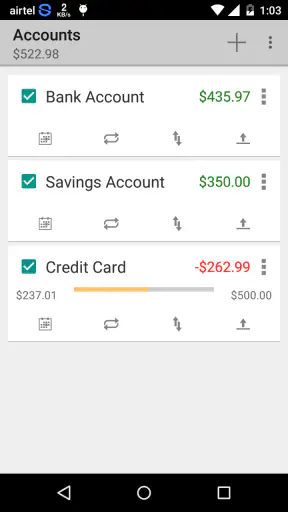
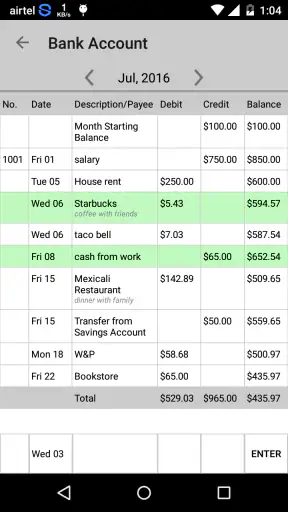
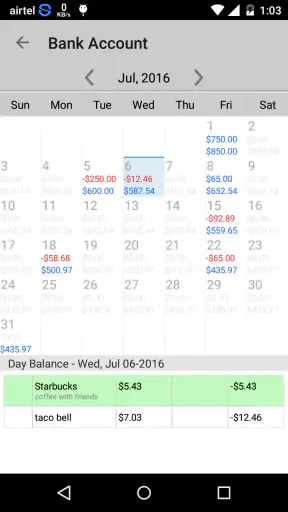
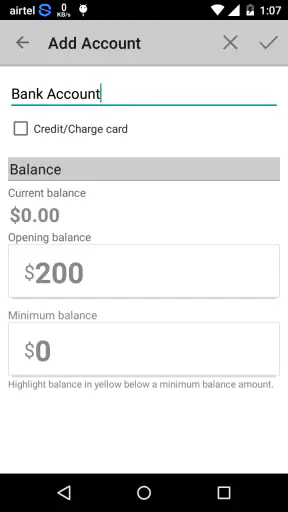
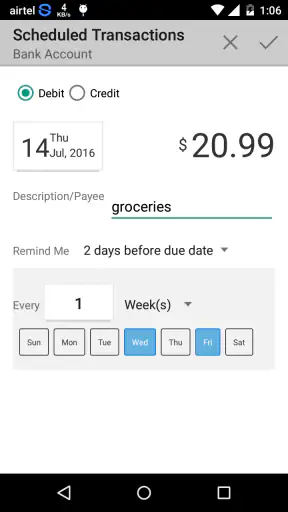
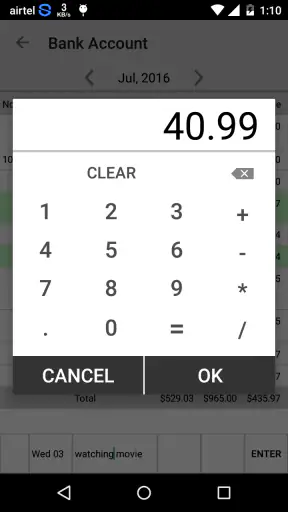
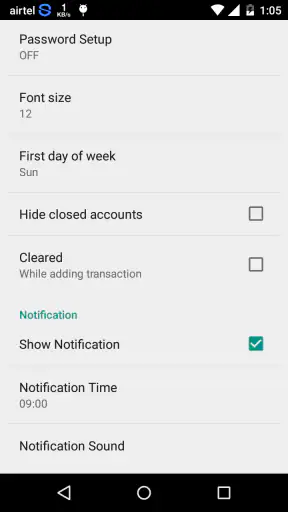
Pros
- Clean
- straightforward interface for recording income and expenses.
- Works well for users who prefer manual control over their finances.
- Useful checkbook-style balance tracking without unnecessary features.
- Lightweight app with low storage and battery requirements.
- Helps separate transactions into different accounts or ledgers.
Cons
- Manual data entry can become time-consuming for frequent transactions.
- May feel too basic for users wanting full budgeting tools and reports.
- Limited automation compared with apps that sync directly with banks.
- Users must maintain accurate records to keep the balance reliable.
- Some advanced features may require an upgrade or in-app purchase.
 Analysis By Mobexer
I tend to trust finance apps that keep their promises small. Simple Checkbook Ledger is built around that idea: it is a free finance app from Teelu Apps for recording money coming in and going out, rather than trying to become a complete banking platform. After spending time with it, I see its main appeal clearly. It gives people a straightforward place to maintain a personal checkbook-style record, especially when a bank balance alone does not explain where the money went.
The app has been available since August 3, 2016, and its current version is 3.5. That long presence gives it a more established feel than a brand-new budgeting experiment, although its average rating of 3.4 from around 2.5 thousand ratings suggests that the simple approach will not suit everyone. It is rated for Everyone, costs nothing to install, and has passed 100 thousand installs. Those details make it easy to try, but they do not remove the need to understand what kind of financial tool this really is.
How Simple Checkbook Ledger feels in everyday use
A focused alternative to a full budgeting suite
I would describe this as a manual ledger first and a budgeting assistant second. That distinction matters. Many modern finance apps concentrate on connecting to bank accounts, importing transactions, sorting spending automatically, and presenting colorful reports. A checkbook ledger takes the opposite route: you enter the financial activity yourself and use the running record to understand your available balance.
That can sound old-fashioned, but manual entry has a practical advantage. It makes each transaction deliberate. When I record a grocery purchase, a bill, or a payment received, I am forced to acknowledge it instead of waiting for an automatic feed to classify it later. For someone who wants awareness rather than a dashboard full of categories, this narrower design can be more useful than a larger app.
The trade-off is equally clear. The app depends on consistent input. If I forget to record a purchase, the ledger becomes less trustworthy. If I enter the wrong amount, the running balance can mislead me. This is not a flaw unique to this application, but it is the central responsibility that comes with choosing a checkbook-style workflow.
Why the interface can feel quick
Because the purpose is limited, routine actions should feel more direct than they would in a feature-heavy financial suite. There is less conceptual distance between opening the app and recording an expense. I do not need to think about linking an institution, waiting for a transaction feed, or correcting an automated category before the entry becomes useful.
That apparent lightness is one of the app’s strongest qualities. On a phone used for small daily updates, a compact ledger is easier to approach than a large financial control center. A person who only wants to maintain a personal spending record is unlikely to benefit from many layers of charts and account synchronization.
Still, “simple” should not be confused with effortless. The app cannot make financial discipline automatic. Its speed helps only when I already know the amount and purpose of a transaction. It is fast as a record-keeping tool, not necessarily as a way to investigate several months of complicated spending.
A realistic daily routine
Imagine checking out at a supermarket on the way home. Instead of relying on memory until the end of the week, I can enter the purchase while the receipt is still in my hand. Later, when a utility payment clears, I add that separately. The value is not in producing an impressive financial report; it is in keeping the balance close to reality throughout the month.
This routine also helps with pending commitments. If I have written a check or scheduled a payment that has not yet appeared in my bank activity, a personal ledger can remind me that the money is already mentally allocated. That is an important difference between looking only at a bank balance and maintaining a forward-looking record.
My practical advice is to choose one consistent moment for entries. Some people will prefer recording immediately; others may collect receipts and update the ledger once each evening. The second method can work, but only if receipts are kept together. The app is most useful when it becomes part of a repeatable habit rather than a place I visit only after a balance looks surprising.
What happens during heavier use
Light daily use is the natural environment for this kind of application. The more demanding situation is not a single large transaction but a long session of catching up after several days or weeks. Entering many purchases in one sitting increases the chance of skipped receipts, duplicated amounts, and inconsistent descriptions. That is where the simplicity of the tool becomes both helpful and limiting.
The focused workflow means I am not navigating a complicated financial model while catching up. However, manual work still takes time, and no compact ledger can remove the attention required to reconstruct a messy spending history. If I regularly postpone entries, a bank-connected service or a spreadsheet with bulk editing may be more efficient.
A useful approach is to separate maintenance from review. I would use the app for recording transactions as they happen, then choose a quiet moment to inspect the running balance and look for entries that need correction. Trying to analyze every purchase while entering it can make the process feel slower and less reliable.
Stability and confidence in the record
For a finance app, reliability is not only about whether it opens. It is also about whether I can trust the record after an interruption, a mistaken entry, or a period away from the app. A ledger becomes valuable when it preserves a clear history that I can return to, rather than forcing me to reconstruct decisions from memory.
I would therefore treat careful review as part of using Simple Checkbook Ledger. After entering an important payment, I would check the amount and the resulting balance before closing the app. That extra second is worthwhile because a small typo in a financial record can create confusion later. The app’s straightforward purpose makes this verification easy to understand, even though it does not eliminate the need for it.
Recovery is another matter of personal routine. If I change phones, remove the app, or lose access to the device, I would not assume that a manually maintained ledger is automatically available everywhere. Before making it the only record of important finances, I would investigate the app’s own options for preserving or moving records and keep any essential information in a separate, secure place. That is sensible practice for any finance tool, particularly one centered on personal entries rather than an institution’s live account history.
This caution does not make the app unsuitable. It simply defines its role. I see it as a convenient personal register, not as a replacement for official statements, receipts, or records needed for tax and legal purposes. For everyday awareness, that distinction is manageable. For formal accounting, I would choose a more specialized system.
Device requirements and practical limits
The minimum operating-system requirement is version 11, so anyone using an older device should check compatibility before planning a switch. On supported hardware, the app’s narrow purpose should be less demanding than a finance product built around constant visual reports or background account updates. That makes it a sensible candidate for people who want a focused tool rather than another resource-heavy service competing for attention.
Even so, perceived performance depends on more than the app’s size or design. A crowded phone, an aging battery, and an outdated operating system can make any finance app feel less responsive. I would judge this application mainly by how quickly it lets me complete a small entry and return to what I was doing, not by expecting it to behave like a full desktop accounting package.
The version number also matters when comparing experiences with another user. Version 3.5 is the current release identified here, and people on different devices may notice differences caused by their operating system or phone hardware. I would keep the app updated through the normal store process, especially for a finance tool where dependable day-to-day access matters.
Who will get the most from it
I think this app is a good match for someone who wants to track a personal account manually, prefers a checkbook metaphor, and does not want to hand over account access to an automatic aggregator. It can also suit a person who uses cash often, since cash spending may not appear in a bank feed at all. Recording those purchases by hand gives the ledger a broader picture of actual spending.
It may be useful for a household member who needs a simple shared routine, provided everyone agrees on when and how entries are made. The key is consistency: one person recording every transaction while another records only large purchases will produce an incomplete balance. A short note or agreed naming style can prevent confusion when reviewing the ledger later.
I also see value for people learning to pay closer attention to money. The manual process can teach the relationship between an individual transaction and the remaining balance more effectively than an automatically updated app that silently absorbs every purchase. It is a small amount of friction, but in this context that friction can encourage better awareness.
Who should choose something else
I would not recommend it as the first choice for someone who expects automatic bank synchronization, detailed spending categories, investment tracking, shared household controls, or sophisticated financial forecasts. Those users are likely to feel constrained quickly. A full budgeting service or accounting application will usually be better when several accounts, recurring obligations, and multiple people need to work from the same current information.
It is also a poor fit for anyone who knows they will not enter transactions regularly. The app cannot compensate for missing data. If the main goal is to see a bank account’s activity without manual effort, an institution’s own application or an account-aggregation service will be more convenient, assuming the user is comfortable with that connection.
People handling business books should be especially cautious about using a personal checkbook ledger as their main system. Business records often require invoice tracking, receipts, tax categories, reconciliation, and reporting. A simple personal ledger can support a small side routine, but it should not be mistaken for dedicated bookkeeping software.
Cost, purchases, and the value question
The app is free to use at the entry level, while in-app purchases are listed at $1.99 per item. That makes the initial decision uncomplicated: install it, test the recording flow, and see whether the ledger habit fits before spending anything. I would avoid paying for an optional item until I had used the basic workflow long enough to know exactly what problem the purchase solves.
This pricing structure is reasonable for a focused finance utility, but value depends on expectations. If I only need a small personal register, a free version may be enough. If I need features associated with a larger budgeting platform, a low-cost add-on will not necessarily turn this app into that different kind of product. The important question is not whether the price is small; it is whether the app’s narrow design matches the job.
Small habits that improve the experience
My first tip is to record transactions using descriptions that will still make sense later. “Payment” is less helpful than identifying the bill or purpose in plain language. A ledger is not merely a list of amounts; it is a memory aid. Clear wording makes end-of-month checking much easier.
Second, I would use the running balance as a warning signal rather than treating it as unquestionable truth. If it suddenly looks wrong, I would review recent entries before assuming the bank or the app is at fault. Common causes are a forgotten cash purchase, a duplicated entry, or a payment entered with the wrong sign or amount.
Third, I would reconcile at a regular interval. Comparing the ledger with a bank statement or receipt pile can expose errors while they are still easy to fix. This is more useful than waiting until a major payment is due, because several small mistakes can otherwise hide inside one confusing total.
Finally, I would keep the app’s role deliberately narrow. I would use it to answer questions such as “What should my available balance roughly be after these commitments?” I would not force it to answer questions it was not designed for, such as a detailed analysis of long-term net worth or a complete business tax report.
My performance verdict
Simple Checkbook Ledger makes the most sense when perceived speed means getting a financial entry recorded without a long setup process. Its focused nature should help routine use feel lighter than a large budgeting suite, while its manual design places responsibility for accuracy firmly with me. That is a fair trade if I value control and privacy of process more than automation.
Its stability should be judged through the trustworthiness of my own routine as much as through opening speed. I would verify important entries, reconcile regularly, and protect the record separately from the phone. Those habits are not unnecessary burdens; they are what make a manual ledger dependable.
With an Everyone rating, free entry point, support for devices running operating-system version 11 or later, and a clear checkbook focus, the app is approachable for personal use. Its 100 thousand-plus installs show that this kind of straightforward tool has found an audience, while the middling average rating of 3.4 is a useful reminder that simplicity can feel limiting to users seeking automation.
My honest recommendation is to try it if you want a compact, manual record of personal money movement and are willing to maintain it consistently. I would skip it in favor of a bank-connected budgeting app or dedicated accounting software if automatic imports, advanced reporting, or multi-account management are central to your needs. For the right user, its restraint is the point; for everyone else, that same restraint will be the reason to look elsewhere.
FAQ
What is Simple Checkbook Ledger used for?
Simple Checkbook Ledger is designed to help you record and organize personal financial transactions in a straightforward way. You can use it to track deposits, withdrawals, purchases, bills, and transfers while keeping an ongoing view of your account balance. It is particularly useful for people who prefer manual control over their finances instead of connecting the app directly to a bank account.
Does Simple Checkbook Ledger connect to my bank account automatically?
The app is primarily intended for manual checkbook and transaction management, so users generally enter financial activity themselves rather than relying on automatic bank synchronization. This can be an advantage for privacy and control, but it also means that your balance is only accurate when transactions are recorded correctly and regularly. Always check the app’s current store listing for supported synchronization features.
Is Simple Checkbook Ledger suitable for budgeting and multiple accounts?
Simple Checkbook Ledger can be helpful for basic budgeting because it lets you review spending and maintain a running record of your money. Depending on the version and device, you may be able to create or manage more than one account or ledger. However, it is better suited to simple personal bookkeeping than advanced financial planning, investment tracking, or detailed household budget analysis.
Can I use Simple Checkbook Ledger without an internet connection?
Because transaction entry and ledger management are generally handled locally, Simple Checkbook Ledger may remain useful when you are offline. This is convenient when recording a purchase immediately or checking your balance without mobile data. Nevertheless, features such as backups, synchronization, advertisements, or external sharing may require an internet connection, so offline availability can vary by platform and app version.
Is my financial information safe in Simple Checkbook Ledger?
A manual ledger app can reduce exposure because it does not necessarily require direct access to your bank credentials. Even so, the safety of your information depends on how the app stores data, whether it supports device security or backups, and how your phone is protected. Before entering sensitive details, review the app’s privacy policy, permissions, backup options, and developer information.











