

Rocco - Fast Cash Advance
4.2FinanceUpdated October 5, 2026
Screenshots
Pros
- Quick application process with minimal paperwork
- Clear repayment schedule shown before accepting an advance
- Useful for covering unexpected short-term expenses
- Funds may arrive quickly after approval
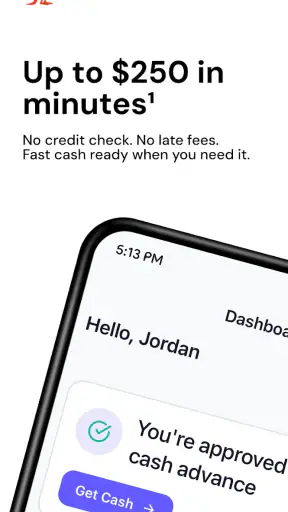
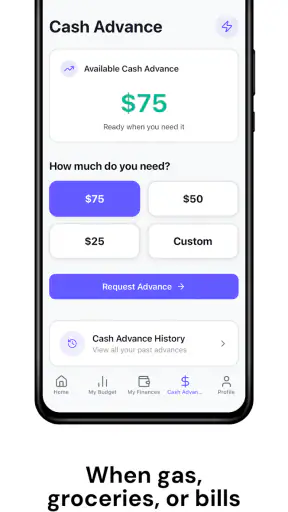
- Simple interface makes account details easy to find
Cons
- Advance availability depends on eligibility and approval checks
- Fees or borrowing costs can make repayment expensive
- Short repayment periods may strain a tight budget
- Late payments could lead to additional charges or collection action
- Not available in every region or to all applicants
 Analysis By Mobexer
I approached Rocco - Fast Cash Advance as a finance app for people who need to think carefully about short-term money, not as a general budgeting tool. Its focus is cash advance and personal finance services, and that narrow purpose matters: the useful question is not simply whether it looks convenient, but whether it fits the way you handle an unexpected gap between income and expenses.
Rocco Finance, Inc. develops the app, which is free to download and intended for everyone. It has reached over 100 thousand installs and holds a 4.2 average from around 4 thousand ratings, with roughly 1.4 thousand written reviews. Those figures suggest that the app has found a real audience, although they should not be confused with a promise that every applicant will receive money or that every user will see the same terms.
My overall impression is that Rocco makes most sense as a tool to investigate a possible cash advance when timing is the main problem. It is less convincing as a permanent replacement for a spending plan, emergency fund, or conventional bank product. That distinction is the key to using it responsibly.
How Rocco fits into a short-term money decision
The app presents itself around two connected needs: accessing a cash advance and handling personal finance services. In practical terms, that puts it closer to an emergency-money option than to a full-featured household finance workspace. I would open it when a bill is due before my next income arrives, then judge the result against the actual cost and repayment pressure rather than treating the available amount as extra income.
That mindset is important because “fast” describes the intended experience, not a guarantee that money will arrive instantly in every situation. Financial applications normally require a user to provide information, meet eligibility conditions, and review the terms shown during the process. I would read each screen carefully before accepting anything, especially where repayment timing, fees, or other obligations are displayed.
The app’s current version is 3.0.0, and it runs on Android 8.0 or later. That makes it accessible to people using older supported Android devices, though the experience can still depend on the phone, operating system behavior, and the information a user can provide. I would keep the app updated and avoid rushing through setup simply because the need for cash feels urgent.
What “free” means in this case
Rocco is free to download, so there is no purchase price required just to install it and explore its starting experience. That is the clearest part of its value proposition. It lets a user investigate the service without paying an upfront app fee, which is useful when someone is already watching every dollar.
However, free access to an app is not the same as free borrowing. The download cost tells me what I pay to get the software, not what a particular cash advance may cost or what conditions may apply. I would never treat the word “free” as evidence that a transaction has no charge. Before confirming an advance, I would look for the complete repayment amount, the due date, any optional or mandatory charges, and what happens if repayment becomes difficult.
This is also why I would not compare Rocco with a paid budgeting app solely on download price. A paid finance app may charge for planning features while leaving borrowing outside its scope; Rocco’s value is tied more directly to the usefulness and affordability of the service presented to an eligible user. The two products solve different problems.
What the app can be worth in a real situation
Imagine my car needs an unexpected repair two days before payday, and postponing the repair would prevent me from getting to work. In that situation, I might use Rocco to examine whether a cash advance is available and whether its repayment fits my next income. The benefit would be timing: solving a short gap without immediately relying on a credit card, overdraft, or a favor from family.
That benefit only counts if I compare the full obligation with the alternatives. If the advance makes the following pay cycle too tight, it has moved the problem rather than solved it. I would write down the amount needed, subtract bills that are already committed, and check whether repayment leaves enough for food, transport, housing, and other essentials. This simple step is more valuable than focusing on the maximum amount the app might display.
A less obvious use is as a screening tool before making a decision elsewhere. Even if I ultimately choose not to accept an advance, going through the available information can clarify how much I actually need and how quickly I could repay it. I would still avoid submitting unnecessary applications or entering sensitive details casually; the point is to make a measured comparison, not to collect offers impulsively.
Where it differs from ordinary alternatives
A traditional bank account is usually better for regular money management, direct deposits, saving, and long-term financial history. A credit card may be more practical for someone who can repay the balance reliably and already understands its interest and fee structure. An overdraft facility may be convenient for a very small timing issue, but it can also create its own charges and repayment pressure.
Rocco’s potential advantage is concentration. Instead of opening a broad banking relationship, I can look specifically at a cash advance and personal finance service. That can feel simpler when the need is immediate. The trade-off is that a focused advance app should not be mistaken for a complete financial system. It will not, by itself, replace the habits that prevent repeated shortfalls.
For a person with access to a genuinely interest-free option from a trusted source, that alternative may be cheaper. For someone who needs ongoing debt consolidation, a bank loan or qualified credit counselor may be more appropriate. Rocco is most relevant when the problem is short-term timing and the user can evaluate the repayment consequences with a clear head.
Practical checks I would make before accepting anything
First, I would identify the exact amount needed instead of borrowing the largest amount offered. A smaller advance is easier to repay and reduces the risk that convenience turns into unnecessary spending. I would also check whether the repayment date matches my actual income date rather than an optimistic assumption.
Second, I would compare the total repayment with at least one realistic alternative. That could be delaying a nonessential purchase, asking a service provider about a payment arrangement, using an existing emergency reserve, or checking a conventional account. The right comparison is the total cost and the effect on my next budget, not just how quickly the money appears.
Third, I would save or record the key terms before confirming. A screenshot or personal note can help me remember the amount, schedule, and conditions I agreed to. This is especially useful with any financial service because a rushed tap can be hard to reconstruct later.
Finally, I would plan the repayment before using the funds. If the only way to repay is another advance, the app is no longer solving an isolated emergency. It is becoming part of a debt cycle, and that is the point at which I would stop and look for a different form of help.
Friction and limitations worth considering
The first limitation is inherent to the category: eligibility and terms are personal. A positive public rating does not mean that every user qualifies, receives the same offer, or has the same repayment experience. I would treat the app as a way to check my own situation, not as a guaranteed source of emergency money.
The second is psychological. A clean, convenient interface can make borrowing feel less serious than it is. The easier the process feels, the more important it becomes to pause at the final review. A cash advance can be useful for a genuine shortfall, but it should not become the default response to routine overspending.
There is also a practical limitation for people seeking broad financial organization. Someone who wants detailed long-term planning, investment research, extensive account analysis, or a complete household ledger may be better served by a dedicated budgeting or banking product. Rocco’s identity is tied to fast cash access and personal finance services, so I would not choose it expecting the depth of a full financial planner.
Another trade-off is that urgency can reduce comparison shopping. If a bill is due today, a user may accept the first workable option without examining alternatives. My advice is to prepare a small emergency checklist in advance: the amount required, the next dependable income date, essential expenses, and the maximum repayment I can handle. That preparation makes Rocco more useful and less risky.
Who is likely to get the most value
I see the strongest fit for an adult who has a temporary cash-flow gap, understands the difference between borrowing and earning, and can repay without sacrificing essential expenses. The app may also suit someone who wants to investigate a cash advance from a phone rather than visit a branch or manage a more traditional credit application.
It is less suitable for someone whose income is already insufficient for recurring bills. In that case, another advance may provide relief today while increasing pressure later. I would also advise caution for anyone who has trouble tracking due dates, tends to borrow for discretionary purchases, or is already juggling several repayment commitments.
People under the Everyone content rating can encounter the app in the store, but that should not be read as financial advice for every age or situation. A young user, someone without independent income, or anyone uncertain about a financial agreement should involve a trusted adult or qualified adviser before accepting an obligation.
For a careful user, the strongest feature is not simply speed. It is the possibility of putting a short-term option in front of me at the moment I need to compare choices. The hidden discipline is that I must bring my own budget to the process. Without that, the app can encourage a decision based on availability rather than affordability.
My verdict after weighing the value
Rocco - Fast Cash Advance earns consideration because it is free to download, focused on cash advances, and available on a wide range of Android devices. Its 4.2 average and established install base make it look like a service many people have tried, but popularity is not a substitute for reading the offer presented to me personally.
I would recommend trying it when the need is genuinely short-term, the requested amount is modest, and repayment is already mapped out. I would not recommend opening it with the assumption that fast access automatically means affordable access. The decisive information is the complete obligation shown before acceptance, together with the effect on the next budget.
If I needed a lasting way to organize spending, I would choose a dedicated budgeting or banking solution instead. If I had a cheaper, clearly understood alternative for the same emergency, I would compare that first. But when timing is the central problem and I can repay responsibly, Rocco can be a practical place to investigate an option.
My final advice is simple: use it as a financial decision tool, not as spare income. Check the terms, borrow only what the emergency requires, record the repayment plan, and walk away if the next pay cycle cannot comfortably support it. Used with that discipline, the free app access has real value; used without it, convenience can become the most expensive part of the experience.
FAQ
What is Rocco - Fast Cash Advance?
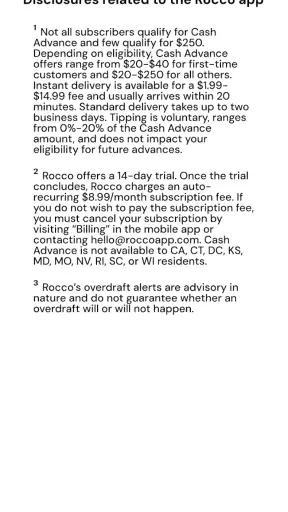
Rocco - Fast Cash Advance is a financial app designed to help eligible users request short-term cash advances through a mobile device. After creating an account and providing the requested personal and financial information, the app may show available options, fees, repayment details, and estimated delivery times. It is not a guaranteed loan, and approval depends on eligibility checks and the terms presented to each applicant.
How does the Rocco cash advance application process work?
After downloading Rocco, you generally need to register, verify your identity, connect or provide information about a qualifying bank account, and complete the application steps shown in the app. Rocco then evaluates the submitted information and may display an advance offer. Before accepting, carefully review the amount, service charges, repayment date, and any optional features because costs and approval conditions can vary by user.
Are there fees or interest charges when using Rocco?
The total cost of using Rocco depends on the advance and services available to your account. The app may present service fees, expedited transfer charges, subscription-related costs, or other expenses rather than a traditional interest rate. Read the final disclosure before confirming an advance, and check whether any recurring membership can be canceled. Never accept an offer until you understand the complete repayment amount.
When will the money arrive, and how is repayment handled?
Delivery speed depends on the selected transfer method, bank processing times, eligibility, and whether an expedited option is available. Standard transfers may take longer than instant delivery. Repayment is typically scheduled for a future date and may be collected from a linked bank account or through another method shown in the app. Keep sufficient funds available and review the repayment schedule to avoid returned-payment fees.
Is Rocco - Fast Cash Advance safe and available to everyone?
Rocco may use account verification and security measures to protect submitted information, but users should still review its privacy policy, permissions, and terms before registering. Availability is usually limited by location, age, banking status, and other eligibility requirements, so downloading the app does not guarantee approval. Only use the official Android or iOS store listing, and avoid sharing login details or verification codes with anyone.











