

Robinhood Banking
4.9FinanceUpdated October 5, 2026
Screenshots
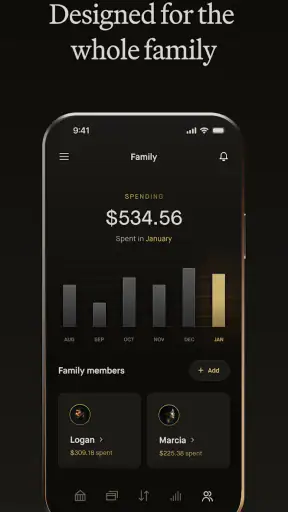
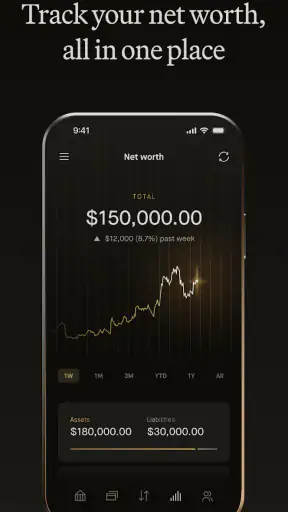
Pros
- Commission-free stock
- ETF
- and options trading is easy for beginners.
- Clean interface makes portfolio tracking and order placement straightforward.
- Supports fractional shares for investing with smaller amounts of money.
- Recurring investments can help users build consistent saving habits.
- Offers access to stocks
- ETFs
- options
- crypto
- and cash-management features.
Cons
- Advanced traders may find the research and charting tools too limited.
- Options and margin trading can expose inexperienced users to significant losses.
- Customer support is primarily online and may not offer phone assistance.
- Crypto availability and features can vary depending on the user's location.
- Account restrictions or verification delays may frustrate some new users.
 Analysis By Mobexer
Robinhood Banking is a finance app from Robinhood that brings its banking experience to a phone. I spent time looking at it as an everyday money tool rather than as a trading shortcut, and that distinction matters. The store summary presents it as “Credit Card & Banking,” while the short description simply calls it “Robinhood Banking,” so I approached it mainly as a way to keep banking tasks close at hand.
My overall impression is that the app is most appealing to people who already like managing money digitally and want fewer separate places to check. It is free to install, rated for Everyone, and its average rating is 4.9 from around 25K ratings, with about 2.3K written reviews. Those figures suggest strong user satisfaction, but they do not remove the need to think carefully about whether its style of banking fits your habits.
Robinhood Banking in everyday use
The central capability: banking from the same financial app
The most important idea here is convenience through consolidation. Instead of treating banking as something completely separate from the rest of your financial life, Robinhood Banking puts that experience inside the Robinhood ecosystem. In practical terms, I found the appeal less about a flashy feature and more about reducing the number of apps I would need to open when checking money, reviewing activity, or making a routine decision.
That can be useful when your financial life is already organized around Robinhood. A single mobile destination feels simpler than moving between a traditional bank app, a separate card app, and another service for financial monitoring. The benefit is especially noticeable for people who check their finances in short moments: while commuting, before paying a bill, or after a purchase they want to verify.
Still, I would not describe this as a universal replacement for every banking arrangement. A banking app needs to be judged by the details of your daily routine, not just by how neatly it fits on a home screen. If you prefer a branch, extensive account types, or a long-established relationship with a conventional bank, the streamlined Robinhood approach may feel narrower.
What the mobile-first design changes
Using a phone as the main place for banking changes the rhythm of money management. You are more likely to glance at your finances often, but those quick checks can also encourage impulsive decisions if you confuse visibility with understanding. I like the immediacy, yet I would still set aside a quiet moment for reviewing transactions rather than relying only on brief notifications or snapshots.
A useful habit is to open the app with a specific question. For example, I might check whether a recent payment has appeared, review spending from the last few days, or confirm that my available balance matches what I expect. This makes the mobile format work as a practical tool instead of turning it into a stream of disconnected account checks.
The app is available for devices running Android 7.0 or later, which gives it a broad compatibility range for Android users. Its current version is 2.18.7, and the release date shown for this version of the app is March 19, 2024. I would still keep the application updated, especially for a finance product where reliability and security maintenance matter more than having the newest visual design.
How I would use it in practice
My preferred workflow would begin with a quick balance check, followed by a review of recent activity. I would then compare what I see with my own budget or notes before moving money or making another purchase. That extra pause is important because an account screen tells you what has been recorded, while a budget tells you what you can comfortably afford.
For a household, I would use the app as a personal control panel rather than assuming it replaces every shared financial process. One person could check routine activity on a phone, while larger planning decisions remain in a spreadsheet or another budgeting method. That division keeps the convenience of mobile banking without asking one app to become the entire financial system.
Another practical tip is to separate “checking” from “acting.” Open the account to understand what happened first. Only after confirming the transaction, balance, and purpose should you decide whether to spend, transfer, or wait. This small workflow reduces the chance that a fast mobile interface will push you into a rushed choice.
A realistic everyday scenario
Imagine that I am leaving work and receive a message that a regular payment should have gone through. I open Robinhood Banking, look at the recent activity, and compare the result with the amount I expected. If the record is present, I can close the app with confidence. If something looks unfamiliar, I have caught it early enough to investigate instead of discovering the issue during a later monthly review.
The same process works after a weekend of small purchases. Rather than waiting until the end of the month, I can look at the activity while the transactions are still fresh in my memory. That makes it easier to spot a duplicated charge, an unexpectedly large purchase, or spending that is quietly taking money away from a planned goal.
What I like about this scenario is that it shows the real value of the app: frequent, low-effort awareness. It is not a substitute for financial discipline, but it can make the discipline easier to practice. The phone becomes a convenient checkpoint between earning money and spending it.
Where the convenience has limits
The same simplicity that makes the app approachable can become a limitation for users who want a very detailed banking workspace. People with complicated finances may need more specialized tools for budgeting, tax preparation, joint money management, or long-term planning. I would not choose Robinhood Banking as my only financial tool without first checking whether its workflow covers those needs comfortably.
There is also a psychological trade-off. When banking and other money-related activity live close together, it may be tempting to act more often than necessary. I prefer to use the app for observation and routine administration, then make larger decisions only after considering my broader financial plan. That is particularly important for anyone who tends to react emotionally to balances or market-related information.
Compared with a traditional bank app, Robinhood Banking feels more attractive to someone who values a modern, centralized mobile experience. A conventional bank may be the better choice for a person who depends on in-person service, a wide range of established banking products, or a familiar branch network. Compared with a standalone budgeting app, Robinhood Banking is more directly connected to banking activity, while a budgeting tool may offer a more deliberate planning environment. These are different strengths, not simple wins and losses.
Who gains the most from it
I think the strongest match is a mobile-first user who already feels comfortable with Robinhood and wants banking to sit naturally within that environment. The app is also a good fit for someone who checks transactions frequently and prefers a clear, quick routine over a feature-heavy desktop experience.
It may suit a younger adult building independent money habits, provided that person understands the difference between viewing an account and managing a complete budget. The Everyone age rating makes it broadly approachable from a content perspective, but financial responsibility still depends on the user’s situation and decisions.
I would be more cautious about recommending it as the sole option to someone with complex household finances, a strong need for branch access, or a preference for highly specialized budgeting controls. In those cases, a traditional bank or a dedicated planning tool may be a better foundation, with Robinhood Banking used only if it adds a clear convenience.
Small habits that make the app more useful
First, I would choose a regular review time rather than opening the app randomly throughout the day. A short check after a typical spending period gives the activity context and makes unusual entries easier to recognize. Second, I would keep a separate note of recurring commitments so that the app’s account view is supported by a personal plan.
Third, I would investigate unfamiliar activity immediately instead of waiting for several transactions to accumulate. Mobile access is valuable because it shortens the time between noticing something and responding to it. Finally, I would avoid judging financial progress from a single balance. A balance is a moment; progress comes from comparing it with upcoming obligations, saving intentions, and actual spending behavior.
These habits are not flashy features, but they are where I see the app producing its most meaningful effect. The real advantage is the lower friction between a question and an answer. When checking money takes very little effort, I am more likely to check it before making a decision rather than after a problem appears.
What to expect from the developer and the app’s position
Robinhood is the developer, and the app has attracted more than 100K installs. That level of adoption gives it a visible place among mobile finance tools, while the strong average rating indicates that many users enjoy the experience. I would treat those signals as encouragement to try the interface, not as a reason to skip personal evaluation.
The free price also lowers the barrier to testing the app. I can explore whether its banking workflow feels natural without paying simply to install it. Even so, “free” should not be confused with “automatically right for me.” The important question is whether the app helps me manage money more clearly than the alternatives already on my phone.
My final view
Robinhood Banking works best as a convenient mobile banking hub, not as a promise to solve every financial problem. I like its focus on quick access and the possibility of keeping everyday banking closer to the rest of a Robinhood-centered financial routine. The strongest use case is frequent checking: confirming activity, staying aware of spending, and catching questions while they are still easy to investigate.
Its trade-off is that convenience can make the experience feel lighter than the needs of a complex financial life. I would pair it with a real budget, careful decision-making, and another service when branch support or deeper planning matters more than mobile simplicity.
For someone who wants a free, phone-based banking experience and already prefers Robinhood’s ecosystem, I think it is worth trying. For someone seeking a complete replacement for a traditional bank and a dedicated budgeting system, I would compare those options first. My recommendation is positive, but specific: use it when fast, regular financial visibility is the capability you value most.
FAQ
What is Robinhood Banking, and what services does it offer?
Robinhood Banking is the financial services section connected to the Robinhood investing platform. Depending on your eligibility and location, it may provide features such as a spending account, debit card, direct deposit, bill payments, cash management tools, and access to uninvested cash programs. Availability can vary, so review the current terms and supported features in the app before signing up.
Is Robinhood Banking a real bank, and is my money insured?
Robinhood is primarily a financial technology company and brokerage platform, while certain banking services are provided through partner banks or other regulated financial institutions. Eligible deposits may receive FDIC insurance when placed with participating banks, subject to applicable limits and requirements. Brokerage assets have different protections, so users should read the account agreements carefully rather than assuming every balance has identical coverage.
Are there fees for using Robinhood Banking?
Robinhood Banking may advertise no monthly maintenance fees for certain services, but that does not mean every possible charge is eliminated. Depending on how you use the account, fees could apply to out-of-network ATM withdrawals, expedited transfers, replacement cards, or other optional services. Before downloading or transferring money, check the latest fee schedule and account disclosures in your region.
Can I use Robinhood Banking for direct deposit, bills, and everyday spending?
Eligible users may be able to set up direct deposit, receive paychecks or government payments, pay bills, transfer funds, and spend with a Robinhood debit card. The exact capabilities depend on account approval, verification, location, and current product availability. It is wise to confirm deposit timing, transfer limits, ATM access, and payment support before making it your primary everyday account.
What should I know about eligibility, security, and customer support?
Opening a Robinhood Banking account generally requires identity verification and may involve age, residency, and regulatory eligibility requirements. The app typically includes security tools such as passcodes, device verification, and account alerts, but users should still enable strong protection and monitor activity. Support is mainly provided through in-app or online channels, so response times may vary when urgent help is needed.











