

ReelMoney: Watch & Earn Cash
4.8FinanceUpdated October 5, 2026
Screenshots
Pros
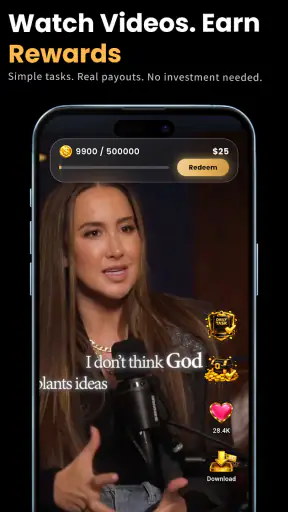
- Simple video-based earning system with no upfront payment required.
- Short clips make it easy to use during brief free moments.
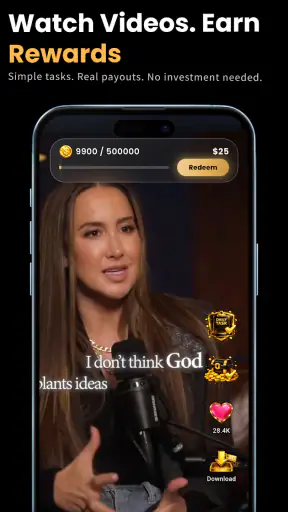
- Reward progress is clearly displayed inside the app.
- Lightweight interface is generally easy for beginners to navigate.
- May offer extra earning opportunities through bonuses and referrals.
Cons
- Earnings per video can be very small and require considerable time.
- Cash-out eligibility may depend on minimum balance requirements.
- Reward availability and withdrawal options can vary by location.
- Frequent ads may interrupt viewing and reduce the overall experience.
- Referral-focused promotions may not appeal to users seeking passive rewards.
 Analysis By Mobexer
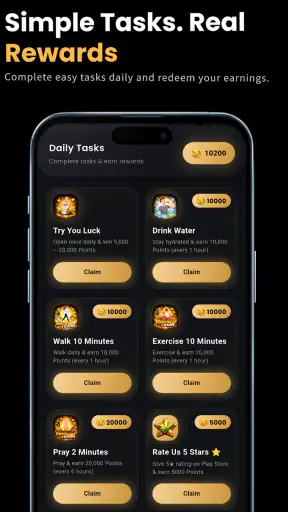
I approached ReelMoney as a small experiment in turning spare minutes into something useful. It is a free finance app from Debug Entity Dev built around short videos, simple tasks, points, and reward redemptions. That idea is easy to understand, and the first sessions feel pleasantly low-pressure: open the app, choose an available activity, finish it, and see your balance move. The more important question, though, is whether that routine remains worthwhile after the novelty wears off.
My overall impression is cautiously positive. ReelMoney is best viewed as a light rewards companion rather than a serious income source. It may suit someone who already spends a few idle minutes scrolling and would rather attach a small incentive to that habit. It is much less suitable for anyone expecting dependable earnings, meaningful financial growth, or a replacement for a budgeting, banking, or investing tool.
What using ReelMoney feels like beyond the first session
The first-week appeal is immediate, but deliberately modest
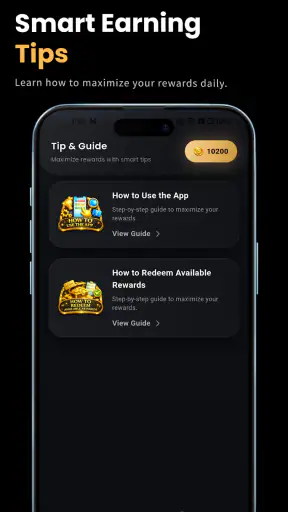
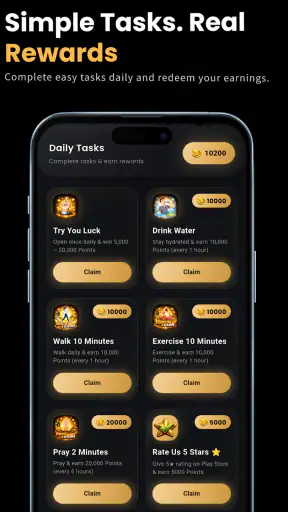
The strongest part of the experience is how quickly the purpose becomes clear. There is no need to learn a complicated finance system or build a detailed profile before understanding the basic loop. Short videos and tasks create a sequence of small actions, while points provide visible progress toward rewards. That makes the app approachable for people who dislike dense financial dashboards.
I also like the psychological simplicity of the format. A normal finance app asks me to make decisions about spending, saving, or planning. ReelMoney asks for attention instead. That difference matters. If I am waiting for a bus, taking a break, or winding down before bed, a short activity feels easier to start than a full budgeting session.
The first week is where the app has its clearest advantage. New users are naturally curious about the available tasks, the pace of point accumulation, and the redemption process. I found that the reward loop gives otherwise empty moments a little structure. It is not exciting in the way a game is exciting, but it can be satisfying when progress is easy to see.
That initial appeal should not be confused with high earning potential. The app’s store message focuses on watching and completing activities for points, not on guaranteed income. I would set expectations accordingly: think of it as a small bonus attached to spare time, not a job. Anyone opening it with that distinction in mind is less likely to feel disappointed later.
Who is likely to enjoy the routine
ReelMoney makes the most sense for people who enjoy short, repeatable tasks and are comfortable waiting for rewards to build gradually. It can also appeal to users who want a very simple introduction to reward-based finance apps without committing to a subscription. Since the app is free, trying the basic routine does not require an upfront purchase.
A realistic everyday scenario would be a commuter with ten minutes before a train arrives. Instead of opening a social feed and losing track of time, that person could complete a few available activities, check the points balance, and close the app. The value comes from giving those minutes a defined purpose. The same approach could work during a lunch break, although I would avoid treating every spare moment as an obligation to earn.
Parents and younger users should still apply ordinary judgment even though the content rating is Everyone. An age label makes an app broadly accessible, but it does not turn reward activities into a financial education tool. I would explain to a child that points are not the same as cash and that no reward app should encourage sharing sensitive information casually.
What the numbers suggest about its place in the market
ReelMoney has reached over one hundred thousand installs and carries a 4.8 average from roughly fourteen thousand ratings, with about two and a half thousand written reviews. Those figures suggest that the concept is connecting with a substantial group of users, and the written feedback volume gives prospective users more context than a nearly empty listing would.
Still, popularity does not answer the practical questions that matter most: how consistently useful the tasks feel, how easy redemptions are in a person’s situation, and whether the routine remains worth the attention. A high average rating can reflect a pleasant first impression, while long-term value depends on repeated use. I would treat the reception as encouraging, not as proof that it will fit every user.
Where it differs from ordinary finance apps
Compared with a budgeting app, ReelMoney is almost the opposite in purpose. A budgeting tool helps me understand money I already have and make better decisions with it. ReelMoney focuses on completing activities in exchange for points. It is therefore complementary at best, not a substitute. Using it will not automatically improve spending habits, reveal recurring expenses, or create a savings plan.
It also differs from cashback services. Cashback usually connects a reward to a purchase I was already planning to make. ReelMoney connects progress to attention and task completion. That distinction creates a useful trade-off: I do not need to shop to participate, but I am spending time rather than simply receiving a benefit from an existing transaction.
Against survey or gig platforms, the attraction is the shorter, lighter format. The drawback is that small activities can feel repetitive, and the value of each minute may be harder to judge. If I wanted a more predictable return for a longer block of time, I would look at a platform with clearly defined paid assignments instead. If I wanted financial control, I would choose a budgeting app. ReelMoney occupies the narrow space between entertainment and rewards.
The redemption mindset matters more than the point counter
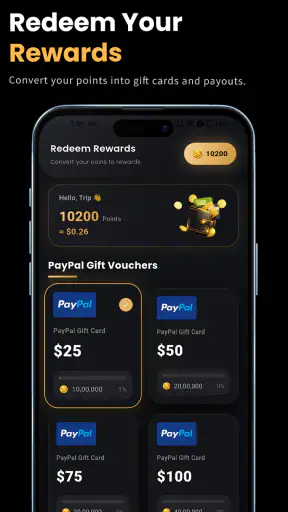
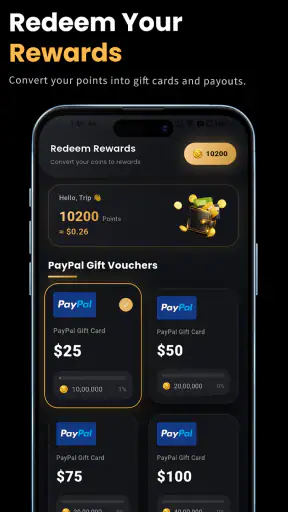
One of the most useful habits is to think about redemption before spending too much time inside the app. I would first inspect how the reward process is presented, what options are available to me, and how much progress is required. This prevents a common mistake: accumulating points enthusiastically without knowing whether the eventual reward suits my needs.
I would also keep a simple personal rule: only use ReelMoney during time I would otherwise waste. That rule protects the app from quietly replacing more valuable activities. If I begin interrupting work, study, sleep, or conversations to chase points, the exchange is no longer attractive. The app works best when it fills leftover time, not when it creates a new demand for attention.
Month-to-month value depends on variety
After the first month, the central issue is repetition. Watching short videos and completing tasks can be pleasant when activities feel fresh, but the same loop becomes mechanical if every session feels identical. ReelMoney’s lasting appeal therefore depends less on its basic concept than on whether the available activities continue to justify opening it.
This is where I would be more selective. I would not force myself to check the app every day simply because daily use is possible. Instead, I would open it when I have genuine spare time and compare the effort with the progress offered. A flexible schedule is healthier than turning a small reward into a chore.
The store positioning emphasizes daily redemption, which gives the app a clear recurring-use angle. In practice, daily availability is useful only if the activities remain convenient and the reward path feels understandable. A daily routine can be sustainable when it takes a few spare moments; it becomes tiring when I feel compelled to monitor it repeatedly throughout the day.
My practical test would be simple: after several weeks, can I describe a reason to open ReelMoney that is more specific than “I should check for points”? Perhaps there is a convenient idle-time window, a reward goal I actually want, or a task format I find less tedious than scrolling elsewhere. If the answer is no, the app may have already delivered its short-term value.
Three ways to use it more intelligently
Set a time boundary before starting. I would decide in advance whether I have five or ten spare minutes, then stop when that window ends. This avoids letting a reward loop expand into unplanned screen time.
Separate points from personal income. I would track the app as a small rewards activity, never as part of rent, bill, or savings calculations. That mental separation keeps expectations realistic and prevents the balance from influencing important financial decisions.
Review the reward path periodically. Rather than checking only the growing number of points, I would confirm that the available redemption choices still match what I want. A balance is useful only when it can be exchanged in a way that feels worthwhile.
These habits may sound basic, but they address the main weakness of this category: users can spend more attention than the reward justifies. ReelMoney is most effective when the user controls the routine instead of letting the routine control the user.
The maintenance burden is low, but not zero
ReelMoney is easy to maintain compared with a full personal finance system. There is no complicated budget to update, no portfolio to rebalance, and no recurring payment to remember. The main maintenance task is behavioral: deciding when to use it, checking progress sensibly, and avoiding unnecessary sessions.
The app is currently at version 1.0.0, so I would approach it as an early product rather than a finished financial ecosystem. That does not make it unusable, but it does make patience important. Early versions can feel straightforward because they have a narrow focus, while later changes may alter the balance between convenience and repetition. I would keep the app updated through normal platform channels and pay attention to how the experience develops over time.
There is also a small organizational burden around reward expectations. I would avoid treating every point notification as urgent and would not build a daily schedule around it. A reward app should be easy to leave alone for a while. If missing a day creates anxiety, the product has stopped being a casual tool and started behaving like an obligation.
Because it belongs to the finance category, I would use the same privacy discipline I apply to any money-related app. I would read prompts carefully, avoid entering information that is not necessary for the action I am taking, and never assume that a reward is worth compromising personal security. The Everyone rating is reassuring about broad accessibility, but it should not replace sensible caution.
Where fatigue begins
The first source of fatigue is the task loop itself. Short activities are convenient, but convenience does not guarantee variety. Once the curiosity of a new app disappears, I may notice that I am repeating the same gestures for a reward that feels increasingly distant. This is normal for the category, yet it is still the main threat to long-term use.
The second source is opportunity cost. Five spare minutes can be harmless, but repeated sessions add up. I might have used that time to answer an important message, prepare for tomorrow, stretch, or simply rest without another screen. ReelMoney needs to compete not only with other reward apps but also with doing nothing, which is often the better choice.
The third is uncertainty around perceived value. A point balance looks concrete, but points are not useful until I understand what they can become. If progress feels slow or the reward target feels remote, the app’s motivational design loses force. That is why I recommend judging the experience by completed redemption goals rather than by the size of the balance alone.
There is also a risk of confusing activity with productivity. Because ReelMoney sits in Finance, it can appear more financially meaningful than a normal entertainment app. In my view, the category should not change the basic calculation: I am exchanging attention for a small reward. That can be fine, but it is not the same as learning to manage money or increasing reliable income.
Who should skip it
I would skip ReelMoney if I need predictable earnings, transparent hourly compensation, or a tool for managing bills and savings. It is also a poor match for people who already struggle with compulsive scrolling. Adding points to a feed-like activity may make it harder, not easier, to stop.
Users with very limited data, battery, or screen time should also compare the benefit with the cost of watching videos and completing tasks. Even without a monetary subscription, free does not mean costless: attention, connectivity, and time all count. If those resources are scarce, a direct financial tool or an offline activity may be more useful.
I would also avoid relying on it for a specific financial deadline. A reward app can be a pleasant extra, but it is not a dependable plan for an upcoming payment. Anyone who needs a guaranteed result should choose work, saving, or financial assistance options with clearer terms instead of building a plan around points.
Who should give it a fair trial
ReelMoney deserves a fair trial from users who enjoy structured micro-activities, want a free way to use idle minutes, and can keep rewards in perspective. Its broad age rating and simple premise make the entry barrier low, while the strong user reception indicates that the concept has found an audience.
My recommended trial would be controlled rather than enthusiastic. Use it during one or two naturally empty parts of the day, inspect the reward route early, and note whether the activities remain comfortable after the novelty fades. If the routine fits without displacing anything important, it can earn a small place on the phone. If it feels like another feed demanding attention, uninstalling it is a sensible outcome.
Long-term verdict: a small habit, not a financial strategy
After looking at the first-week appeal, the month-to-month routine, and the maintenance involved, I see ReelMoney as a narrowly useful app. Its strength is accessibility: the concept is easy to grasp, the price is free, and the combination of short videos, tasks, points, and rewards can make idle time feel slightly more purposeful.
Its weakness is equally clear. The long-term value depends on whether the reward remains worth the attention required. No points system can remove the possibility of repetition, and no daily routine is automatically beneficial just because it is easy to start. The app needs a disciplined user who knows when to participate and when to close it.
Debug Entity Dev has kept the product focused enough to make that judgment straightforward. I would recommend it to a friend with one qualification: treat it as a casual rewards app, not as a source of dependable income and not as a replacement for real financial planning. Its lasting value comes from controlled use, realistic expectations, and rewards that genuinely fit your goals.
For me, that is enough to justify keeping it available for occasional idle moments, but not enough to give it a permanent daily appointment. If the activities stay convenient and the redemption experience continues to feel worthwhile, it can remain a pleasant extra. If the routine becomes repetitive or starts consuming intentional time, the novelty has finished its job, and another finance tool—or no app at all—will be the better choice.
FAQ
What is ReelMoney: Watch & Earn Cash, and how does it work?
ReelMoney: Watch & Earn Cash is an entertainment and rewards app that lets users watch short videos, explore content, and complete selected in-app activities in exchange for points or virtual earnings. After reaching the required threshold, users may be able to request a payout through the methods supported in their region. The available tasks, rewards, and redemption rules can change over time.
Can I really earn cash with ReelMoney, and how much can I expect?
ReelMoney may provide small rewards for watching videos and completing offers, but it should not be considered a reliable source of income. Earnings generally depend on how many activities are available, your location, the time you spend in the app, and whether you meet each promotion’s conditions. Before investing significant time, review the current reward rates, limitations, and withdrawal requirements shown inside the application.
What are the withdrawal requirements and payment options?
Withdrawal rules can vary according to your country, account status, and the payment providers available when you use the app. ReelMoney may require users to reach a minimum balance, verify an account, or complete additional steps before submitting a cash-out request. Processing times are not always immediate, and rewards may be rejected if activity violates the terms. Always check the latest payout information in the app.
Is ReelMoney: Watch & Earn Cash safe to use?
The app should be downloaded only from an official Google Play or Apple App Store listing, and users should review its permissions, privacy policy, and developer information before registering. Avoid sharing unnecessary sensitive details, payment passwords, or identity documents through unofficial channels. Because the app may include advertisements, third-party offers, and tracking technologies, privacy-conscious users should carefully manage permissions and read the terms before using it.
What should I know about ads, offers, and account restrictions?
Watching advertisements and completing promotional offers is usually central to the ReelMoney experience, so frequent ads, redirects, and eligibility conditions may be part of normal use. Some offers are available only in certain countries or require actions outside the app. Using multiple accounts, automated tools, VPNs, or misleading information can lead to lost rewards or account suspension. Follow the app’s rules and keep evidence of completed offers if support is needed.











