

Rate: Home, Finance & Wellness
4.5FinanceUpdated October 5, 2026
Screenshots
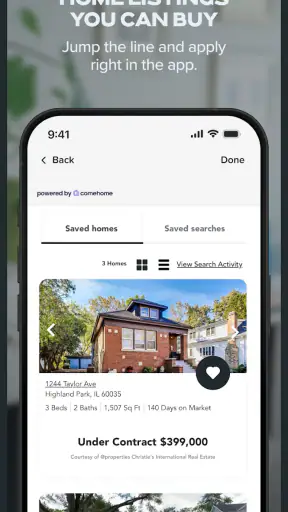
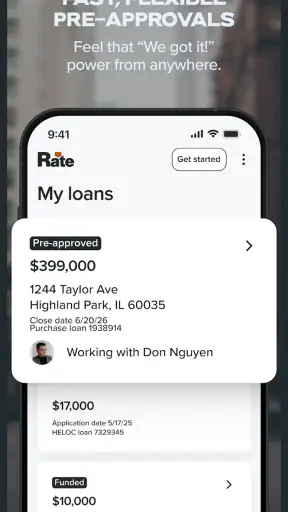
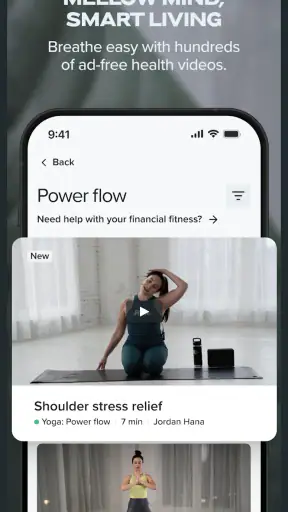
Pros
- Combines home tracking
- budgeting
- and wellness tools in one app.
- Simple interface makes daily check-ins quick and easy.
- Helpful reminders can support consistent routines and financial habits.
- Useful summaries help identify patterns in spending and wellbeing.
- Suitable for users seeking an all-in-one personal organization app.
Cons
- Some features may require a subscription or in-app purchases.
- Combining several categories can make the app feel less specialized.
- Wellness insights should not replace professional medical advice.
- Financial tools may lack advanced budgeting and investment features.
- Regular manual updates may be needed for accurate tracking.
 Analysis By Mobexer
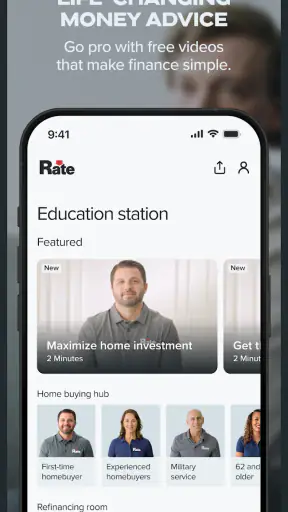
Rate: Home, Finance & Wellness is the kind of finance app that makes a strong first impression because it brings several everyday money tasks into one place. I found the idea appealing immediately: instead of treating a mortgage, refinancing, an auto loan, home equity, a personal loan, travel, and wellness as completely separate concerns, the app presents them as parts of a broader household-planning routine. That range gives it a more practical feel than a single-purpose calculator or a lender-only dashboard.
At the same time, an app like this earns a permanent place on a phone only if it remains useful after the first browsing session. Financial tools can feel exciting when I am comparing borrowing options, but less interesting once the immediate decision has passed. My experience with Rate is that its lasting value depends on whether I use it as a starting point for organized financial thinking rather than expecting it to replace every specialist tool or every conversation with a lender.
It is a free finance app from Guaranteed Rate, Inc, with an Everyone age rating. The current version is 1.52-prod, and it runs on Android 7.0 or later. Its average score is 4.5 from around 1.9 thousand ratings, while its reach has passed 500 thousand installs. Those figures suggest that it has attracted a meaningful audience, but I would still judge it by the quality of its fit for a particular financial task rather than by popularity alone.
What Rate feels like during the first week
The first-week appeal comes from the breadth of the app. I can open it with a broad question in mind—“Could I afford a different home?” or “Would a personal loan make sense for this expense?”—without first deciding which narrow calculator to download. That lowers the barrier to exploration. For someone who is at the early stage of planning, the app is more approachable than opening several lender websites and trying to remember which figures belong to which scenario.
The mortgage and refinancing focus gives the app a clear center of gravity. These are decisions where people often need to compare a current situation with a possible future one, and having related borrowing categories nearby can help me think beyond a single monthly payment. A lower payment is not automatically a better deal, for example, if it comes with a longer repayment period or changes the total cost. Rate is most useful when I treat its information as a prompt to ask better questions, not as an instant answer.
The inclusion of auto, home equity, and personal loans broadens the situations in which I might return. A home repair, vehicle purchase, or unexpected expense can lead to very different borrowing choices. Seeing those choices in one finance environment encourages a useful pause: is this a mortgage-related decision, a secured borrowing decision, or something that should be handled without new debt? That comparison is a more valuable habit than simply searching for the first available rate.
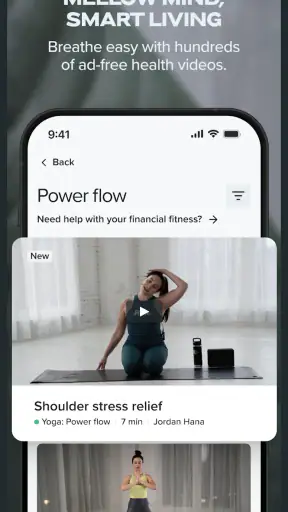
Travel and wellness make the app feel less narrowly transactional. I would not install it solely for those themes, but their presence changes the way I think about the product. Money decisions are connected to plans, health, and lifestyle, so a broader home screen can help users remember that a loan is only one part of a budget. The trade-off is that users who want a focused mortgage workspace may find the wider scope distracting.
One useful first-week workflow is to use the app before speaking with a lender. I would write down the goal, the amount I think I need, the payment I could comfortably handle, and the questions I do not yet understand. Then I would use the app to organize my thinking. This prevents a common mistake: entering a conversation focused only on the headline rate while overlooking repayment length, fees, equity, or what happens if circumstances change.
The best early use is comparison, not commitment. Rate can help me frame a decision, but a finance app should not encourage me to treat an initial estimate as a final offer. Numbers related to borrowing depend on personal circumstances and the details of the product. I would always read the terms carefully and confirm the current conditions before acting.
Useful for several real-life starting points
Imagine I am considering a kitchen repair while also planning a holiday. Opening a personal-loan section, a home-equity section, and a travel-oriented area in the same app could help me separate a necessary expense from an optional one. I might decide that postponing the trip is safer than borrowing for both goals, or I might discover that the repair deserves a different funding approach. The value is not that the app makes the decision for me; it is that it gives the decision a place to begin.
For a first-time home buyer, the mortgage material may be the main attraction. For an existing homeowner, refinancing and home equity may be more relevant. For someone changing vehicles, the auto-loan area may make the app worth keeping temporarily. This flexibility is a genuine strength, but it also means that the experience will feel more valuable to people whose financial lives are changing than to users who want a static account-balance tracker.
What remains valuable from month to month
After the novelty fades, Rate needs a recurring reason to be opened. I do not see its strongest long-term role as daily expense tracking. Instead, I would return when a major financial question changes: a move, a home project, a vehicle decision, a refinancing review, or a personal loan that needs careful comparison. That makes it a periodic planning companion rather than an app I would necessarily check every morning.
This distinction matters because many finance apps promise an ongoing habit but are really useful only during a decision window. Rate can still earn space on my phone if I use it as a checkpoint. Every few months, I could revisit whether my plans have changed, whether a borrowing goal is still necessary, and whether I understand the consequences of pursuing it. The habit is light, but it is more realistic than pretending every user will constantly monitor loan information.
Its broad subject range also creates a useful annual-planning routine. I could review housing goals, transportation needs, travel plans, and wellness spending together instead of treating each as an isolated impulse. That encourages a more honest question: which goals compete for the same money? A mortgage decision can affect travel; a vehicle payment can affect wellness spending; a home project can alter the need for personal borrowing. The app’s value increases when I use those categories to see trade-offs.
For homeowners, the home-equity area may be especially relevant during a renovation or when evaluating a large expense. Yet I would not assume that available equity equals affordable borrowing. The home is tied to the decision, so the risk is more serious than with an ordinary purchase. Rate is helpful as a place to investigate the concept, but I would use a separate budget and carefully consider whether the project improves my situation enough to justify the obligation.
Refinancing is another area where recurring review can be useful, but it is also where oversimplification can cause trouble. A payment that looks smaller may reflect a different term, a changed balance, or costs that are not obvious at first glance. I would compare the full repayment picture and my expected time in the home, not just the first number that catches my eye. This is one of the app’s most important practical lessons: convenience should lead to verification.
The app’s free price makes occasional use easier to justify. I do not need to decide that it will become a permanent financial command center before trying it. I can keep it available for the moments when a borrowing or planning question appears, then remove it if my needs are better served elsewhere. That low commitment suits the app’s periodic nature.
Where other tools may be better
If my main need is detailed budgeting, a dedicated budgeting app may be stronger because it is built around transactions, categories, recurring bills, and spending history. If I need to manage an existing bank account, my bank’s own application may provide more direct account information. If I am comparing many lenders in a highly structured way, a specialist marketplace or a spreadsheet may make side-by-side analysis easier.
Rate’s advantage is the combination of borrowing topics and broader lifestyle context. Its weakness is the same thing: it is not designed around one narrow workflow. Someone who wants a precise amortization model, a complete net-worth dashboard, or intensive expense automation may find it too general. I would keep it alongside a specialist tool only if its broader perspective actually changes my decisions.
Maintenance, friction, and the reasons interest can fade
The maintenance burden is relatively low if I use Rate as a planning reference. I do not need to turn it into a daily ritual, and that is a positive. A finance app that demands constant attention can create anxiety or become another source of notifications and unfinished tasks. Rate makes more sense as something I revisit when a real financial choice is approaching.
Still, low maintenance does not mean no maintenance. Borrowing information can become outdated as personal circumstances, market conditions, and product terms change. I would avoid saving an old estimate in my head and treating it as current. When I return to the app after a long gap, I would start the comparison again rather than relying on what I remember from the previous session.
One practical way to reduce confusion is to keep a short note outside the app with the purpose of each scenario. I might label one “home repair,” another “vehicle replacement,” and another “future move,” then record the assumptions I used. This prevents different goals from blending together and helps me notice when I am comparing unlike situations. It is an advanced but simple workflow, and it makes a broad app much more useful.
Another helpful habit is to separate exploration from application. During exploration, I can consider several loan categories and think through affordability. During application, I should slow down, read every condition, and confirm what is being offered. Mixing those stages can create false confidence, especially when an attractive figure appears before the full details are understood.
The main source of fatigue is probably the gap between curiosity and action. The app can make financial topics feel accessible, but accessibility does not eliminate the work involved in gathering documents, checking budgets, comparing terms, and making a responsible decision. If I open it repeatedly without a concrete question, the broad selection may start to feel like browsing rather than progress.
There is also a mental-load issue. Mortgages, refinancing, home equity, auto loans, personal loans, travel, and wellness are all meaningful subjects, but they do not belong in the same decision for every user. A person dealing with one urgent task may prefer a focused interface. I would be more patient with the wider design during planning, but less enthusiastic if I wanted a clean, single-purpose tool.
Users should also be realistic about the app’s role. It is not a substitute for professional financial advice, a complete household budget, or careful reading of loan documents. That is not a failure unique to Rate; it is a boundary that matters for every consumer finance tool. The app is strongest when it helps me prepare, compare, and identify questions before I make a commitment.
Who should keep it installed
I would recommend keeping it installed if I were actively considering a home purchase, refinancing, a home project, a vehicle, or a personal loan. It is also a sensible temporary companion for someone trying to connect financial goals with travel and wellness plans. The broad range can help users who are in a transition and need to examine several choices at once.
I would be less likely to recommend it as a permanent daily app to someone whose priority is expense tracking, investment management, bill reminders, or direct banking. Those users may get more value from tools designed specifically for those tasks. I would also suggest skipping it if the wider lifestyle sections make it harder to concentrate on a single urgent financial decision.
Before installing, I would ask one simple question: do I have a financial decision to explore, or am I merely collecting another finance app? If there is a real question, Rate has a clear purpose. If there is no question, its broad catalog may not create a lasting habit by itself.
My long-term verdict on Rate
After the first-week curiosity disappears, Rate remains worthwhile as an occasional planning tool rather than an all-purpose financial headquarters. Its lasting appeal comes from bringing major borrowing categories together and placing them near travel and wellness considerations. That combination can improve the quality of my questions and make competing goals easier to see.
I appreciate that it is free, broadly accessible, and available for older Android devices beginning with Android 7.0. The Everyone rating also makes it approachable for a wide audience, although financial decisions still require adult judgment and careful reading. Guaranteed Rate, Inc has created an app that is easiest to appreciate when I use it deliberately, with a specific scenario in mind.
My biggest reservation is that breadth can become distraction. Rate will not replace a detailed budget, a bank app, a specialist loan calculator, or professional advice. It may also lose relevance between major financial decisions. Those are important limitations, but they do not cancel its usefulness; they define the right place for it.
My recommendation is to treat Rate as a financial decision companion, not a financial autopilot. Use it to compare directions, prepare questions, connect borrowing with wider goals, and revisit important plans over time. If that matches what I need, it earns a place on my phone beyond the initial novelty. If I need intensive day-to-day money management, I would choose a more specialized alternative and use Rate only when a major borrowing question comes up.
FAQ
What is Rate: Home, Finance & Wellness?
Rate: Home, Finance & Wellness is designed as a personal organization and lifestyle app that brings home-related planning, financial awareness, and wellness habits into one place. It may help users monitor important routines, review personal goals, and keep practical information organized. Before downloading, check the current store description because available tools, supported regions, and the exact balance between home, finance, and wellness features can change with updates.
Is Rate: Home, Finance & Wellness free to download and use?
The app may be available as a free download, but some features could require a subscription, one-time purchase, or in-app payment. Users should review the pricing information shown on the Google Play Store or Apple App Store before creating an account. Also check whether a free trial automatically converts into a paid plan, how cancellation works, and whether any premium features are necessary for the type of planning or tracking you want to do.
Does the app protect my financial and personal information?
Because an app covering finance, home details, and wellness may handle sensitive personal information, privacy should be considered before use. Read the developer’s privacy policy to understand what data is collected, where it is stored, and whether information is shared with analytics or service providers. Avoid entering banking passwords, card PINs, or highly confidential documents unless the app clearly explains its security measures and provides trustworthy protection.
Can I use Rate: Home, Finance & Wellness without an internet connection?
Offline availability depends on the individual feature and the version installed on your device. Some basic notes, checklists, or previously loaded information may remain accessible without an internet connection, while account synchronization, cloud backups, financial updates, and certain wellness services may require mobile data or Wi-Fi. If reliable offline access is important, test the app in airplane mode and confirm how unsynchronized changes are handled.
Is Rate: Home, Finance & Wellness suitable for managing my money or health?
The app may be useful for organizing financial goals, household responsibilities, and wellness routines, but it should not automatically be treated as a replacement for a bank, licensed financial adviser, doctor, or other qualified professional. Use its information for planning and personal tracking rather than making high-risk financial or medical decisions. Before downloading, verify whether the app offers the specific tools, reminders, reports, and regional support you need.











