

Ramp
4.7FinanceUpdated October 2, 2026
Screenshots
Pros
- Simple interface makes navigation quick for new users.
- Useful tools are organized clearly and easy to access.
- Responsive performance on most modern phones.
- Regular updates help improve stability and usability.
- Convenient settings let users personalize the experience.
Cons
- Some advanced features may require a paid plan.
- The app can use noticeable battery during extended sessions.
- Certain functions depend on a stable internet connection.
- Older devices may experience slower loading times.
- Help resources may not fully answer less common questions.
 Analysis By Mobexer
When a small business starts growing, money rarely becomes difficult because of one dramatic problem. The trouble usually comes from scattered receipts, unclear spending requests, late approvals, and several people trying to answer the same question: where did this charge come from? I found Ramp most useful as a way to bring those everyday finance tasks into one mobile workflow rather than treating it as a simple expense notebook.
It is a free finance app from Ramp Business Corporation, aimed at business users rather than people looking for a personal budgeting tool. The app is rated for Everyone, runs on devices using iOS 11 or later, and its current version is 0.160.2. Its public reception is encouraging, with a 4.7 average from around 2.3 thousand ratings and more than 100 thousand installs. Those figures do not tell me whether it will fit every company, but they do suggest that the mobile experience has found an audience beyond early testers.
From a business purchase to a cleaner record
The best way to understand the app is to follow a normal workday. Imagine I am responsible for a small team and someone needs to buy a subscription, replace a piece of equipment, or pay for travel. In the usual alternative, that request may arrive by email or chat, the purchase happens on a company card, and the receipt sits in a camera roll until someone asks for it. A personal finance app can record the amount, but it usually does not understand the approval handoff or the business context behind the charge.
Ramp is built around that business setting. I would begin by opening the app when a transaction or finance task needs attention, then identify what needs to be reviewed instead of searching through unrelated personal spending. That change sounds small, but it matters: the useful unit here is not just “money spent.” It is the complete trail from a business need to a documented outcome.
The practical strength is the handoff between people. A requester, cardholder, manager, and finance person may all look at the same purchase from different angles. A mobile finance tool becomes valuable when it reduces the number of times those people have to ask one another for context. Ramp is more convincing in that role than a basic spreadsheet because the workflow is centered on business spending rather than only on totals and categories.
Starting with the right expectation
I would not install this expecting a traditional personal budget dashboard. If my goal were to track groceries, rent, savings, and household bills, a consumer budgeting app would probably feel more natural and offer a clearer view of personal cash flow. Ramp makes more sense when spending belongs to a company and several people need a shared process for handling it.
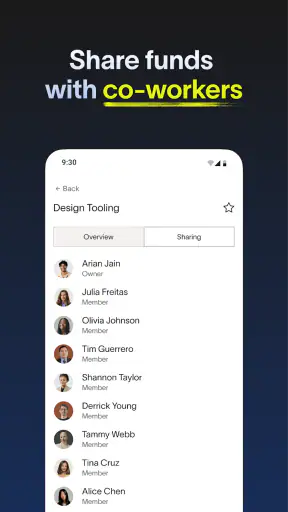
That distinction also affects who should be invited into the workflow. A founder who handles every purchase alone may not gain much from adding another finance tool. A growing team, on the other hand, can benefit when employees submit information from the place where they notice the transaction, while the person responsible for finance receives a more structured item to check.
Step one: capture the business context
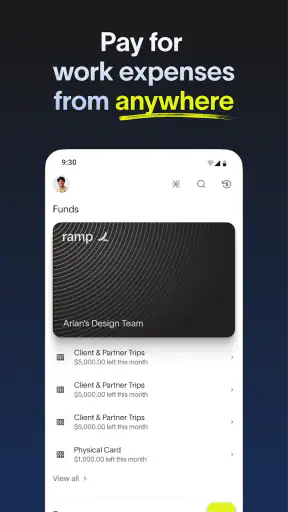
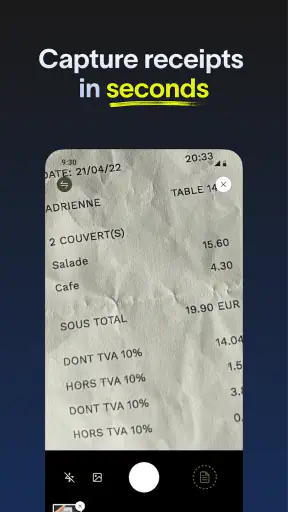
In a realistic scenario, I finish a client visit and need to deal with a business expense while the details are still fresh. The useful habit is to handle it immediately rather than postponing the task until the end of the week. I would open Ramp, locate the relevant spending item, and add the context that explains why the charge belongs to the company.
This is one of the less obvious advantages of a mobile-first workflow. The phone is already with me at the moment the receipt exists, so the app can become the first stop instead of the final cleanup station. That does not eliminate admin work, but it moves the work closer to the source. In my experience, that is often more effective than giving finance staff another spreadsheet to reconcile later.
A useful routine is to treat every charge as a small handoff: what was purchased, why it was needed, and who may need to review it next. Even when the app makes the action straightforward, the quality of the final record still depends on the person entering enough detail. A rushed submission can move through a workflow quickly while remaining unhelpful to anyone checking it later.
Step two: turn a transaction into something reviewable
The next stage is where Ramp separates itself from a simple note-taking tool. A finance reviewer does not only need the amount; they need enough surrounding information to decide whether the item is understandable and ready to move forward. I would use the app to make the transaction legible to someone who was not present when the purchase happened.
This is especially helpful when the person who spent the money is not the same person who manages the budget. The employee knows the immediate reason for the purchase, while the reviewer knows the company’s broader priorities. A good handoff respects both viewpoints. It avoids forcing the reviewer to reconstruct the story from a bank statement, a message thread, and an image of a receipt stored somewhere else.
My tip would be to write for the next person, not for myself. A note that makes perfect sense at the moment may be vague a month later. Naming the project, trip, customer meeting, or internal purpose gives the record more lasting value. This is not a flashy feature, but it is the kind of habit that determines whether a finance app actually saves time.
Step three: keep approval from becoming a chat conversation
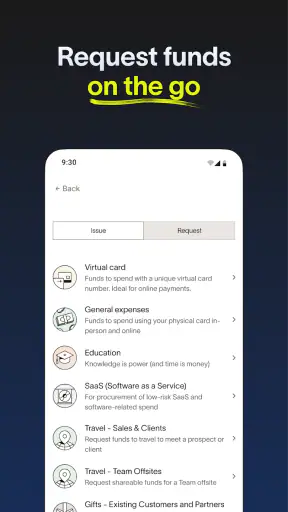
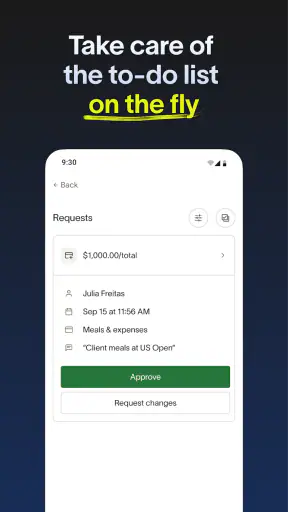
Many business spending problems are really communication problems. Someone says “go ahead” in a message, another person assumes the approval was recorded, and finance later has to find the original conversation. Ramp is most useful when it keeps the spending item and its review together instead of letting the decision disappear into an unrelated chat.
For a small team, that can make the workflow easier to follow. The person requesting or recording the expense knows where it stands, the reviewer has a clear item to inspect, and the finance owner can see which tasks still need attention. The result is not necessarily fewer decisions; it is fewer disconnected places where those decisions can be lost.
There is a trade-off here. A structured workflow asks users to change their habits. People who are used to sending a quick message may see the app as an extra step, especially for low-value purchases. I would introduce it by agreeing on which types of spending must go through the process and which can remain lightweight. Without that team agreement, even a well-designed finance app can become another inbox.
Step four: complete the finance handoff
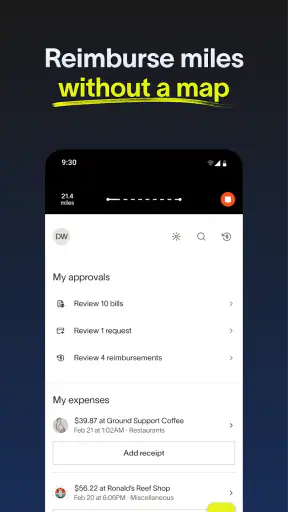
Once the employee has supplied the context, the responsibility shifts toward the person who checks business spending. This is where the app’s value becomes organizational rather than merely personal. Finance staff can work from the information submitted by the team instead of repeatedly chasing receipts and explanations.
I would still expect a reviewer to question unclear items. Automation cannot know every company rule or recognize every unusual business situation. The better outcome is that the reviewer spends time making decisions rather than doing detective work. If a charge needs clarification, the app should be treated as the place to resolve that question, not simply as a box to tick.
For a manager, the important insight is that speed and control are not opposites. A fast process is useful only when it leaves enough evidence to understand the purchase. Ramp fits teams that want a repeatable route from spending to review, but it will not compensate for unclear internal ownership. Someone still needs to define who checks what and how quickly unresolved items should be handled.
What the completed workflow feels like
When the process works, the outcome is modest but meaningful: a business charge has a reason attached to it, the relevant people know where it stands, and the finance owner has less manual follow-up. I would not describe that as a dramatic transformation after one transaction. The benefit appears through repetition, especially when the same process is used across many employees and many small purchases.
This is also why the app’s store summary, “Time is money. Save both,” makes more sense as a workflow idea than as a promise of instant savings. The time saved is the time that would otherwise be spent looking for missing information, forwarding receipts, and asking who approved a charge. Whether that becomes meaningful depends on consistent use across the team.
The app’s free price lowers the barrier to trying it, which is useful for a business that wants to test the mobile experience before committing its staff to a new routine. Still, “free” should not be confused with “effortless.” The real cost may be onboarding, deciding how the company will use it, and getting employees to complete their part of the process promptly.
Where the workflow breaks
The first weak point is adoption. If one employee records every expense while everyone else continues using email, chat, or paper receipts, the company ends up with two systems instead of one. Ramp can provide a central place for the finance side, but it cannot force a team to stop creating parallel records.
The second weak point is ambiguity. A transaction with no useful explanation is still difficult to review, even if it appears neatly inside an app. I would be cautious about judging the tool by how quickly I can submit an item. The more important question is whether another person can understand it without contacting me again.
The third is fit. A very small operation with only one person making purchases may find a spreadsheet or existing banking tools sufficient. At the other extreme, a larger organization with highly specialized accounting, procurement, payroll, or reporting requirements may need a broader platform than a mobile finance app alone. Ramp can be a practical layer in a business spending process, but I would not assume it replaces every financial system a company may already use.
There is also a human limitation: mobile convenience can encourage people to process items too quickly. A phone is excellent for capturing a receipt while I am away from my desk, but less comfortable for deep investigation across a large set of transactions. I would use the app for timely input and follow-up, while reserving more involved financial analysis for the tools and routines the business already relies on.
How it compares with familiar alternatives
Compared with a spreadsheet, Ramp offers a more natural place for a shared spending workflow. A spreadsheet can be flexible and inexpensive, but it depends heavily on manual formatting, permissions, reminders, and discipline. Ramp is the better choice when the problem is not merely recording numbers but moving an expense from employee to reviewer to finance owner.
Compared with a personal budgeting app, the difference is even clearer. Personal tools are usually designed around an individual’s income, bills, categories, and goals. They are a poor match for an employee submitting a purchase that belongs to a company. I would choose Ramp when the central question is “how should this business expense be handled?” rather than “how much can I spend this month?”
Compared with email and workplace chat, the app provides a more durable home for the transaction. Messages are useful for quick discussion, but they are easy to lose among unrelated conversations. Ramp is preferable when the record needs to remain connected to the spending item. Chat may still be useful for unusual cases, but it should not be the only place where an approval or explanation exists.
Compared with a full accounting package, Ramp appears more focused on the front end of business spending: getting information from the people who make purchases and making it easier for finance to review. A dedicated accounting system may be better for comprehensive books, tax preparation, detailed reporting, and other specialized work. I see the two approaches as potentially complementary rather than interchangeable, depending on the company’s existing setup.
Who will get the most from it
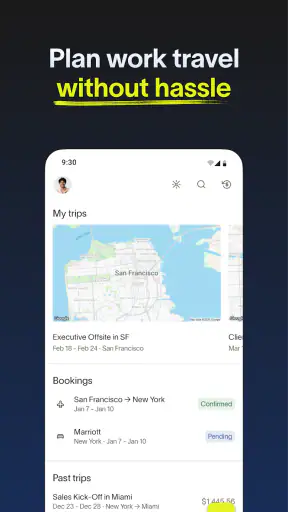
I would recommend trying Ramp if a team has started to outgrow informal expense handling. It is particularly suitable when employees spend on behalf of the business, managers need visibility before or after purchases, and finance staff are tired of requesting the same missing details. The app is also a good fit for teams whose members are frequently away from a desk and need to complete finance tasks from a phone.
The strongest use case is not one spectacular purchase. It is the steady stream of ordinary expenses that creates administrative drag: subscriptions, travel, supplies, meals, and project-related costs. When those items arrive through a consistent route, the company gains a clearer rhythm for reviewing them.
I would skip it, or at least test it carefully, if I wanted personal money management, if my business has almost no shared spending, or if my team refuses structured approval habits. I would also compare it with a more comprehensive financial platform when the main requirement is advanced accounting rather than employee-facing expense handling.
My practical setup advice
Before asking everyone to use the app, I would define a simple internal rule: which purchases belong in Ramp, who reviews them, and what information makes an item complete. That preparation is more important than persuading people with the app’s feature list. A clear process gives the mobile tool a job; without one, it becomes another place to enter the same information.
I would start with a small group and a familiar category of spending. That makes it easier to see where the handoff fails: perhaps employees forget context, managers do not know when to review, or finance receives too many vague submissions. Fixing those points early is better than launching the workflow across the whole company and discovering that nobody agrees on what “done” means.
It is also worth deciding how the team will handle exceptions. A purchase may be urgent, a receipt may arrive later, or the person who normally reviews it may be unavailable. A useful process includes a clear path for those cases. The app can organize the normal route, but the company still needs a human decision for unusual spending.
Final assessment
After looking at Ramp as a complete business-spending journey, I see a focused finance app rather than a universal money manager. Its strongest contribution is the connection between a purchase, the person who made it, the person who needs to review it, and the finance record that remains afterward. That makes it more relevant to a growing team than a personal budgeting app or an improvised spreadsheet.
I like the mobile timing of the workflow: information can be handled close to the moment of spending, when the reason and receipt are easiest to remember. I also appreciate that the app’s usefulness depends on better handoffs, not just on displaying balances. The limitations are just as important: adoption takes effort, vague submissions remain vague, and companies with complex financial needs may require more than this app can provide on its own.
With a clear internal process, Ramp is worth considering for teams that want fewer scattered expense conversations and a more dependable route from purchase to review. For a solo user seeking household budgeting, I would choose something else. For a business where several people spend money and someone must make sense of it afterward, this free app offers a sensible place to begin.
Developed by Ramp Business Corporation, it has reached more than 100 thousand installs and carries an Everyone age rating, making it approachable from a store perspective. My recommendation is still practical rather than automatic: install it, run one complete expense through the process, and judge whether the handoff is genuinely clearer for your team. If it is, the value will come from using that workflow consistently, not from simply having another finance app on a phone.
FAQ
What is Ramp and what can I use it for?
Ramp is a digital finance and expense-management platform designed to help businesses control spending, issue and manage company cards, automate expense reporting, and monitor financial activity. After reviewing its main features, it is best suited to companies rather than casual personal users. Its tools are focused on business workflows, approvals, accounting organization, and giving administrators greater visibility over employee purchases.
Is Ramp free to download and use?
Ramp may be available without a traditional upfront software charge, but users should not assume that every feature is completely free. Pricing, eligibility, card availability, and access to advanced services can depend on the business, its location, account approval, and the selected plan or financial products. Before signing up, review the current terms carefully, including any fees, requirements, and conditions related to cards or other services.
Who is eligible to use Ramp?
Ramp is primarily intended for registered businesses and their authorized employees, not for ordinary personal spending. During registration, the company may need to provide business, identity, ownership, and financial information for verification. Availability can also vary by country, business structure, and product type. If you are an individual looking for a personal budgeting or payment app, Ramp may not be the most suitable option.
Is Ramp safe for managing business expenses?
Ramp includes security and administrative controls intended to reduce unauthorized spending and improve financial oversight. Businesses can typically set spending limits, create approval rules, review transactions, and manage access for employees. However, no financial platform is completely risk-free. Users should protect login credentials, enable available security features, review account activity regularly, and download the app only from an official store or verified source.
Does Ramp integrate with accounting and other business tools?
One of Ramp’s main advantages is its focus on connecting expense management with existing business processes. Depending on the current plan and region, it may support integrations with accounting, payroll, travel, communication, and productivity tools. These connections can reduce manual data entry and simplify reconciliation, but setup may require administrator permissions and careful configuration. Check the latest supported integrations before choosing Ramp for your company.











