

Plynk: Grow as an Investor
4.1FinanceUpdated October 2, 2026
Screenshots
Pros
- Simple interface makes investing approachable for beginners.
- Supports recurring investments to help build consistent habits.
- Offers educational content for learning basic investing concepts.
- Fractional investing can make diversified portfolios more accessible.
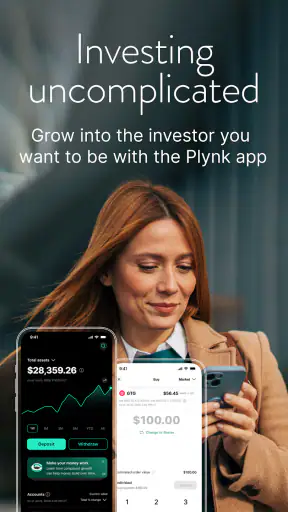
- Provides a clear overview of portfolio performance and activity.
Cons
- Investment options may feel limited compared with larger brokerages.
- Market data and portfolio values may not update instantly.
- Fees and spreads can reduce returns on smaller investments.
- Advanced trading tools and research features are limited.
- Availability and account features may vary by country and eligibility.
 Analysis By Mobexer
I approached Plynk: Grow as an Investor as a practical finance app rather than a replacement for a full brokerage workstation. Its main appeal is straightforward: it tries to make investing feel less intimidating by putting learning and investing tools in the same place. After spending time with it, I found the experience most convincing for someone who wants a calmer introduction to the market, not for an experienced trader who needs a dense screen full of advanced controls.
The app is free, aimed at everyone, and produced by Digital Brokerage Services LLC. It sits in the finance category, where the usual choices often split into two extremes: simplified investing apps that hide much of the learning process, and powerful brokerage platforms that can overwhelm a beginner. Plynk takes the middle route. That makes it approachable, but it also means its usefulness depends heavily on what you expect from an investment app.
How Plynk feels in its current form
The first thing I noticed is that the product is built around reducing friction. Instead of assuming that I already understood market terminology, it presents investing as something I can explore gradually. That tone matters. A person opening a brokerage app for the first time can easily mistake a complicated interface for expertise, while Plynk makes a visible effort to keep the starting point understandable.
That simplicity is not merely cosmetic. The app works best when I use it as a learning companion: I can think about a company or investment idea, review the information available in the app, and then decide whether it deserves more attention. This is a healthier workflow than opening a chart and reacting to every movement. I would still verify important decisions elsewhere, but Plynk gives a new investor a less intimidating place to begin.
The current release is version 4.4.2, and the app requires iOS or Android software version 12 or later. Those requirements are worth checking before downloading, particularly if you keep an older phone for financial apps. On a supported device, the experience feels designed for regular mobile use rather than occasional account maintenance from a desktop.
A useful starting point for people who are still learning
I would recommend Plynk first to someone who knows they want to invest but has not yet developed a routine. The app’s educational focus can help turn vague curiosity into better questions: What am I buying? Why does this investment interest me? How long am I prepared to hold it? What would make me change my mind?
Those questions are more valuable than simply finding a popular ticker. In my experience, beginner apps are most useful when they slow down impulsive decisions without making the process feel like homework. Plynk’s combination of intuitive tools and education is well suited to that role. It does not need to turn a new user into a market expert immediately; it needs to help that person avoid treating investing like a guessing game.
There is also a practical benefit for users who prefer learning in small sessions. Someone commuting, waiting for an appointment, or reviewing personal finances at the end of the day can use a phone-based app more naturally than a traditional trading terminal. I found that this encourages a repeatable habit: read a little, compare an idea with my own goals, and leave the decision until I have thought it through.
Where the simple design helps—and where it stops helping
The clean approach is a strength when the alternative is confusion. A beginner can focus on the decision instead of learning a complicated menu system first. That makes Plynk less intimidating than many established brokerage apps, especially for users who do not want to study technical charting before they understand basic investing concepts.
However, simplicity has a cost. As my questions become more specific, I may want deeper research, more detailed comparisons, or a wider range of controls than the app is designed to provide. This is the central trade-off: Plynk lowers the entry barrier, but it is not the obvious destination for someone whose process already involves advanced analysis.
I would not judge that limitation as a flaw by itself. A focused beginner experience can be better than a crowded platform that tries to serve everyone. The important point is to know when the app’s role should change. I see it as a place to build confidence and organize early decisions, not as the only research source for every investment choice.
What the recent version says about the product’s direction
The app was released on April 14, 2021, and its current version shows that it has continued to develop rather than remaining a one-time launch. The version number matters less to me than what it suggests about the product’s direction: Plynk is still being maintained as a living mobile investing experience, with attention on the core promise of making investing easier to understand.
I would be careful, though, about reading a version update as evidence that every part of the app has changed dramatically. A newer release does not automatically mean a complete redesign, broader research coverage, or a professional-grade feature set. What I can reasonably take from the current release is that the app remains relevant to its original audience and that existing users are not relying on an abandoned product.
That distinction is useful when deciding whether to switch from another brokerage app. If I already have a platform that handles my investing needs well, a new version alone is not a reason to move everything. Plynk becomes interesting when the problem is not simply buying and holding, but understanding what I am doing along the way.
How the evolution affects someone already using it
For an existing user, continued development is most valuable when it preserves a familiar workflow while making the experience clearer. People who use a finance app regularly do not want every update to force them to relearn basic navigation. Plynk’s identity is tied to approachability, so I would expect the best improvements to be the ones that make education and investing feel more connected without adding unnecessary complexity.
That matters in an everyday scenario. Imagine I receive a small amount of money after paying regular bills and decide to put it toward a long-term investment rather than spending it immediately. With Plynk, I can approach that moment as a learning exercise: review the idea, consider whether it fits my goal, and make a measured decision. The app is more helpful when it supports that repeatable process than when it encourages me to chase whatever is moving today.
Another useful workflow is keeping a short personal note outside the app about why I made a purchase. I can record the goal, the expected holding period, and the condition that would make me reconsider. That simple habit prevents an educational app from becoming a source of random transactions. Plynk can provide the accessible interface, but the discipline still has to come from me.
Users coming from a more advanced platform may experience the opposite effect. They may appreciate the less cluttered presentation but miss the depth they have grown accustomed to. In that case, the sensible approach is not necessarily to delete the old app. Plynk can serve as the beginner-friendly layer for learning and basic monitoring, while a more comprehensive brokerage remains available for research that demands greater detail.
Three ways I would use it beyond the obvious first download
First, I would use the educational material before making a watchlist, not after. Many people collect investment ideas first and only learn the basics when they are ready to buy. Reversing that order helps me recognize whether I understand the risk, time horizon, and purpose of an investment before becoming emotionally attached to it.
Second, I would treat the app as a decision checkpoint rather than a notification machine. The most useful routine is to open it at a planned time, review what I intended to learn, and close it once that task is complete. This reduces the temptation to turn every market movement into an urgent action. An intuitive interface should make thoughtful use easier, not make constant checking feel necessary.
Third, I would use Plynk to explain investing to another beginner by walking through the learning process together. A friend or family member who feels excluded by financial jargon may understand the basics more comfortably in a guided mobile environment. The important boundary is to discuss concepts and personal goals, not to present one person’s investment choice as a universal answer.
These workflows reveal the app’s real strength. It is not simply that the interface looks friendly; it is that the product can help establish better habits around research and decision-making. That is a more meaningful benefit for a beginner than a long list of technical functions.
What it still does not replace
I would not rely on Plynk alone for every financial question. Investing decisions can depend on tax circumstances, emergency savings, debt, income stability, and goals that an app cannot understand from a quick interaction. A person who is still building a cash reserve may need to solve that problem before focusing on market exposure.
I would also look elsewhere if my main priority were highly detailed analysis or an extensive professional workflow. Traditional brokerage platforms may be a better fit for users who already know exactly which research tools they need. A specialized financial education resource may also be preferable for someone who wants a structured course rather than an app that combines learning with investing.
The same caution applies to users who expect investing to produce quick results. Plynk’s approachable design could make the process feel easy, but ease of use is not the same as low risk. The app may help me understand the first steps; it cannot remove uncertainty from the market. Anyone uncomfortable with the possibility of losing money should pause before treating a simple interface as reassurance.
Ratings, reach, and what they mean to a new user
Plynk has an average rating of 4.1 from around 4.1 thousand ratings, along with roughly 590 written reviews. More than 500 thousand people have installed it, which gives me some confidence that the app has found a real audience rather than existing only as a niche experiment.
I would still treat those figures as context, not as proof that it will suit me. Ratings can reflect very different expectations: one user may value a clear introduction, while another may be disappointed because the app does not feel like a full trading terminal. The written feedback is more useful when I read it through that lens and ask whether the reviewer’s needs resemble mine.
The Everyone age rating also makes the app broadly accessible from a content perspective, but that should not be confused with suitability for every financial situation. A younger or inexperienced user may still need guidance from a trusted adult or qualified professional before making decisions involving real money.
Small frictions worth considering before committing
The first friction is the learning curve hidden inside the word “simple.” A clear interface can make the first screen comfortable, but investing itself remains a subject that takes time to understand. I would not download Plynk expecting the education to replace patience. The app can organize the beginning of the journey, while the user still has to read carefully and accept that some answers will not be immediate.
The second is the danger of confusing convenience with completeness. Because a mobile app is always close at hand, it can encourage frequent checking. That behavior is especially unhelpful for a long-term investor who has not defined a reason for opening the app. I would set a personal schedule and use the tools intentionally rather than allowing market noise to dictate my routine.
The third is the likely transition point for growing users. Someone may begin with Plynk and eventually need more detailed resources. That is not a failure; it is a normal part of becoming more informed. The smart choice is to recognize that transition early instead of forcing one beginner-oriented app to handle every future requirement.
What I would watch as the app continues to develop
Future progress should be judged by whether Plynk becomes more useful without losing its calm, understandable character. I would watch for improvements that make educational material easier to connect with real decisions, clarify information at the moment it matters, and help users build consistent habits rather than react to short-term noise.
I would also pay attention to how the app serves users who outgrow the basics. There is a delicate balance here. Adding too much complexity could undermine the reason beginners choose Plynk, while failing to support a more informed audience could make the app feel temporary. The strongest evolution would preserve the welcoming starting point while offering a sensible path for users who want to deepen their understanding.
For someone deciding whether to try it now, my advice is simple: install it if your main obstacle is uncertainty about how to begin. Give yourself time to use the educational side before treating the investing side as a shortcut. If you already have a detailed strategy, need advanced research, or prefer managing finances from a full desktop platform, another option may serve you better.
Overall, I see Plynk as a thoughtful entry point into mobile investing education. It is free, approachable, and focused on helping ordinary users feel less lost at the start. Its limitations become clearer as expectations rise, but that honesty is part of the appeal. Plynk: Grow as an Investor is worth considering when you want to build understanding and a repeatable routine—not when you are looking for a high-powered trading command center.
FAQ
What is Plynk: Grow as an Investor?
Plynk: Grow as an Investor is an investment app designed to make getting started with stocks, exchange-traded funds, and other market opportunities easier for beginners. Its interface focuses on simple explanations, guided investing, and accessible account management. It is intended for users who want to learn while building an investment portfolio, rather than for experienced traders seeking advanced charting or complex order tools.
Is Plynk suitable for beginner investors?
Yes, Plynk is primarily aimed at people who are new to investing or want a more approachable way to manage their money. The app generally presents investment concepts in plain language and helps users explore available assets without overwhelming them with professional-level features. However, beginners should still understand that investments can lose value and should research each product before committing money.
What can I invest in through Plynk?
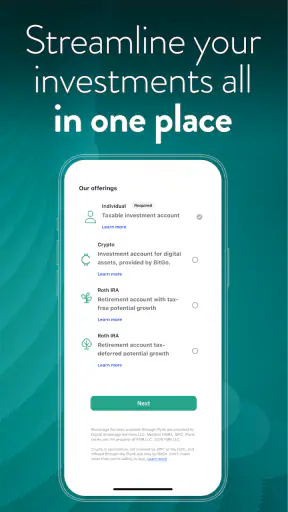
The investment choices available through Plynk may include individual stocks, ETFs, and other supported market products, depending on your location, account eligibility, and the services currently offered by the platform. Availability can change over time, so users should check the app’s latest product list before signing up. Fractional investing may also be available for selected assets, but conditions can apply.
Is Plynk safe and regulated?
Plynk uses standard security practices intended to protect user accounts and personal information, such as login safeguards and encrypted connections. Investment services are typically provided through regulated financial entities, and eligible accounts may receive applicable investor protection under local rules. Nevertheless, regulation does not guarantee investment returns. Before depositing money, review Plynk’s legal disclosures, fees, privacy policy, and protection limits.
Does Plynk charge fees, and how much money do I need to start?
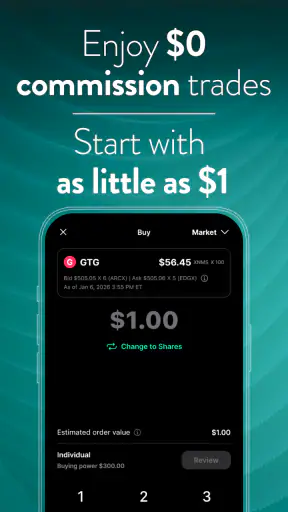
The amount required to begin investing and the fees charged by Plynk depend on its current pricing structure, the type of transaction, and your region. Some features may have no commission while other services, transfers, or account activities could involve charges. The app may support starting with a relatively small amount, but users should carefully read the fee schedule and minimum-balance information before funding an account.











