

Payday Advance Borrow Money
4.7FinanceUpdated October 5, 2026
Screenshots
Pros
- Fast application process with minimal paperwork
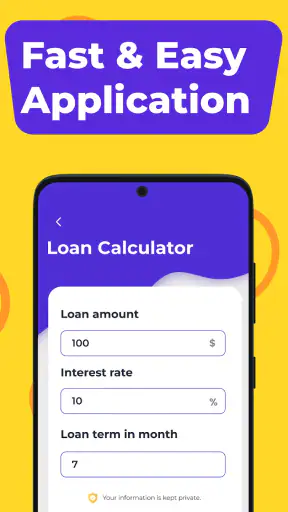
- Clear repayment schedule shown before accepting an advance
- Useful for covering unexpected short-term expenses
- Mobile access makes managing advances convenient
- May help avoid overdraft fees in urgent situations
Cons
- High fees can make borrowing expensive
- Repayment may be withdrawn automatically from your account
- Eligibility and advance limits vary by user
- Late repayment could lead to additional charges
- Not suitable as a long-term solution for recurring expenses
 Analysis By Mobexer
When an unexpected bill lands between paydays, the hardest part is often not finding a borrowing app but understanding what you are agreeing to. Payday Advance Borrow Money is a free finance app from Shpuryk Sergii that focuses on helping users find a suitable payday cash advance. I approached it less like a shortcut to money and more like a screening tool: useful when I needed to organize my options quickly, but deserving of careful attention before any application or borrowing decision.
My overall impression is mixed in a practical way. The app is easy to understand at a glance, and its purpose is much narrower than that of a full banking app or budgeting platform. It is aimed at people looking for short-term borrowing rather than people trying to manage their entire financial life. That focus can be helpful, but it also means the app should be used with a clear limit in mind: finding an advance is not the same as finding an affordable solution.
What the app is really useful for
The store summary presents the app as a way to find a suitable payday cash advance, and that description matches the role I would give it. I would not treat it as a digital wallet, emergency savings account, credit-building service, or replacement for a bank. Its value is in bringing attention to a specific type of short-term loan search, where speed and simple comparison may matter more than long-term financial planning.
That distinction is important because payday borrowing can solve a timing problem while creating a repayment problem. If I had a utility payment due before my salary arrived, I could use the app to explore whether an advance might fit the situation. I would first write down the amount I actually needed, the date I expected to repay it, and the total cost I could genuinely afford. Without those three details, the convenience of a quick application could make the decision feel easier than it really is.
The app has a 4.7 average from around 3.2 thousand ratings, with more than 100 thousand installs. Those figures suggest that many people have found the experience useful enough to rate, but they do not tell me whether a particular advance will be suitable for my circumstances. A strong app rating is an opinion about the application experience, not a guarantee about a lender, approval, repayment terms, or the outcome of an individual application.
It is also worth separating the developer from any lender a user may encounter through the process. Shpuryk Sergii is listed as the developer of the app. That identification helps me understand who publishes the software, but it should not be confused with the company that might offer or administer a loan. Before accepting anything, I would check the name of the actual provider, the repayment schedule, the total amount due, and the consequences of missing a payment.
Trust starts with the screen in front of you
My trust test for a finance app begins with visible choices rather than attractive wording. I want to see what action I am taking, what information is being requested, and whether I can stop before submitting anything. With a payday advance tool, those details matter more than a polished interface because the decision can affect my bank balance long after I close the app.
I would move slowly through each screen and read every consent prompt instead of tapping through automatically. If the app presents a form, I would prepare the information beforehand and avoid guessing. Incorrect income, employment, or repayment details can lead to an unsuitable result, while entering more personal information than necessary can create a separate privacy concern.
A useful habit is to take note of the provider name and the terms shown before moving forward. I would save the repayment date and total repayment amount in my own notes, not rely on memory or assume that an initial estimate is the final offer. If the app takes me toward a provider, I would treat that transition as a new decision point and review the provider’s own disclosures independently.
The app is free to install, which removes an upfront purchase barrier. That does not mean borrowing through it is free. The software price and the cost of a cash advance are entirely different things, and confusing them is one of the easiest mistakes to make. I would never interpret “free” as meaning that the loan search, loan offer, or repayment carries no fees or interest.
Controls I would check before sharing information
My first practical check would be the permission screen shown by my phone during installation or use. I would look at each requested permission and ask whether it makes sense for the task I am trying to complete. If a permission appears unrelated to finding or applying for a cash advance, I would pause rather than approve it automatically.
Android users can review and change permissions through the operating system settings after installation. That gives me a useful control: I can revisit what the app is allowed to access instead of treating the first approval as permanent. I would also check whether denying a permission still lets me browse or proceed, because that tells me whether the permission is essential to the particular action or simply being requested broadly.
I would keep account details, identity information, and financial records separate from casual notes or screenshots stored in shared locations. If I needed to record an offer for comparison, I would capture only the necessary terms and avoid saving sensitive documents in an unprotected gallery or cloud folder. This is a small workflow change, but it reduces the chance of leaving personal information scattered across my phone.
Another useful control is stopping before the final submission. I would look for a clear review stage where I can inspect the requested amount, repayment date, provider identity, and any displayed cost. If those details are difficult to find, change unexpectedly, or appear only after I have committed personal information, I would treat that friction as a reason to leave and consider another route.
Where financial privacy needs extra attention
Finance apps naturally involve sensitive moments. A user may be asked for information connected to income, employment, identity, or a bank account. I would consider every such request high sensitivity, even if it appears routine. The fact that an app is designed for borrowing does not mean I should provide every detail immediately or assume that every request is necessary for every stage.
I would use the minimum information needed to understand the next step, then reassess before continuing. For example, browsing an option and submitting a full application are different activities. I would not provide application-level information merely to see whether the app’s general process suits me. If a form makes that impossible, I would decide whether the possible convenience is worth the loss of control.
I would also read the privacy explanation and consent language shown during use, paying attention to who receives the information and what action my consent enables. I am especially cautious when a screen uses broad wording or combines several permissions and disclosures into one quick button. A short pause to expand the text can reveal whether I am agreeing to a specific application step or a wider sharing arrangement.
When I finish, I would not assume that closing the app ends every process. I would check for confirmation messages, emails, text messages, or provider accounts created during the application. If I decided not to continue, I would look for an option to withdraw from the process or contact the relevant provider directly. I would keep a simple record of whom I contacted and when, particularly if I had already submitted personal information.
These habits are not accusations against the app or its developer. They are sensible safeguards for any service connected with borrowing. Payday Advance Borrow Money puts the user near decisions involving personal and financial information, so the user should remain active rather than treating the app as an automatic recommendation engine.
A realistic way I would use it
Imagine I have a necessary household payment due several days before my next income arrives. I would begin outside the app by checking whether the bill can be moved, split, or covered through an existing buffer. I would also ask whether borrowing a smaller amount would solve the immediate issue. Only after those options would I open the app to explore a payday advance.
Inside the process, I would compare the amount requested with the amount I can repay on the stated date, not with the amount I hope to have. I would write down the full repayment figure and check whether another automatic payment is scheduled for the same period. A loan that appears manageable in isolation can become difficult when combined with rent, subscriptions, transport, and ordinary food costs.
If an offer or provider looks suitable, I would leave the app and review the terms again with a clear head. I would check for fees, the repayment method, late-payment consequences, and whether the schedule matches my actual income date. If I could not explain the total cost in plain language, I would not accept it. The most useful feature of the app in this scenario is not speed; it is giving me a starting point for a decision I can verify.
After making a choice, I would set a reminder several days before repayment and keep the confirmation details somewhere private. I would not wait until the due date to discover that the account balance is short or that the repayment method differs from what I expected. This workflow turns the app into one part of a controlled process rather than the place where the entire decision happens impulsively.
Who should use it, and who should look elsewhere
I can see the app helping someone who has a one-off timing gap, understands short-term borrowing, and is willing to inspect every condition before submitting an application. It may also suit a user who wants a focused payday advance search instead of installing a broad personal finance suite. The Everyone content rating and compatibility with Android devices running version 5.0 or later make it accessible to a wide range of Android users.
It is a poor fit for someone already using one payday loan to repay another, someone without a dependable repayment date, or anyone whose regular expenses already exceed income. In those situations, another advance can postpone the underlying problem and increase pressure. A conversation with a bank, credit union, debt adviser, employer, or trusted support service may be more appropriate than another short-term application.
I would also skip it if I wanted budgeting, spending categorization, savings goals, bill tracking, or a complete view of several accounts. A conventional budgeting app is better for identifying where money goes and planning ahead. A bank’s own app may be better when I need to review an existing overdraft, transfer money, or discuss hardship options with an institution that already knows my account.
For users who mainly want to compare longer-term personal loans, a dedicated loan comparison service may offer a more relevant experience. For users who need a small emergency cushion repeatedly, building a modest savings buffer or arranging a lower-cost line of credit may be more sustainable. The right alternative depends on the problem: this app addresses a short-term advance search, not every form of financial strain.
Version, accessibility, and everyday friction
The current version is 1.2.1, and the app is free to use as an installation. I found those details useful mainly because they set expectations about access, not because they change the financial decision. A user on an older compatible Android phone may be able to install it, but compatibility alone does not guarantee that every lender flow or external page will feel equally smooth.
The narrow purpose is both a strength and a limitation. I do not have to navigate a crowded dashboard filled with unrelated banking tools, but I also should not expect the app to help me understand my wider financial position. The focused design can encourage quick action, so I would deliberately add my own pause between finding an option and accepting one.
Another point of friction is that the most important decision may happen beyond the app itself. Once a provider’s application or terms become central, I would judge that provider’s disclosures and controls separately. The app can help me reach an option, but it cannot replace my responsibility to verify the final agreement presented by the company offering the advance.
My cautious verdict
After reviewing Payday Advance Borrow Money, I see it as a focused doorway into short-term cash advance searches rather than a complete financial companion. Its free access, clear purpose, and broad Android compatibility make it easy to try, while its strong user rating indicates that the basic experience has appealed to many people. Those are reasonable reasons to consider it when a genuine, temporary cash-flow gap needs attention.
Still, I would recommend it only with firm boundaries. I would review permissions, limit the information I share at each stage, identify the actual provider, record the total repayment, and stop if the terms are unclear. I would never choose an advance solely because the app makes the search feel quick or convenient.
My bottom line is simple: use it as a cautious research step, not as permission to borrow. If I had a reliable repayment plan and had already checked less expensive alternatives, it could be useful. If repayment depends on another loan, an uncertain future income, or optimistic budgeting, I would skip it and seek a solution that addresses the wider financial problem instead.
For the right user, Payday Advance Borrow Money can make a narrow search easier to begin. For everyone else, the most valuable decision may be recognizing that a payday advance is not the right answer before submitting an application.
FAQ
What is Payday Advance Borrow Money?
Payday Advance Borrow Money is a financial app designed to help users explore short-term borrowing options through a mobile device. It may collect personal, employment, income, and banking information to assess eligibility or connect users with potential lenders. The app is not a guaranteed approval service, and available offers, loan amounts, fees, and repayment terms can vary according to your profile and location.
How does the borrowing process work in the app?
After installing the app, you generally complete a request form with details such as your identity, income, employment, and bank account. The information may be reviewed by the app or shared with lending partners to identify possible offers. Before accepting anything, carefully check the annual percentage rate, origination or service fees, repayment date, and total amount you will owe.
Are loans guaranteed, and what eligibility requirements may apply?
Approval is not guaranteed, even if you complete the application successfully. Requirements can differ between lenders, but applicants may need to be adults, have a valid identification document, a regular source of income, an active bank account, and a verifiable phone number or email address. Credit history, state regulations, and other financial information may also affect the result.
How much does borrowing through the app cost?
The cost depends on the lender and the specific offer you receive. Short-term payday-style loans can have high fees and a significantly higher annualized cost than traditional personal loans or credit products. Read every disclosure before agreeing, including the finance charge, APR, late-payment consequences, automatic withdrawal terms, and whether renewing or extending the loan creates additional costs.
Is Payday Advance Borrow Money safe to use?
Use caution and review the app’s privacy policy, permissions, developer information, and user feedback before submitting sensitive data. Never provide passwords, one-time security codes, or unnecessary account access. Confirm that the lender is legally authorized in your area, understand how your information may be shared, and avoid any service demanding an upfront payment before showing clear loan terms.











