

Park National Bank
4.3FinanceUpdated October 2, 2026
Screenshots
Pros
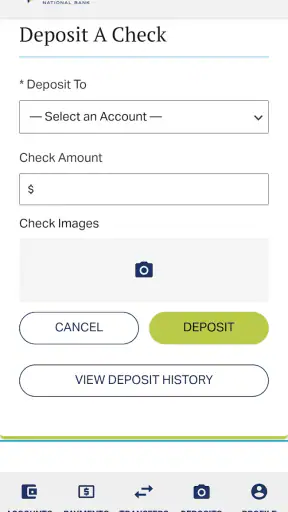
- Mobile check deposit saves time and reduces branch visits.
- Custom alerts help users monitor balances and account activity.
- Bill pay supports convenient scheduling of recurring payments.
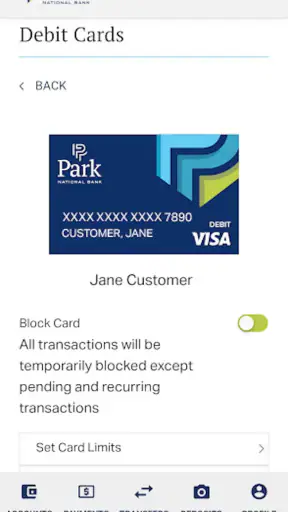
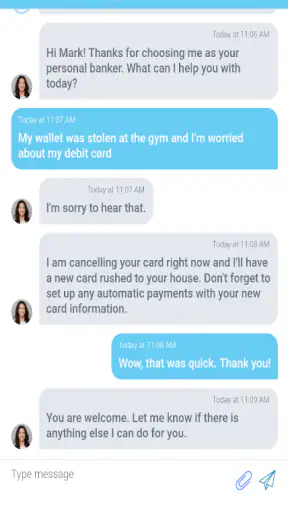
- Card controls can improve security when a card is lost or stolen.
- Secure login options help protect access to personal banking information.
Cons
- Some features may be limited to Park National Bank customers.
- Mobile deposit limits can vary by account and may restrict larger checks.
- Transfers to external banks may take several business days to complete.
- The app’s usefulness depends on reliable internet or mobile data access.
- Certain services may redirect users to contact support or visit a branch.
 Analysis By Mobexer
Managing a bank account from a phone is only useful when the important tasks feel clear rather than stressful. I approached Park National Bank with that standard in mind: could a first-time user move from installation to a genuinely useful banking action without feeling lost? This free finance app is built for customers of Park National Bank, and its purpose is straightforward—bringing everyday banking access to a mobile screen instead of making every task depend on a branch visit or a desktop browser.
The app comes from Park National Corporation and has been available since May 7, 2013. Its current version is 25.2.0, and it requires iOS or Android 11 or later. That combination tells me something practical: this is an established mobile-banking product rather than a brand-new experiment, but anyone using an older phone should check the operating system before planning a setup session.
Park National Bank has a 4.3 average from around 2.8 thousand ratings, with roughly 1.3 thousand written reviews and more than 100 thousand installs. Those figures suggest a reasonably established user base, although they should not be treated as a guarantee that every customer will have the same experience. Banking apps are especially dependent on account type, login status, device security, and the quality of the bank’s online service.
What to expect from the mobile banking experience
My first impression is that this is an access tool for existing Park National customers, not a general-purpose money-management app. That distinction matters. If you already bank with Park National, the app can become a convenient front door to your account. If you are looking for a way to compare banks, open an unrelated digital wallet, track investments across several institutions, or build a detailed household budget, this is probably not the right place to start.
The strongest reason to install it is convenience around routine banking. Instead of waiting until you are near a branch or opening a computer, you can reach your banking relationship from a compatible phone. That is particularly useful when you want to check whether a payment has cleared, review recent account activity, or confirm that your available balance is what you expected before making a purchase.
I would not judge the app by how many decorative features it has. For mobile banking, the better question is whether the basic path is dependable: sign in, understand what you are seeing, complete a needed task, and leave without uncertainty. Park National Bank is most appealing to people who value that direct relationship with their bank and do not need a separate financial dashboard to combine information from several providers.
The Everyone content rating also makes the app broadly suitable from an age-classification perspective. That does not mean every person should use it independently. A teenager, older relative, or anyone unfamiliar with mobile banking may still benefit from a careful first session, especially when learning how account information is presented and how to distinguish a completed action from one that is still waiting for confirmation.
One useful habit is to decide your first goal before opening the app. “I want to see whether a deposit arrived,” “I need to check a recent charge,” or “I want to confirm my balance before paying a bill” is better than tapping around without a purpose. A defined goal makes it easier to recognize success and helps you notice when the app is showing information rather than asking you to take an action.
Who will get the most from it
This app makes the most sense for an existing Park National customer who handles ordinary banking from a phone. It should suit someone who wants a quick account check during a busy day, a way to review activity after using a card, or a mobile alternative to signing in through a browser. It is also a reasonable choice for a customer who prefers dealing directly with the bank’s own application rather than connecting accounts to a third-party finance service.
The trade-off is that this direct focus can feel narrow. People with accounts at several banks may prefer an aggregator that puts everything in one view. Someone who wants spending categories, long-term charts, subscription detection, or a complete financial plan may find a bank-specific app less useful than a dedicated budgeting service. I would also skip it if you do not have a Park National relationship, since installing a banking app without an account purpose simply adds another login to manage.
Getting through the first setup without unnecessary confusion
Before installing, I would check the phone’s operating system and make sure I am using the official Park National Bank app associated with Park National Corporation. I would also choose a moment when I am not rushing. Mobile banking setup is not the kind of task I like to begin in a checkout line or while distracted, because the first sign-in is the point at which a small mistake can create avoidable frustration.
Have the credentials you normally use for Park National’s digital banking available, but do not share them with anyone helping you. If you are assisting a family member, let that person enter sensitive details themselves. This is a simple distinction, yet it prevents a helpful setup session from turning into a privacy problem. I would also avoid saving banking information in an unsecured note or sending it through a message just to make the process faster.
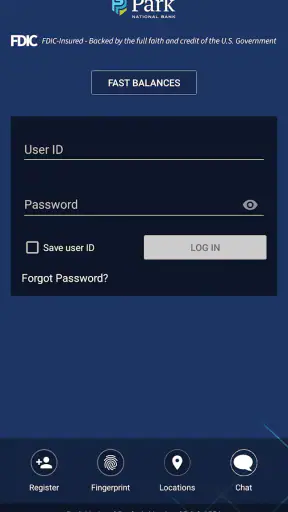
After installation, the sensible path is to open the app, identify the sign-in area, and use the same banking access you recognize from Park National’s other official channels. If the screen does not look familiar, stop and verify that you installed the correct application rather than repeatedly entering credentials. Repeated failed attempts are rarely a good troubleshooting strategy for financial accounts.
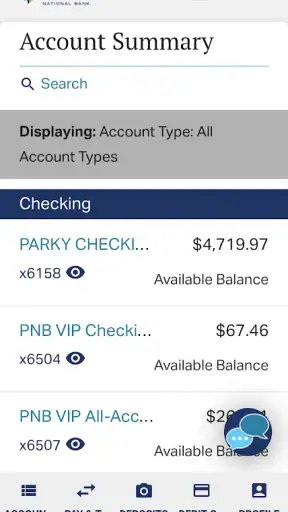
Once signed in, take a quiet minute to understand the first screen before selecting anything. Look for the account name or label, the balance information, and the recent activity area. The most important setup insight is that a balance is not always the same thing as money you can safely spend at that exact moment. Pending activity, timing differences, and transactions that have not fully posted can change what the number means.
I recommend making the first session observational. Confirm that the account you expect is visible, compare one or two recent transactions with your own records, and learn how the app distinguishes current information from activity still in progress. This is more valuable than immediately attempting a complicated task, because it gives you a reference point for future visits and makes unusual activity easier to spot.
The first meaningful success: verify something you already know
The best first action is one with a clear answer. For example, after buying something with your Park National account, open the app later and see whether the transaction appears. Alternatively, check whether a balance matches what you expected after a known transfer or deposit. This approach turns the first session into a low-risk test: you are not guessing whether the app worked because you already know what information should be there.
When the transaction appears, read the details carefully instead of relying only on the headline amount. Check the date, description, and status as displayed. A merchant name may not look exactly like the name you remember from a receipt, and a transaction that is visible may still be pending. That difference is one of the most useful lessons for new users, because it prevents the common mistake of treating every visible line as fully settled.
If your goal is simply to confirm your available funds, compare the balance with your own recent spending rather than assuming the number explains everything. I find it helpful to think of the app as a current view into the bank’s records, not as a substitute for keeping track of commitments. A rent payment, card purchase, or scheduled transfer may affect your plans even when it does not yet appear in the way you expect.
This first verification also creates a practical security routine. If you notice an unfamiliar transaction, do not dismiss it just because the amount is small. Review the description, consider whether another household member made the purchase, and use the bank’s established support route if it still looks wrong. The app helps you notice activity; it does not remove the need for judgment.
A realistic everyday example would be a customer leaving a grocery store and wondering whether an earlier payment has already reduced the account balance. Rather than waiting until the evening, the customer can open Park National Bank, review the visible activity, and make a more informed decision about the next purchase. That is the kind of modest success that makes a banking app worthwhile: not dramatic financial transformation, but less uncertainty at the moment it matters.
Common points of confusion during daily use
The first confusion many people face is the difference between seeing a transaction and seeing a completed transaction. A line in the activity list may represent movement that is still being processed. I would avoid making decisions based on a single number when several recent transactions are unsettled. If the app presents status information, read it; if the timing seems unusual, give the bank’s records time to update before assuming that money has disappeared or returned.
Another source of friction is selecting the wrong account when a customer has more than one relationship with the bank. Before reviewing an activity item or beginning a banking task, check the account label. This small pause is especially important when balances are similar. A quick action taken from the wrong account can be more troublesome than a slower action taken deliberately.
Users may also expect a bank-specific app to behave like a personal finance organizer. Park National Bank is designed around the Park National relationship, so I would not install it expecting a complete picture of credit cards, outside bank accounts, cash spending, and long-term goals in one place. If that is your main objective, a separate budgeting tool may be a better companion. The mobile banking app should remain the authoritative place for checking the bank account itself, while broader planning can happen elsewhere.
Login friction deserves a calm response. If access fails, first check whether the credentials were entered correctly and whether the phone meets the minimum operating system requirement. Avoid guessing repeatedly. If the problem continues, use Park National’s normal official support or account-recovery process rather than relying on advice from an unverified message or search result. A banking app is one area where speed should never outrank account safety.
Notifications and device behavior can also create false confidence. A phone alert, if available through the device and account settings, is not a replacement for opening the account when you need to verify a transaction. Alerts can be delayed, dismissed, or misunderstood. I treat them as prompts to check, not as final proof that a payment has settled or that a balance is safe to spend.
Privacy is another trade-off. The convenience of having banking access in your pocket is greatest on a personal, protected device. I would be cautious about signing in on a shared phone, handing an unlocked device to someone else, or leaving the app open in a public place. The app’s usefulness depends partly on habits around the phone itself, not only on the application’s screens.
How it compares with browser banking and finance alternatives
Compared with using a mobile browser, a dedicated app can feel more direct because it is always available as a separate banking destination. That separation is helpful when I want to check Park National activity without opening several browser tabs. On the other hand, browser access can be more convenient on a computer when I am reviewing records, working with several windows, or typing for a longer period. I see the app as the better tool for quick checks and the browser as a useful alternative for sessions where a larger screen matters.
Compared with a third-party money-management app, Park National Bank has a different advantage: it keeps the banking relationship in its own environment. That may reduce the need to connect the account to an outside service, which some users will value. The cost is a narrower view of your overall finances. If you regularly move money between several institutions or want consolidated spending analysis, an external tool may save time despite adding another connection to maintain.
Compared with visiting a branch or calling the bank, the app is more convenient for information you can safely handle yourself. It is not automatically better for every situation. A disputed transaction, unusual account problem, or question requiring personal explanation may still be better handled through Park National’s support channels. The app can help you gather the relevant account activity before that conversation, which is a useful preparation step even when it cannot resolve the issue by itself.
Small workflows that make the app more useful
One workflow I recommend is a two-stage balance check. First, look at the account balance. Then scan recent activity for pending or unexpected items before deciding whether you have enough room for a purchase. This takes longer than reading one number, but it is a better habit for avoiding surprises. The app is most helpful when you use it to interpret your situation rather than simply glance at a headline figure.
A second workflow is to use a known transaction as an anchor after any unusual account event. If you recently made a large payment or received money, compare the app’s activity with the confirmation you kept elsewhere. This gives you a simple personal audit trail and helps distinguish a display issue, a timing issue, and a genuinely incorrect transaction. It is especially useful for people who do not check their account every day.
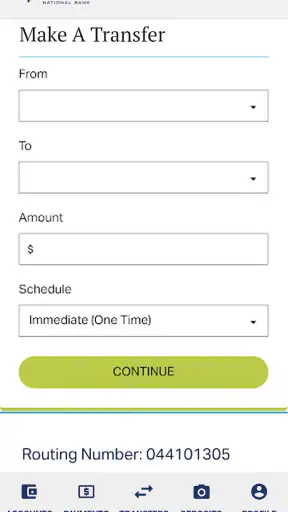
A third insight is to separate “checking” from “acting.” During the first few sessions, learn where information lives before attempting changes or transfers. Once you are comfortable identifying the correct account and reading transaction status, actions become less intimidating and less error-prone. I prefer this gradual approach to treating every visit as a race to finish the first task.
For households, agree on a clear rule about who reviews activity and how concerns are raised. The app can make account information easier to reach, but shared finances still require communication. A family member who sees an unfamiliar purchase should ask before assuming fraud, while a genuinely suspicious transaction should not be ignored simply because someone else might recognize it later.
Who should choose another option
I would look elsewhere if your main need is a complete financial command center rather than access to Park National banking. A budgeting app may be better for categories and spending plans. A multi-bank dashboard may be better for seeing several institutions together. A desktop browser may be more comfortable for detailed record work. None of those choices makes Park National Bank poor; they simply serve different jobs.
I would also hesitate to recommend it as a first step for someone who does not already bank with Park National, someone using an incompatible phone, or someone who expects every banking question to be solved inside an app. The best experience comes when the user understands what the app is for: convenient access to a specific bank relationship, with normal care around credentials, transaction status, and support.
My recommendation after the first few sessions
After using Park National Bank as a focused mobile banking tool, I see its value in reducing the distance between a question and an answer. You can check the account when a decision is in front of you, review activity while it is still fresh, and build a clearer routine around your Park National finances. The experience is less about discovering hidden entertainment and more about making ordinary banking less dependent on time and location.
My advice is to begin with one known transaction, learn the difference between a displayed item and a settled item, and confirm the account label before taking action. Those habits matter more than rushing through setup. If you want direct mobile access to Park National and your phone meets the operating system requirement, the free app is a sensible place to start.
The most important takeaway is simple: use the app to verify, then decide. Park National Bank is not a replacement for financial judgment, careful account security, or broader budgeting when you need it. It is a practical companion for Park National customers who want everyday account information close at hand, and its 4.3 average from a substantial group of users gives it a credible starting point for a first-time installation.
For me, the decision comes down to fit. If your banking life is centered on Park National and you want a straightforward phone-based route to your account, I would recommend trying it. If your priority is combining multiple institutions or analyzing spending in depth, keep a broader finance tool or browser workflow alongside it. Used for the job it is meant to do, Park National Bank can turn a quick account check into a calmer, more informed everyday habit.
FAQ
What is Park National Bank, and what can I do with its mobile app?
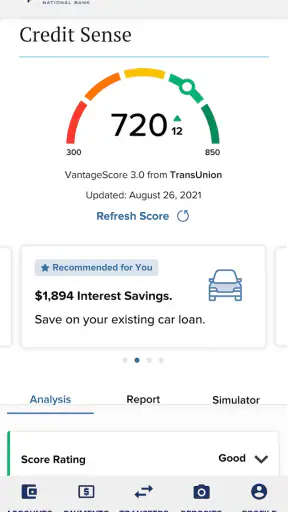
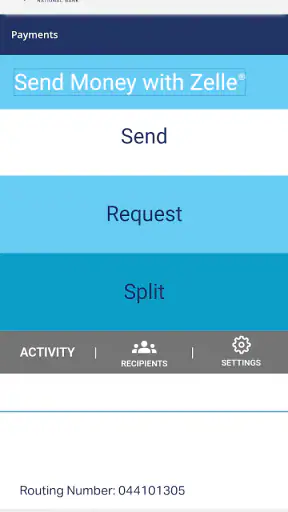
Park National Bank’s mobile app is designed to give customers convenient access to everyday banking services from an Android or iOS device. After signing in, users can typically review account balances and transactions, transfer money between eligible accounts, deposit checks remotely, pay bills, manage debit cards, locate branches or ATMs, and contact the bank. Available features may depend on your account type and region.
Is the Park National Bank app safe to use for mobile banking?
The app is intended to provide secure access to Park National Bank accounts through encrypted connections and account authentication. You should still protect your login credentials, enable biometric sign-in or other security options when available, keep your device updated, and avoid accessing your account over unsecured public Wi-Fi. Park National Bank will never need your password or one-time security code through an unsolicited message.
Can I deposit checks using the Park National Bank mobile app?
If mobile check deposit is available for your account, the app may allow you to photograph the front and back of an endorsed check and submit it for review. Images must be clear, and the check should meet the bank’s eligibility requirements. Deposit limits, processing times, funds availability, and endorsement instructions can vary, so always follow the in-app guidance and retain the original check until the deposit is confirmed.
Does the Park National Bank app charge fees for its services?
Downloading and using a banking app is commonly free, but certain banking activities may involve fees depending on your account agreement. Possible charges can relate to overdrafts, expedited transfers, wire services, returned payments, or other optional products rather than the app itself. Before completing a transaction, review the displayed details and consult Park National Bank’s current fee schedule for accurate information.
What should I do if I cannot log in or notice suspicious activity?
If you cannot access the app, first check your internet connection, confirm that you are using the latest version, and use the official password-reset or account-recovery option. Do not repeatedly guess credentials if your account may lock. If you see an unfamiliar transaction, lost your phone, or suspect fraud, contact Park National Bank through an official website, statement, branch, or verified phone number immediately.











