

OneBlinc - Financial tools
4.6FinanceUpdated October 2, 2026
Screenshots
Pros
- Builds credit history through eligible activity and timely repayments.
- Provides budgeting tools to help track spending and manage cash flow.
- Offers flexible repayment options for qualifying users.
- Useful financial alerts can help avoid missed payments and overdrafts.
- Application process is convenient and handled entirely from a mobile device.
Cons
- Approval
- limits
- and available features depend on personal eligibility.
- Some services may include membership fees
- interest
- or other charges.
- Credit-building results are not guaranteed and may take time to appear.
- Cash advances can encourage borrowing beyond your regular budget.
- Availability and terms may vary by location and change over time.
 Analysis By Mobexer
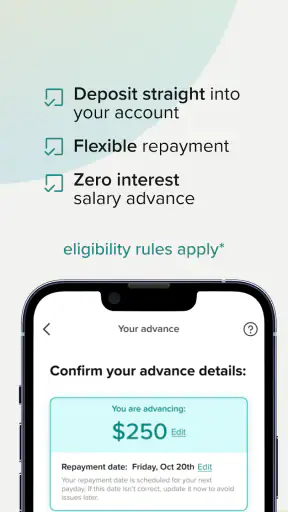
When an unexpected bill arrives before payday, the useful question is not simply whether an app can move money quickly. I want to know how clearly it explains the process, whether it fits the way I already manage my bank account, and whether the convenience is worth making it part of my financial routine. OneBlinc is a finance app from OneBlinc built around access to earned wages, with the option to send up to 250 dollars to a linked account. I see it as a focused cash-flow tool rather than a complete budgeting or banking replacement.
That distinction matters. I would consider it when the problem is timing: money has already been earned, but the regular payment date has not arrived. I would not approach it as a long-term answer to spending more than I can afford. The app is free to download, carries an Everyone content rating, and has reached more than 100 thousand installs. Those details make it approachable, but they do not remove the need to read each screen carefully before requesting money.
How I would decide whether OneBlinc fits
My first decision criterion is the source of the money. This is most relevant to someone who receives wages and wants earlier access through a linked account. If I were looking for a traditional personal loan, a credit card, a savings account, or a tool for tracking every category of spending, I would start elsewhere. OneBlinc has a narrower job, and that narrowness is part of its appeal.
The second criterion is urgency. A person facing a small gap between an automatic payment and payday may value a direct route more than a large collection of financial features. In that situation, I would rather use a focused interface than sort through investment tools, loan comparisons, or a full banking dashboard. On the other hand, if the expense can wait, I would first consider moving the payment date, using existing savings, or adjusting the budget. Early wage access should solve a timing problem, not disguise a recurring shortfall.
I also pay attention to setup friction. The central workflow depends on linking an account, so I would have the correct account details ready and check that the destination is the one I actually want to use. I would not rush through identity, employment, or account prompts simply because I needed money quickly. Financial apps deserve the same care as online banking, especially when a request involves transferring funds.
Another practical test is repeatability. One emergency request can be manageable; relying on the same solution every pay cycle is a different situation. Before using it regularly, I would write down the amount requested, when I expect the normal wages to arrive, and how the next few days of bills will look. That small pause helps separate a one-off bridge from a pattern that needs a broader budget change.
The everyday situation where it makes sense
Imagine I have worked the relevant hours, but a utility payment is scheduled before my normal payday. I could use OneBlinc to seek access to part of those wages through my linked account, then leave the rest of my paycheck untouched for rent, groceries, and other fixed obligations. In that scenario, the value is not unlimited borrowing; it is reducing the gap between work completed and the date the employer’s usual payroll process makes the money available.
I would still check the amount twice before confirming. Requesting the maximum simply because it is available would be poor practice if the bill only needs a smaller sum. A useful habit is to request the narrowest amount that solves the immediate problem and then return to the normal budget as soon as possible. That approach makes the app a short bridge instead of an extra source of spending room.
What I noticed about the app’s position in finance
OneBlinc is listed as a free app, which lowers the initial barrier to trying it. Its current release is version 7.12.0, and it supports devices running Android 7.0 or later. I would still treat “free” as a download and access statement, not as a reason to skip the transaction details. The important financial question is always what the specific request involves, how the transfer works, and what I will owe or need to manage afterward.
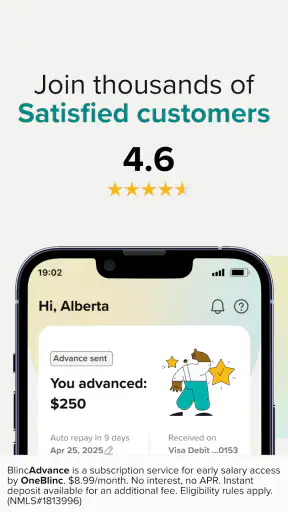
The app’s average rating is 4.6 from roughly 4.8 thousand ratings, with around 672 written reviews. I find that encouraging as a sign that many people have found the experience useful, but ratings cannot predict whether my employer, account arrangement, or cash-flow situation will fit the workflow. I use them as a reason to investigate, not as a substitute for reading the in-app terms.
Where OneBlinc wins against familiar alternatives
Its clearest strength is focus. A normal bank app may show my balance, pending transactions, deposits, and transfers, but it may not be designed around accessing wages before the ordinary payday. A budgeting app can tell me that a bill is coming, yet it cannot necessarily address the timing gap. A credit card can cover an expense, but that changes the problem into revolving credit management. OneBlinc sits in a different part of the decision: it targets earned-income timing rather than general borrowing or financial tracking.
That focus can make the mental process simpler. Instead of opening a credit application or rearranging several accounts, I can think in a short sequence: identify the immediate need, connect the appropriate account, review the amount, and decide whether the request is sensible. I appreciate that kind of narrow workflow when the situation is urgent, because too many unrelated features can make a financial decision harder rather than easier.
Another advantage is that the intended destination is a linked account. For someone who already uses one main account for bills, receiving the money there may reduce an extra transfer step. My practical tip would be to link the account that actually handles the expense, not an account that makes the balance look temporarily larger. Keeping the money close to the bill can make it easier to see what the advance is for.
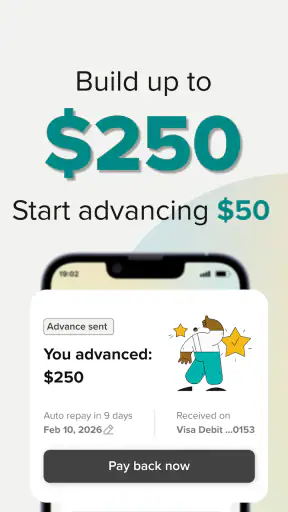
The wage-access angle is also more disciplined than treating an emergency as open-ended credit. The stated ceiling is up to 250 dollars, so the product is positioned for a limited shortfall rather than a major purchase. That limit can be helpful: it naturally discourages using the app as a replacement for a full emergency fund or a large loan. At the same time, it means I would not choose it for rent arrears, substantial medical costs, or any obligation that requires more room than a small bridge can provide.
Small habits that make the workflow safer
I would use the app alongside a simple note on my phone. Before requesting anything, I would record the bill, the amount needed, the expected payday, and the account receiving the funds. Afterward, I would mark the request against the upcoming income. This is not a feature claim about the app; it is a practical safeguard that prevents a quick transfer from disappearing into general spending.
I would also review the confirmation screen slowly, especially the destination and amount. A rushed request can create a second problem if money lands in the wrong account or if I ask for more than necessary. Screenshots or notes may help me remember the transaction, but I would avoid storing sensitive financial information in an insecure place.
Finally, I would treat repeated use as a signal to investigate the underlying budget. If the same bill creates a gap every month, the better solution may be changing the bill date, building a small cash buffer, speaking with the employer’s payroll team, or using a conventional account feature that matches the pattern. OneBlinc is strongest when the timing issue is occasional and specific.
Where another type of financial tool may fit better
A standard bank account is the better starting point when I need deposits, bill payment, card spending, and a stable place to keep savings. OneBlinc does not replace the everyday functions I expect from a bank. I would use my bank for the main financial structure and consider this app only for the wage-access gap that the bank’s normal schedule leaves behind.
A budgeting app may be more appropriate when the real issue is visibility. If I am unsure where my paycheck goes, I need spending categories, upcoming-bill planning, and a longer view of cash flow. Accessing wages earlier can relieve today’s pressure, but it will not explain why the pressure keeps returning. In that case, budgeting and a realistic spending plan are more valuable than another transfer option.
A credit card may fit a purchase that must be made now and can be repaid predictably under terms I already understand. That does not automatically make a card cheaper or safer; it simply gives it a different role. I would compare the repayment structure, consequences of carrying a balance, and my own history with credit before choosing it. OneBlinc may be preferable for a small earned-wage timing issue, while a card may be more familiar for a planned purchase that falls within an established repayment plan.
An employer’s own payroll or earned-wage program could also be a better fit if it integrates directly with workplace records and provides a process I already understand. I would compare the steps, timing, account destination, and any applicable conditions rather than assuming that the most convenient-looking button is the best route. The right choice depends on how closely the option matches my employment and banking setup.
For a genuine emergency fund problem, neither early wage access nor a credit product should be my only plan. I would look at payment arrangements, trusted support, existing savings, and professional financial guidance where appropriate. The small limit makes OneBlinc unsuitable for expenses that need a large, sustained solution. That is not a flaw in a focused app; it is a boundary I would respect.
Questions I would resolve before the first request
I would first ask whether my wages and linked account are eligible for the exact workflow shown in the app. The answer affects whether setup will be smooth, so I would not assume that every worker or account combination behaves identically. I would follow the prompts carefully and stop if the information requested does not match my circumstances.
I would then check when the money should become usable and how the normal wage payment will interact with the request. A transfer that arrives after the bill’s deadline does not solve the problem, while a request that leaves the next paycheck too tight can move the stress rather than remove it. Timing is just as important as the headline amount.
I would also look for the complete cost and repayment explanation inside the request flow. The app is free to download, but that phrase alone is not enough to evaluate a financial transaction. I would read every disclosure attached to the specific action, including anything about optional services, repayment, or account effects, before pressing confirm.
Lastly, I would make sure I know how to stop using it. If my situation improves, I would not keep requesting early access merely because the option is available. A good financial tool should remain under my control, and that means having a clear reason for each use rather than allowing convenience to become automatic.
The cost of switching from an existing routine
Switching to OneBlinc is not only a download decision. I would need to create the appropriate account relationship, connect a destination, learn the request flow, and remember to account for the upcoming wage payment. That is a modest amount of work for an urgent need, but it is still more than opening my familiar bank app and checking a balance.
The switching cost is lowest when I already have a clear main account and only need a temporary bridge. In that case, the linked-account model can fit naturally into my routine. It is higher when my finances are spread across several accounts, when payroll information is complicated, or when I need a complete record of spending rather than a single access feature.
I would also avoid switching during the most stressful minute of an emergency if I could prepare earlier. Installing the app, reviewing the setup screens, and understanding the destination account before a bill is due gives me time to notice a mismatch. The best moment to learn a financial app is before I urgently depend on it.
For an occasional user, that preparation may be worthwhile because the product addresses a specific gap. For someone who already has reliable savings or a well-managed bank facility, switching may add another account connection without much benefit. In that case, the familiar option may be better simply because it is already understood and integrated into the household budget.
My biggest trade-off is convenience versus discipline. Early access can prevent a late payment or reduce the need to use a more expensive form of credit, but it can also make an income shortage feel less visible. I would only call the switch successful if it solves the immediate timing issue without weakening the next pay cycle.
My recommendation for the right kind of user
I recommend OneBlinc to a worker who occasionally needs a modest amount of earned wages before the regular payday, has a suitable linked account, and is willing to review the transaction carefully. The app’s focused purpose, free availability, Everyone rating, and established presence on Android make it easy to consider. Its strongest use is a small, clearly defined bridge tied to a known upcoming payment.
I would not recommend making it the center of a financial plan. If I needed ongoing borrowing, detailed budgeting, a bank account, investment tools, or a solution for a large expense, I would choose a product designed for that job. I would also pause if the same request would be necessary every pay period, because the pattern suggests that the underlying income-and-expense balance needs attention.
OneBlinc was released on February 18, 2025, and the current version is 7.12.0, so I would keep the app updated on a compatible device and review the current screens each time I use it. The version details are useful for deciding whether an older Android phone can run it, but they do not change the central judgment: this is a targeted finance tool, not a universal money manager.
My final view is cautiously positive. I like the idea of matching a small advance to a real wage-timing problem, and I would choose that route before turning a short gap into broader credit if the request terms fit my situation. But I would use it with a written amount, a known bill, and a clear repayment expectation. If those three things are missing, I would step back and look for a slower, more sustainable alternative.
FAQ
What is OneBlinc, and what financial tools does it offer?
OneBlinc is a financial services app designed to help eligible users manage short-term cash needs and everyday money more conveniently. Depending on your eligibility and location, its tools may include access to a membership program, cash advances, a spending account or card, budgeting features, and other financial resources. Available products, limits, fees, and terms can vary, so review the details shown in the app before accepting any offer.
Who can use OneBlinc, and what information is required to sign up?
OneBlinc is generally intended for users who meet its identity, age, residency, income, and account-verification requirements. During registration, the app may request personal information, employment or income details, and permission to connect a bank account so it can evaluate eligibility and provide its services. Approval is not guaranteed, and requirements may change. Always check the current eligibility rules and privacy disclosures before submitting sensitive information.
Does OneBlinc charge fees or interest for its financial services?
The cost of using OneBlinc depends on the specific product and membership option selected. Some services may involve a recurring membership fee, optional express-transfer charges, card-related costs, or other fees, while a particular advance may not use traditional interest in the same way as a loan. Carefully read the fee schedule, repayment terms, renewal conditions, and disclosures presented in the app before confirming a transaction.
How do OneBlinc cash advances and repayments work?
If you qualify for a OneBlinc cash advance, the app normally displays the available amount, delivery speed, applicable fees, and scheduled repayment date before you accept it. Funds may be sent to a linked bank account or another supported destination, while repayment is typically collected automatically from the connected account on the stated date. Make sure sufficient funds are available and contact support promptly if repayment problems arise.
Is OneBlinc safe to use, and should I connect my bank account?
OneBlinc may use encryption, identity verification, and secure account-linking technology to protect information, but no online financial service can eliminate every security risk. Connecting a bank account may be necessary for eligibility, deposits, or repayments, so only use the official app and verify its permissions carefully. Read the privacy policy, enable device security, monitor account activity, and never share your login codes with anyone.











