

Navy Federal Credit Union
3.7FinanceUpdated October 5, 2026
Screenshots
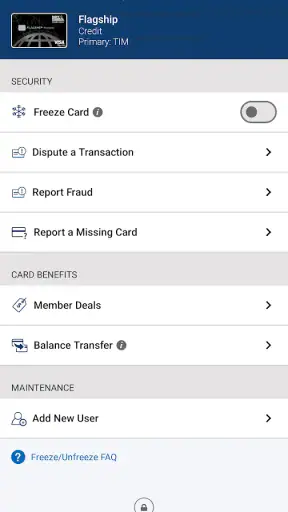
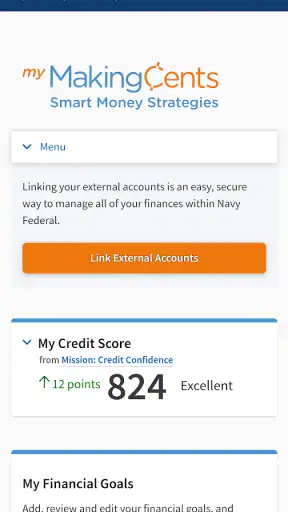
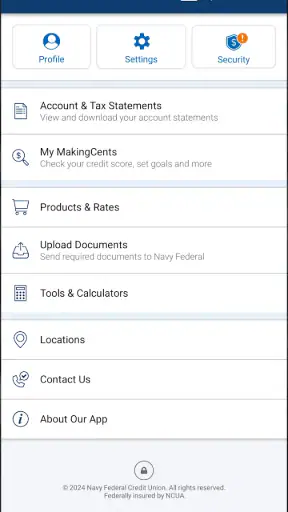
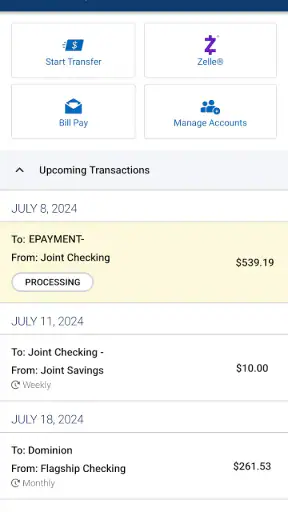
Pros
- No monthly maintenance fees on many checking accounts.
- Strong mobile banking tools for transfers
- deposits
- and bill payments.
- Competitive rates on savings accounts
- certificates
- and loans.
- Access to a large network of fee-free ATMs.
- Helpful benefits and products tailored to military families.
Cons
- Membership eligibility is limited to military-affiliated applicants.
- Some features may require additional verification or documentation.
- Branch availability is limited outside military communities.
- Certain services may involve fees or account-specific requirements.
- App performance and features can vary after updates.
 Analysis By Mobexer
Managing money from a phone is most useful when the app helps me finish a real task without making me search through menus or second-guess every screen. Navy Federal Credit Union is a free finance app from Navy Federal, built around the credit union’s member relationship rather than acting like a general-purpose budgeting tool. I found it most convincing for people who already use Navy Federal for their everyday banking and want a practical mobile route to routine account management.
The app has been available since July 29, 2011, and its long presence is reflected in its broad reach: it has passed ten million installs on Android. Its average rating sits at 3.7 from roughly one hundred ten thousand ratings, with about forty-three thousand written reviews. Those numbers suggest a familiar pattern for a banking app: many members depend on it, while others judge it harshly when a login, transfer, or account screen does not behave as expected.
What to expect before you begin
The first thing to understand is what this app is not. It is not a neutral comparison service for banks, a standalone investment dashboard, or a replacement for a dedicated spending planner. The experience makes the most sense when Navy Federal is already your financial institution. In that situation, the app can put your account information and everyday banking actions in one place instead of making you rely on a browser each time.
Navy Federal presents the service with the message “Our Members Are the Mission,” and that member-focused identity is important to the way I evaluate it. The value is less about flashy financial education and more about access to an existing credit union relationship. If you are deciding whether to join Navy Federal solely because of a mobile app, I would look at the wider credit union relationship first. If you are already a member, the app is much easier to justify.
For Android users, the current version is 2026.8.1 and the minimum operating system is Android 11. That requirement is worth checking before installing, especially if you keep an older phone for banking or use a device that no longer receives regular system updates. On a compatible phone, the app is rated for Everyone and costs nothing to download, which removes the usual price barrier for trying it.
My realistic expectation would be simple: install it, sign in securely, confirm that the displayed accounts are the ones I expect, and complete one small banking task. I would not begin by trying to reorganize my entire financial life. A first successful session should be something concrete, such as checking whether a recent purchase has posted or confirming that available funds look right before paying a bill.
Who will get the most from it
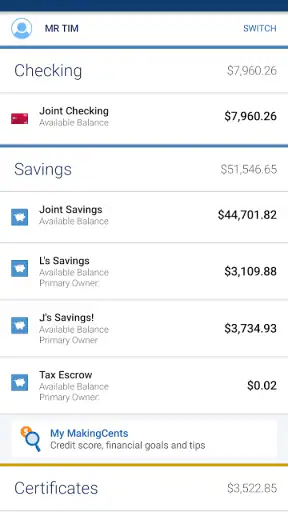
The strongest match is a Navy Federal member who checks balances frequently, moves money between accounts, monitors activity, or wants a phone-based alternative to visiting a branch or opening a desktop browser. It is also useful for someone who prefers seeing their credit union accounts in the institution’s own app rather than connecting them to a separate financial aggregator.
I would be more cautious if you are looking for detailed household budgeting, broad account aggregation across many banks, or an app that explains every financial decision in depth. A dedicated budgeting service may offer better category analysis, while a bank-neutral platform may be more convenient if your money is spread across several institutions. Those alternatives can complement this app, but they do not replace the direct access that a credit union app is meant to provide.
Setting up the first session
I recommend installing it when you have a few uninterrupted minutes and access to the sign-in details you normally use for Navy Federal. Banking setup is not the right moment to rush while standing in a checkout line. Use a private connection you trust, keep your phone’s operating system current, and avoid treating a successful installation as proof that the account is ready until you have actually signed in and reviewed the account screen.
After opening the app, I would take a slow look at every prompt rather than tapping through automatically. Confirm that the developer shown for the app is Navy Federal, then check the app name and version in the store before entering sensitive information. This small habit matters because financial apps deserve more care than ordinary entertainment downloads, even when the app itself is free.
The most reassuring first check is whether the account information shown after sign-in matches what you expect. Look at the account names, balances, and recent activity without immediately starting a transfer. If something looks unfamiliar, stop there and resolve the question through Navy Federal’s official support channels instead of trying random sign-ins or repeatedly submitting forms.
I also suggest deciding in advance what you want from the first session. “I want to see whether yesterday’s card purchase posted” is a better starting goal than “I want to learn the whole app.” A narrow goal makes it easier to identify whether the app is working for you and prevents a crowded financial dashboard from feeling more complicated than it really is.
Making the first useful check
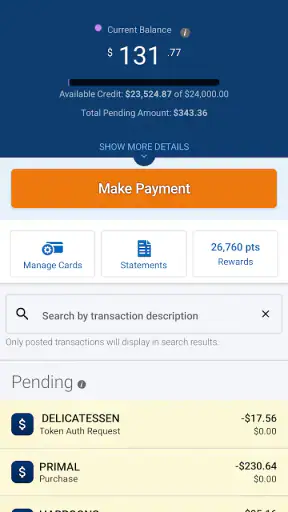
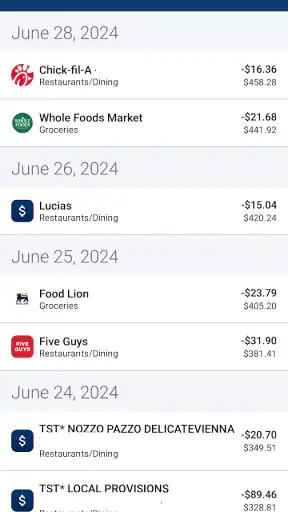
My preferred first action would be reviewing recent account activity. It is low risk, immediately useful, and gives you a chance to learn how the app presents pending or completed activity before money needs to move. Check the transaction description, amount, and date carefully. If a purchase is still pending, I would avoid assuming that the final account balance will be identical to the temporary entry.
This is one of the app’s most practical everyday roles. Imagine buying groceries on the way home, then opening the app later to decide whether another automatic payment can safely leave the account. I would use the activity view and available balance as a snapshot, not as an invitation to spend down to the last dollar. Transactions can take time to settle, and a mobile screen cannot remove that underlying timing issue.
Once the account view feels familiar, the next meaningful action can be a routine payment or a transfer that you already understand. I would not use the first session to experiment with an unfamiliar recipient or an urgent, high-value movement of money. Start with a known workflow, review the destination and amount twice, and save the confirmation screen or reference details when the app presents them.
That cautious sequence is not a criticism of Navy Federal specifically. It is simply good mobile banking practice. The advantage of doing it inside the official Navy Federal app is that you are working from the same credit union relationship rather than copying information between unrelated services. The trade-off is that the app’s usefulness depends heavily on your comfort with Navy Federal’s own account structure and terminology.
Small habits that make the app easier to use
- Use the activity screen as a daily checkpoint: checking recent entries before paying another bill can reveal whether a purchase has posted or is still in progress.
- Separate checking from planning: use Navy Federal for direct account actions, but keep a dedicated budget method if you need long-term category targets or a household spending plan.
- Review before confirming: for transfers or payments, pause at the final review screen and compare the amount, account, and timing with your intention.
- Keep a browser fallback: if the app is unavailable or a screen feels cramped, the traditional web route may be more comfortable for a complex task.
The second habit is especially important. Many people expect a bank app to explain where their money went over an entire month, but direct banking access and financial planning are different jobs. Navy Federal can be the reliable place to verify what happened in an account, while a separate spreadsheet or budgeting tool may be better for deciding what should happen next.
Where new users may hesitate
Banking apps often create confusion around the difference between a balance, available funds, pending activity, and a completed transaction. I would not treat those labels as interchangeable. Before making a payment based on what you see, give yourself time to understand which figure reflects money that is immediately usable and which entries are still moving through the system.
Another common point of friction is assuming that every action should be visible in the same place. A transaction history, a payment workflow, and an account overview may each show different details because they serve different purposes. If you cannot find something, I would return to the account associated with the action and look for the relevant activity or confirmation rather than repeatedly pressing the same button.
Login trouble can also feel more serious in a finance app than in other categories. A failed sign-in does not automatically mean that money or account data has changed. I would stop after a reasonable attempt, verify that the credentials and device are correct, and use Navy Federal’s official help route. Repeated guessing is more likely to create additional frustration than to solve the original problem.
Notifications deserve a thoughtful approach as well. I would enable only the alerts that help me notice important account activity and avoid turning the phone into a stream of low-value reminders. The best notification is one that prompts a useful check; too many alerts can make genuine account activity easier to overlook.
Some users may also find the app less comfortable for complicated work on a small screen. A phone is excellent for a quick balance check or a familiar action, but a desktop browser can be easier when comparing several accounts, reading a long confirmation, or reviewing a more involved financial decision. I see the mobile app as a convenient access point, not a reason to abandon every other way of managing a credit union account.
How it compares with usual alternatives
Compared with visiting a branch, the app is faster for routine checks and does not require planning around opening hours. Compared with a mobile browser, a dedicated app usually feels more direct because it is designed around the Navy Federal relationship instead of a general web page. That convenience matters when I only need to verify activity before leaving home.
Compared with a budgeting app, however, the priorities are different. A budgeting service may be better at combining accounts from multiple institutions, building categories, and showing spending trends. Navy Federal is the better choice when the important question is what is happening inside your Navy Federal accounts and what direct action you can take there.
Compared with another bank’s app, the deciding factor is not simply interface preference. If your accounts are held at Navy Federal, using its own app avoids making a third-party service the middle layer for basic account access. If you do not have a Navy Federal relationship, there is little reason to install this app merely to browse it; a general finance tool would probably serve that purpose better.
What to do after the first success
After confirming a balance or reviewing an activity entry, I would create a repeatable routine instead of exploring every option at once. For example, check the app before a major scheduled payment, review unfamiliar transactions promptly, and use the confirmation details from completed actions when you need to reconcile your records. This turns the app from something you installed into a dependable part of your financial habits.
If you share financial responsibilities with someone else, agree on which person checks activity and how you will discuss unusual entries. The app can show account information, but it cannot replace a clear household process. A simple weekly review may be more useful than opening it constantly without a specific question in mind.
It is also worth keeping expectations realistic about updates. Navy Federal has continued to maintain the Android app, and the current release is 2026.8.1, but an update can change the location or appearance of familiar controls. When that happens, I would first confirm that the account information is correct, then relearn the workflow from the screen labels rather than assuming a missing button means the underlying service has disappeared.
The app’s free price and Everyone content rating make it easy to recommend as a low-risk download for an eligible member, but “free” does not mean that every financial task is automatically simple. The real test is whether the app lets you complete your normal Navy Federal tasks with enough clarity and confidence. For me, that means accurate account awareness, careful confirmation, and a backup plan for anything unusually complex.
My honest recommendation is straightforward: if you already bank with Navy Federal and want a direct mobile companion for everyday account management, Navy Federal Credit Union is worth trying. I would begin with a balance and activity check, then move to one familiar payment or transfer only after the account view makes sense. If you need advanced budgeting, multi-bank organization, or a more spacious workspace, pair it with another tool or use the web experience instead of expecting this app to do every financial job.
For a first-time user, the path to success is reassuringly small: install the official app on a compatible device, sign in carefully, verify the account information, and complete one routine check. That is enough to judge its everyday value. In my experience, the app is strongest when it stays close to that purpose—giving Navy Federal members a practical way to see and manage their credit union accounts wherever they happen to be.
FAQ
What is Navy Federal Credit Union, and who can join?
Navy Federal Credit Union is a member-owned financial institution offering checking and savings accounts, credit cards, loans, mortgages, and other banking services. Membership is generally available to active-duty military personnel, veterans, Department of Defense employees, and qualifying family members. Eligibility requirements should be reviewed before applying, because not every applicant will qualify solely based on interest in the app.
What can I do with the Navy Federal Credit Union mobile app?
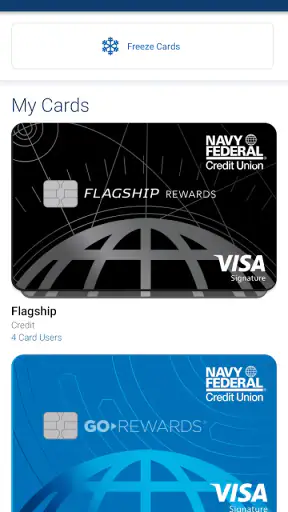
The Navy Federal mobile app provides access to many everyday banking tools from an Android or iOS device. After signing in, members can typically check balances, review transactions, transfer money, deposit eligible checks, pay bills, manage cards, locate branches or ATMs, and apply for selected products. Available features may vary depending on account type, device, region, and current Navy Federal policies.
Is the Navy Federal Credit Union app safe to use?
The app is designed to provide secure access to Navy Federal accounts using standard banking protections, such as encrypted connections, login credentials, device security features, and optional biometric authentication on compatible devices. However, no app eliminates every risk. Download it only from an official app store, keep your operating system updated, avoid public Wi-Fi for sensitive transactions, and never share verification codes or passwords.
Are there fees for using Navy Federal’s mobile banking features?
Downloading and using the Navy Federal mobile app is generally not the same as paying for a separate subscription, but certain banking services may involve fees or eligibility conditions. Examples can include specific transfer methods, overdrafts, expedited services, loan products, or out-of-network transactions. Before completing an operation, review the displayed terms and Navy Federal’s current fee schedule, since charges can change.
What should I do if I cannot log in or the app is not working?
If the app will not open or you cannot sign in, first check your internet connection, update the application, restart your device, and confirm that your login information is entered correctly. Avoid repeatedly guessing passwords, as security controls may temporarily restrict access. Use Navy Federal’s official recovery or support options, and contact the credit union directly through verified channels rather than links in unexpected messages.











