

myEquifax
4.6FinanceUpdated October 5, 2026
Screenshots
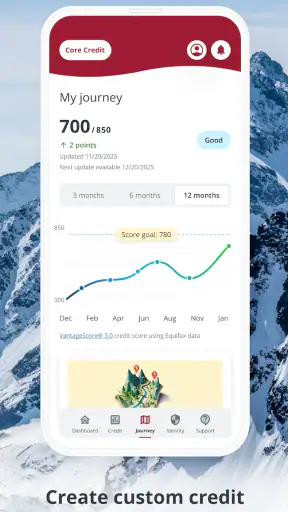
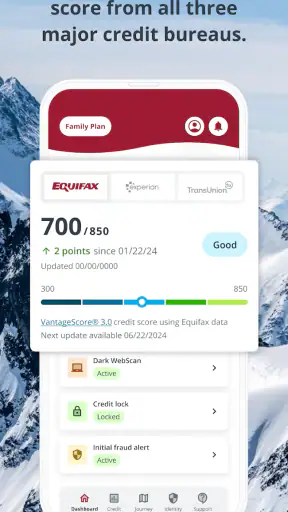
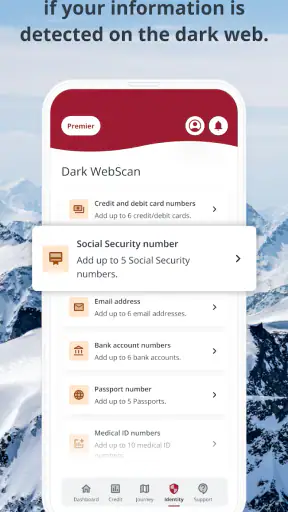
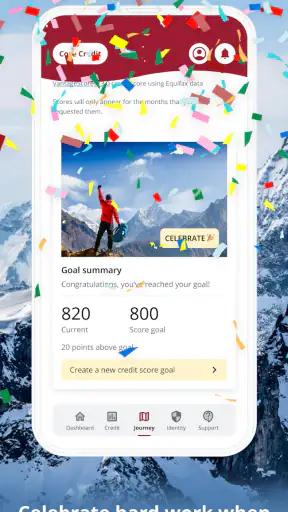
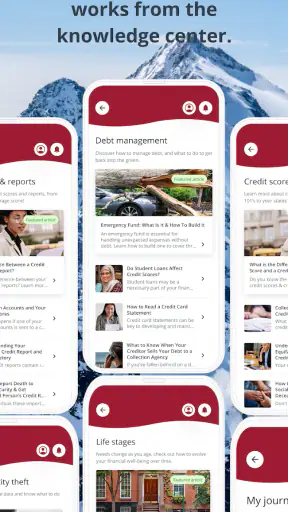
Pros
- Free access to your Equifax credit score and report details.
- Credit monitoring alerts help spot changes and possible identity theft.
- Dispute options make it easier to report inaccurate credit information.
- Secure login and identity verification protect sensitive account data.
- Useful tools explain credit factors and suggest ways to improve your score.
Cons
- Some features require a paid Equifax subscription or separate service.
- Credit information may not update instantly after account activity.
- Identity verification can be frustrating if your details are not matched.
- The app may promote Equifax products and monitoring upgrades frequently.
- Availability and features can vary by country and account type.
 Analysis By Mobexer
I approached myEquifax as someone trying to make sense of a credit situation without turning it into a full-time project. It is a free finance app from Equifax Incorporated, and its basic purpose is clear: help you start and follow your credit journey from a mobile device. That makes it most appealing when you want a more direct way to check your credit information, understand what you are seeing, and keep an eye on changes instead of relying only on occasional paperwork or a general budgeting app.
My first impression is that the app is aimed at reducing the distance between a person and their Equifax credit information. The wording is simple, but the subject itself is not. Credit reports can contain unfamiliar account names, dates, balances, and status labels, so the value here is less about entertainment or constant interaction and more about having a focused place to review an important part of your financial identity.
The app carries a 4.6 average from around ten thousand ratings, with close to a thousand written reviews, and has passed half a million installs. Those figures suggest that it has found a practical audience, although popularity alone does not make a credit app suitable for every situation. I would judge it mainly by how well it supports a careful workflow: open the app, identify what needs attention, understand the next step, and avoid making a rushed decision based on one screen.
From a credit concern to a clearer next step
Starting with the right expectation
The best starting condition for myEquifax is a specific question. You might be preparing to apply for housing, reviewing your finances after paying down a card, checking whether an old account is still appearing, or simply trying to become more familiar with your credit profile. Entering with one of those goals makes the experience more useful because you can compare what you see with the reason you opened the app.
I would not treat it as a replacement for a complete personal finance system. A budgeting app is usually better for categorizing spending, planning bills, and watching cash flow. A bank app is the natural place to manage transactions. myEquifax belongs in a different part of the process: understanding credit information associated with Equifax and using that information as a checkpoint in broader financial planning.
That distinction matters in everyday use. Imagine noticing that a future rental application may involve a credit review. Instead of guessing whether your credit profile is in order, you can use the app as one step in a preparation routine. I would open it early, review the information calmly, make notes about anything unfamiliar, and leave enough time to investigate rather than waiting until an application is already urgent.
Moving through the first review
The first useful habit is to read before reacting. Credit information can look alarming when a user focuses on a single balance or status without considering the surrounding context. I recommend looking for the account or item that prompted your concern, then checking the related details carefully. The goal is not to chase a number from one visit, but to understand what the entry represents and whether it matches your own records.
This is where a mobile app can be convenient. You can review your credit information when you have a quiet moment, rather than needing to gather every document before starting. I found that the smaller screen encourages a narrower task: inspect one issue, record what seems important, and return later if the question requires more research. That can be healthier than opening a large financial dashboard and trying to solve everything at once.
A useful workflow is to keep a simple offline note with the date of your review, the account or item you examined, and the question you still need to answer. I would not copy sensitive information into an unsecured note, but a short reminder can prevent repeated searching. This is a non-obvious advantage of using the app deliberately: it becomes a starting point for organized follow-up instead of a place where you repeatedly look at the same screen without deciding what to do.
Understanding the handoff between information and action
myEquifax can help you see information, but the next action may happen somewhere else. If an account looks unfamiliar, you may need to compare it with statements, contact the relevant company, or follow the appropriate dispute process. If the information appears correct but your financial position needs improvement, the next step may involve changing payment habits, reducing balances, or speaking with a qualified adviser. The app is useful at the beginning of those handoffs because it gives you something concrete to investigate.
I consider this separation a strength when used properly. It prevents the common mistake of assuming that viewing a credit profile automatically fixes a problem. At the same time, it can feel like friction if you expect one app to explain every situation and complete every action. A person who wants an all-in-one money manager may prefer a broader financial service, while someone focused specifically on Equifax credit information may appreciate the narrower purpose.
When I review a questionable entry, I would take screenshots only when appropriate and store them carefully, avoiding unnecessary exposure of personal details. I would also compare the information with my own documents before contacting anyone. That extra pause is important because a familiar-looking company name, an old account, or a balance that changed recently can be misunderstood when viewed without context.
Using the app as a repeatable check-in
The strongest everyday use is not a single dramatic inspection. It is a repeatable check-in that fits into a larger routine. For example, after reviewing monthly bills, I might open myEquifax and look for information connected to a financial change I already made. If I recently paid down an account, I would avoid expecting an immediate result and instead treat the app as a place to check again later, while remembering that different financial records may update on different schedules.
This approach also helps separate action from anxiety. Credit monitoring can encourage people to check repeatedly without knowing what they are looking for. I prefer setting a purpose for each visit: verify an account, review a change, prepare for a financial application, or learn the meaning of an unfamiliar entry. If there is no clear reason to open the app, a broader budgeting task may be more valuable that day.
Another practical tip is to review credit information before making a major application, not only after a rejection or surprise. Early review gives you time to correct your own records, gather supporting paperwork, and ask questions. It does not guarantee a particular lending or housing outcome, but it improves your preparation and reduces the chance of discovering an issue at the worst possible moment.
Where the result becomes useful
The outcome I want from myEquifax is not a feeling of certainty based on a single visit. It is a clearer answer to a practical question: does my Equifax credit information look consistent with what I know, and do I have a sensible next step? If the answer is yes, I can continue with my broader plan. If the answer is no, I have a starting point for gathering documents and seeking clarification.
That makes the app particularly suitable for people who are beginning to learn about credit. The store age rating is Everyone, and the interface is positioned for a general audience rather than finance professionals. Still, an Everyone rating does not mean every credit decision is simple. Younger users, first-time borrowers, and people rebuilding their finances may benefit from the app as an observation tool, but they should not interpret a displayed result as personal financial advice.
For someone preparing to rent a home, the workflow might look like this: identify the reason for checking, review the relevant credit information, compare unfamiliar details with personal records, write down questions, and then contact the appropriate organization if something needs clarification. The final outcome is better preparation, not a promise that an application will be approved. That distinction is worth keeping visible throughout the process.
What makes it different from usual alternatives
Compared with a general banking app, myEquifax is more focused on credit information rather than daily account activity. A banking app may show your current balance and transactions very clearly, but it usually is not the place I would go to investigate Equifax-specific credit details. Compared with a budgeting app, myEquifax offers less value for planning spending categories or forecasting bills, but it is more relevant when the question concerns your credit profile.
There is also a difference between using a dedicated credit app and relying on a third-party financial dashboard. A third-party service may combine information from several institutions, which can be convenient if you want a broad overview. The trade-off is that a narrower Equifax-focused app may be easier to understand when your concern is specifically tied to Equifax information. I would choose based on the question: broad money management calls for a broader tool, while an Equifax-centered review calls for this app.
I also like the fact that the app is free. That removes a common barrier for someone who is only beginning to investigate their credit situation. However, free access should not encourage careless checking or sharing. I would still use a strong device passcode, install the app only from a trusted store, and avoid reviewing sensitive financial information on a public screen whenever possible.
Where the workflow breaks down
The main weakness is that credit questions rarely end inside one application. If the information is confusing, the app may be only the first handoff in a longer process. You can identify a concern, but resolving it may require documents, phone calls, correspondence, or patience. Users expecting an instant explanation for every credit outcome may find that gap frustrating.
Another limitation is the risk of overinterpreting what appears on screen. A credit profile is not the same thing as a guaranteed decision from a lender, landlord, or service provider. Different organizations can apply their own criteria, and a person’s wider financial circumstances matter. I would use myEquifax to prepare questions and check consistency, never as a promise about what another organization will decide.
The app is also not the right choice if your primary goal is managing everyday money. If you need to split spending into categories, schedule bills, track investments, or maintain a detailed household budget, a dedicated financial planning tool will probably serve you better. Installing myEquifax will not replace those workflows; it adds a credit-focused checkpoint to them.
People who dislike handling sensitive information on a phone may also prefer a web-based process or paper records. That is a reasonable preference, especially if you share a device or often use your phone in public. The convenience of mobile access has to be balanced with privacy habits, careful sign-in behavior, and the discipline to avoid leaving personal screens visible.
Version, access, and who should use it
The current release is version 1.11.0 and supports devices running Android 8.0 or later. That gives the app a practical reach across many Android phones, including devices that are not recent flagship models. I would still keep the operating system and app updated when possible, particularly for a finance app, because reliable access and basic device security matter more here than visual novelty.
As a free finance app, myEquifax is easy to justify for a person who wants a focused way to begin reviewing credit information connected with Equifax. It is especially useful for first-time credit learners, people preparing for a major application, and users who want a dedicated place to return to when checking whether their records look familiar.
I would skip it if you want a complete financial command center, if you need detailed spending analysis, or if you are looking for guaranteed explanations and instant corrections. In those cases, a budgeting service, bank application, direct creditor contact, or professional guidance may be the better next tool. The right choice depends on whether your starting condition is a credit-information question or a broader money-management problem.
My recommendation after following the full workflow
After looking at the app as a complete journey from concern to outcome, I see myEquifax as a focused first stop rather than a universal financial solution. Its value comes from helping you move from vague worry to a specific item, then from that item to a sensible handoff. The experience is most effective when you bring your own records, ask one question at a time, and accept that some answers require action outside the app.
I would recommend it to a friend who wants to start understanding their Equifax credit information without paying for access to a separate budgeting platform. I would tell that friend to use it calmly, keep private details protected, and record what needs follow-up instead of repeatedly refreshing without a plan. The free price and focused purpose make it approachable, while the limits of credit data mean it should be used as part of a wider financial routine.
In the end, myEquifax is most useful when it turns a credit check into an organized next step. It will not make complicated financial decisions disappear, and it is not designed to replace banking or budgeting tools. But for someone starting a credit journey, the app offers a practical way to inspect information, prepare for important applications, and recognize when the next move belongs with a creditor, a document, or a qualified professional.
FAQ
What is myEquifax, and what can I use it for?
myEquifax is Equifax’s mobile and online service for accessing personal credit information and related account features. After signing in, users may be able to review their Equifax credit report, monitor changes or alerts, manage identity-protection services, and find educational resources. Available features can vary by country, subscription, account type, and the specific Equifax service connected to your login.
Is myEquifax free to download and use?
The myEquifax app may be free to download, but not every feature is necessarily free. Basic account access or legally required credit-report options may be available without charge, while credit monitoring, identity theft protection, additional reports, scores, or premium alerts can require a paid plan. Always check the current pricing, trial terms, renewal conditions, and cancellation policy before subscribing.
What information do I need to create or access a myEquifax account?
To register or verify your identity, myEquifax may request personal details such as your full name, address, date of birth, and government-issued identification information, depending on your location and the service selected. You will also need an email address or username and a secure password. Identity-verification questions or multifactor authentication may be required before access is granted.
How accurate is the credit information shown in myEquifax?
myEquifax displays information maintained by Equifax and supplied by lenders, creditors, and other reporting organizations. Although the service is designed to provide current credit data, errors or outdated entries can occasionally appear. Review your report carefully, especially account balances, payment history, personal details, and inquiries. If something is incorrect, use Equifax’s official dispute process rather than assuming the app will correct it automatically.
Is my personal and financial information safe when using myEquifax?
myEquifax uses account authentication and security measures intended to protect sensitive credit and identity information, but no online service can eliminate every risk. Use the official app or website, create a unique password, enable multifactor authentication when available, and avoid signing in over unsecured public Wi-Fi. Keep your device updated, never share verification codes, and contact Equifax through official channels if you notice suspicious activity.











