

MoodWallet: Money Management
4.3FinanceUpdated October 2, 2026
Screenshots
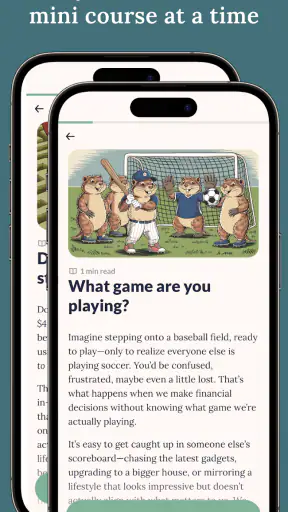
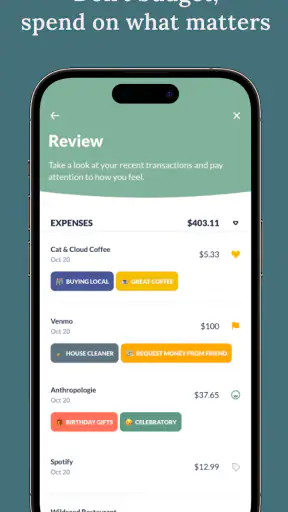
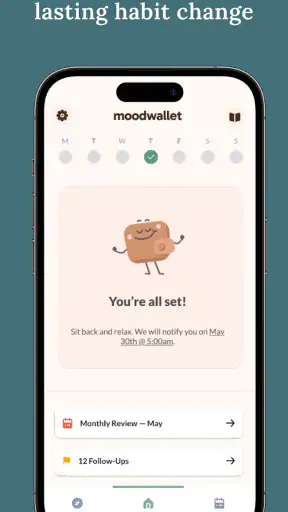
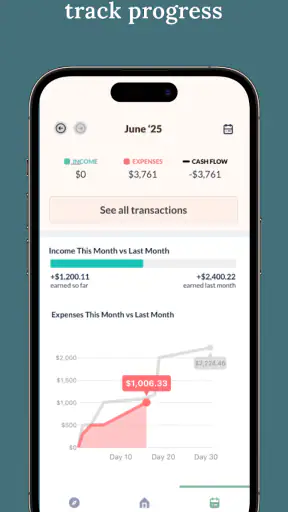
Pros
- Simple interface makes daily money tracking quick and approachable.
- Custom categories help organize spending around personal habits.
- Budget alerts can encourage users to stay within planned limits.
- Useful summaries make it easier to review financial behavior over time.
- Suitable for users who want lightweight expense management on mobile.
Cons
- Some advanced budgeting tools may be limited compared with full finance suites.
- Manual transaction entry can become tedious for frequent purchases.
- The app’s usefulness depends on consistently recording expenses.
- Users may need time to customize categories and budgets effectively.
- Privacy-conscious users should review data handling and account permissions.
 Analysis By Mobexer
Money management tools often fail before the budgeting itself begins. A person downloads an app hoping to feel calmer about spending, then gets stuck wondering what to enter, what the numbers mean, or whether the process will become another daily chore. I approached MoodWallet: Money Management with that exact concern. It is a free finance app from Jomo Labs built around a lighter idea: helping you connect spending with how it feels, rather than forcing you into a detailed budget from the first screen.
That difference matters. Traditional budget apps usually ask you to create categories, assign limits, connect accounts, and maintain a fairly strict routine. MoodWallet takes a more approachable direction for people who want to notice patterns and make better choices without turning every purchase into an accounting exercise. In my experience, its strongest appeal is not advanced financial control. It is the attempt to make spending reflection feel less intimidating.
The app is available to users aged Everyone, is free to download, and has reached over ten thousand installs. Its average rating is 4.3 from more than a hundred ratings, which suggests that the concept connects with a useful group of users while still leaving room for different opinions. Jomo Labs released it on September 13, 2021, and the current version is 2.12.0. The minimum operating system is Android 7.0, so many older Android phones should be able to run it.
What makes MoodWallet different from a normal budget app
The key idea is in the name. Instead of treating money as a series of cold totals, MoodWallet encourages you to consider the emotional side of spending. That can be surprisingly useful because a purchase may be affordable on paper and still leave you feeling regretful, stressed, rushed, or satisfied. A spreadsheet can show the amount; it usually cannot show the reason you made the decision or how you felt afterward.
I would describe it as a reflection tool within the finance category rather than a replacement for a full household accounting system. That distinction is important before you install it. If you need detailed bill scheduling, tax records, shared accounts, investment tracking, or a strict envelope budget, a conventional finance manager will probably serve you better. If your main problem is impulse spending or uncertainty about where your money goes emotionally, this approach is more relevant.
The store summary presents the app as a way to reduce stress and spend better without requiring a budget. I think that promise is most believable when you interpret “without budgeting” as “without building a complicated budget.” You still need to pay attention and record or reflect on your choices. No app can make spending habits change automatically if you never pause long enough to examine them.
Where a first session can become confusing
The most likely sticking point is expectation. Someone accustomed to a banking app may open MoodWallet looking for a live balance, while someone coming from a spreadsheet may expect detailed categories and reports. The app’s purpose is softer and more behavioral. If you approach it as a place to understand your relationship with spending, its design makes more sense. If you approach it as a complete financial ledger, it may feel limited.
Another possible source of friction is deciding how much detail to enter. Recording every tiny purchase can become tedious, especially if you already feel overwhelmed by money. On the other hand, recording only major purchases may hide the small repeated decisions that create stress. I found that the most useful middle ground is to focus on purchases that trigger a noticeable reaction: the item you nearly returned, the treat that genuinely improved your day, or the expense you made while tired and distracted.
This is one of the app’s less obvious strengths. You do not need to turn your entire financial life into a project to learn something from it. A short period of intentional observation can reveal whether your spending is driven by convenience, social pressure, boredom, reward-seeking, or genuine need. That kind of insight is easy to miss in a standard category chart.
Setup checks that prevent unnecessary frustration
Before judging the experience, I recommend starting with a clear goal. Decide whether you want to understand impulse purchases, reduce money-related anxiety, or simply become more aware of emotional triggers. Choosing one purpose keeps the first sessions manageable. If you try to analyze every part of your finances immediately, the app may feel like work rather than support.
It also helps to begin with a small, recent sample instead of trying to reconstruct months of spending. Think back to a handful of purchases that you remember clearly. Ask yourself what was happening before each one, what you expected the purchase to change, and how you felt afterward. This gives the app useful context without creating a large data-entry task on day one.
Keep your first entries honest rather than impressive. There is no benefit in describing a purchase as sensible if you actually bought it to relieve boredom or avoid an uncomfortable decision. The value comes from recognizing the pattern, not from producing a perfect financial record. I would especially avoid using the app while feeling guilty; self-judgment makes reflection less accurate and can turn a helpful exercise into punishment.
Android compatibility is another simple check. MoodWallet requires Android 7.0 or newer, so confirm the device software before assuming an installation problem is caused by the app. If the app installs but behaves oddly, the sensible first steps are ordinary ones: close and reopen it, restart the phone, check available storage, and make sure the operating system is not waiting for a pending update.
Because the app is free to download but includes in-app purchases ranging from $6.99 to $89.99 per item, I would also pay attention to the purchase screen during setup. Read what each optional purchase is for before confirming anything. This is especially important if you are trying to reduce financial stress. A money app should not lead you into an unplanned expense simply because you tapped through a screen quickly.
A workflow that keeps the app useful
My preferred routine is short and selective. I would open MoodWallet after a purchase that feels emotionally significant, rather than setting an unrealistic goal of documenting every transaction. Note the situation while it is still fresh. Was the purchase planned? Were you hungry, rushed, lonely, celebrating, or trying to save time? Then compare the immediate feeling with the feeling later that day or the next morning.
This creates a practical feedback loop. You are not merely asking whether something was “good” or “bad.” You are checking whether the result matched the expectation. A convenience purchase may be worth repeating if it genuinely reduced pressure during a busy day. A cheap impulse purchase may be worth avoiding if it repeatedly produces regret. The amount alone does not tell you which lesson applies.
One useful technique is to separate the trigger from the purchase. For example, if you buy food delivery after a difficult workday, the trigger may be exhaustion rather than hunger. The better solution might not be a strict spending ban. It could be keeping an easier meal available, setting a reminder before the evening rush, or accepting that occasional convenience is part of your real life. MoodWallet is most helpful when it leads to a practical adjustment instead of a vague promise to “be better.”
A second technique is to review patterns at a fixed moment, such as the end of a week. Do not repeatedly reread every entry throughout the day. That can amplify worry and make the app feel like a monitor. A brief review is enough to identify recurring situations. Look for repeated emotional words, similar times of day, or purchases that seemed harmless individually but often followed the same trigger.
A third, less obvious use is decision testing. Before making a nonessential purchase, pause and predict how you will feel afterward. Later, compare the prediction with reality. This turns the app into a way to improve your judgment, not just a diary of past mistakes. Over time, the gap between expectation and outcome becomes more informative than the price tag.
How to recover when your routine breaks
Missing several days does not ruin the process. In fact, trying to catch up by recreating every forgotten purchase can make the app feel burdensome. I would simply restart with the next meaningful purchase. The goal is not a flawless streak; it is a clearer understanding of the decisions that matter to you.
If an entry feels confusing, simplify it. Record the situation and the emotional result first, then add detail only if it helps explain the choice. A short, truthful note is more valuable than a long description written from memory. This is particularly useful after a stressful day, when asking yourself too many questions can become another source of pressure.
If the app appears not to respond, use a calm troubleshooting sequence rather than repeatedly tapping the same control. Leave the screen and return, restart the application, and restart the device if necessary. Check whether other apps are also having trouble. If the problem affects only one screen, avoid deleting local information impulsively; first make sure you understand what might be removed. General recovery steps are safer than experimenting with settings at random.
It is also worth separating a technical interruption from a motivation problem. Sometimes people say an app “stopped working” when the real issue is that the routine became uncomfortable. If opening MoodWallet makes you feel judged, reduce the scope of the exercise instead of abandoning the idea entirely. Track only purchases connected to one goal for a week. If that still feels unpleasant, the method may not suit you right now.
When the app is not the cause of the money stress
MoodWallet can help you notice behavior, but it cannot fix an income shortage, a high-interest debt problem, an unexpected bill, or a financial situation shared with other people. Reflection is valuable, yet it should not be mistaken for a complete solution. If the main challenge is that essential costs exceed available income, changing the emotional framing of purchases will not be enough. You need practical financial information and, when appropriate, advice from a qualified professional.
The same applies to shared household finances. One person’s mood around spending may not explain a partner’s decisions, family obligations, or irregular bills. In that situation, a conventional budgeting tool with clear totals may be the better primary system, while MoodWallet can remain a personal reflection aid. I would not use it as the only source of truth for a household that needs precise coordination.
Privacy and comfort should guide your habits as well. Avoid entering details that you would not want stored on a personal device. Keep reflections general when a purchase involves another person or a sensitive situation. The app is about learning from your choices, not creating a complete personal dossier. That boundary makes the practice easier to sustain and reduces the temptation to overshare.
Who will benefit most from MoodWallet
I think the best audience is someone who understands basic money management but struggles with consistency, impulse decisions, or emotional spending. It can also suit people who find conventional budgets intimidating. A student, a first-time worker, or anyone rebuilding a healthier relationship with purchases may appreciate the gentler starting point.
It is particularly promising for users who have already tried strict rules and repeatedly abandoned them. A rigid limit can create an all-or-nothing cycle: follow the plan perfectly, break it once, then give up. MoodWallet encourages observation instead of perfection, so a setback can become information rather than proof of failure.
It is less suitable for users who want automatic financial administration. If your priority is seeing exact account balances, tracking recurring payments, splitting expenses, or producing detailed reports, choose a dedicated budgeting or banking solution first. MoodWallet should complement that kind of tool only if its reflective approach adds something you genuinely need.
The app may also be a poor match for someone who dislikes journaling or does not want to think about feelings while making financial decisions. Its central idea is not a minor decoration. If you want a purely numerical experience, the emotional angle may feel unnecessary. That is not a defect for the right user, but it is a real trade-off.
My practical verdict after using it
MoodWallet: Money Management is an interesting finance app because it addresses a part of spending that ordinary budgets often overlook: the reason a purchase felt necessary at the time and whether it actually delivered what you wanted. I like that it can be approached in small sessions, without demanding an elaborate financial system from the beginning.
Its limitations are equally clear. It should not be treated as a full replacement for banking tools, detailed budgets, or professional financial guidance. The experience depends on honest participation, and users who expect automatic answers may be disappointed. The free download is inviting, but the available in-app purchases mean I would read each payment prompt carefully before proceeding.
My recommendation is to try it with one focused question rather than your entire financial life. For example: “Why do I keep making late-evening purchases?” Use the app to observe that pattern, test one small change, and review what happened. If the process makes your decisions clearer and less stressful, it has earned a place in your routine. If you need exact financial control or shared household accounting, use a traditional finance manager instead.
Overall, Jomo Labs has created something more thoughtful than a basic spending log, even though it is not designed to do every job a finance app can do. Its real value appears when you use it as a bridge between awareness and action. For people who want to spend better without starting with a complicated budget, that is a worthwhile and approachable place to begin.
FAQ
What is MoodWallet: Money Management used for?
MoodWallet: Money Management is designed to help you organize your personal finances in one place. You can typically use it to record income and expenses, review spending patterns, create budgets, and monitor your financial habits. Its mood-focused approach may also help you connect emotional states with purchasing decisions, making it easier to recognize whether stress, boredom, or other feelings influence your spending.
Is MoodWallet suitable for beginners who have never used a budgeting app?
Yes, MoodWallet can be useful for beginners because the main concept is straightforward: enter your financial activity, categorize transactions, and review the resulting information. New users should still spend a few minutes exploring the settings, categories, recurring transactions, and reports before relying on the app. The quality of your results will depend on entering purchases consistently and accurately.
Does MoodWallet connect directly to bank accounts or credit cards?
Bank and card connectivity can vary depending on the app version, operating system, country, and available financial-service integrations. Before downloading, check the current store listing and the app’s privacy information to confirm whether automatic synchronization is supported. If it does not connect to your accounts, you may need to add transactions manually, which offers more control but requires regular maintenance.
Is my financial information safe when using MoodWallet?
Before adding sensitive financial details, review MoodWallet’s privacy policy, permissions, data-storage practices, and any information about encryption or third-party services. Avoid entering online-banking passwords unless the app clearly explains a secure, reputable connection method. You should also protect the device with a passcode or biometric lock, keep the app updated, and confirm whether backups or cloud synchronization are enabled.
Is MoodWallet: Money Management free to download, and are there in-app purchases?
The download price and available features may differ between Android and iOS, so check the official store page for the latest information. Some budgeting apps provide basic tracking for free while reserving advanced reports, customization, synchronization, or an ad-free experience for a subscription or one-time purchase. Read the payment terms carefully and verify whether any trial automatically renews before confirming it.











