

Money Eco: Budget / Expense
4.7FinanceUpdated October 2, 2026
Screenshots
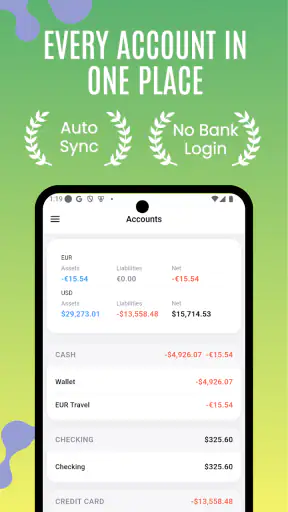
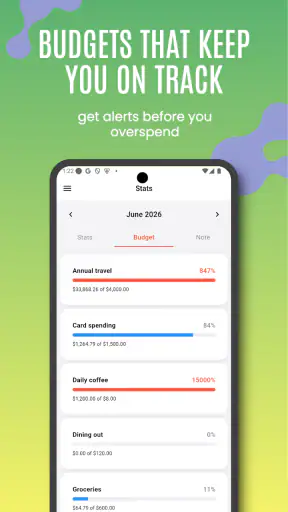
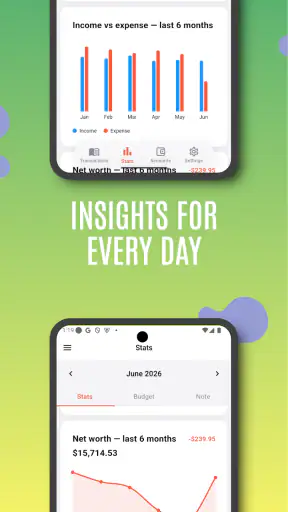
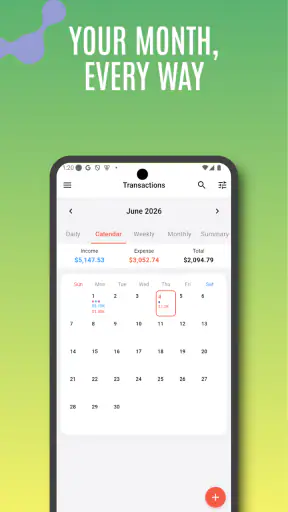
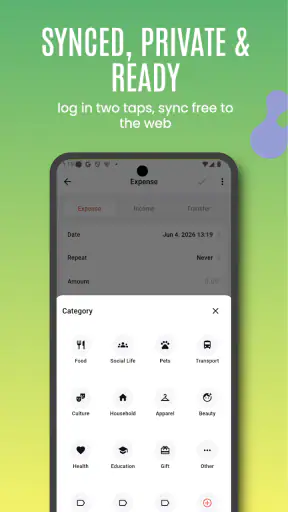
Pros
- Simple interface makes daily expense tracking quick and approachable.
- Useful budget categories help organize spending more clearly.
- Expense records can reveal patterns in everyday financial habits.
- Suitable for users who want a lightweight personal finance tool.
- Fast manual entry encourages regular updates on the go.
Cons
- Manual transaction entry may feel tedious for frequent purchases.
- Limited automation can make tracking less convenient than bank-linked apps.
- Advanced reports and investment tools may be unavailable.
- Budget accuracy depends heavily on consistent user input.
- Privacy details should be reviewed before entering sensitive financial data.
 Analysis By Mobexer
Managing money is difficult enough without an app making every screen feel like a puzzle. I spent time with Money Eco: Budget / Expense to see whether its approach to personal finance is practical for different people and everyday situations, not just attractive in a store preview. My overall impression is that it is a focused finance app for recording spending, organizing a budget, and turning that information into visual reports. It feels most useful when I want a simple picture of where my money is going rather than a complicated financial command center.
Money Eco: Budget / Expense is developed by Apponance, Inc. and is available as a free app for Android users with a compatible operating system. Its audience rating is Everyone, which matches the straightforward subject matter: tracking household expenses, planning limits, and reviewing personal spending. The app has reached over ten thousand installs and holds a 4.7 average from around fifty ratings, so its reception is encouraging, although the relatively small review pool means I would treat that score as a helpful signal rather than a complete verdict.
How Money Eco handles readability and navigation
The central idea is easy to understand. I can enter expenses, place them into a budget structure, and use visual summaries to spot patterns. That is a sensible design for someone who does not want to maintain a spreadsheet. Instead of forcing me to interpret rows of figures every time, the reporting side gives the information a more immediate shape. For a person who thinks more clearly in categories, proportions, or visual comparisons, that can make financial review less tiring.
The strongest accessibility quality here is conceptual simplicity. A finance app can quickly become overwhelming when it combines bank connections, investments, debt tools, alerts, forecasts, and account synchronization. Money Eco stays centered on money management, expense tracking, and visualization. That narrower purpose makes it easier for a new user to understand what the app is meant to do. I would recommend beginning with only a few familiar spending groups rather than trying to recreate an entire financial history in one sitting.
Readable navigation is not only about large text or high contrast. It is also about knowing what action comes next. In my experience, a budgeting tool is easier to use when the path from “I spent money” to “the expense is recorded correctly” is short. Money Eco is best approached with that rhythm: record an item soon after paying, assign it consistently, then return later to inspect the report. That workflow reduces the mental effort of remembering several purchases at once.
The visual report can also help users who struggle with long lists. A list tells me what happened one item at a time, while a summary can reveal that small daily purchases are taking more of the budget than expected. That is a useful distinction for people with limited attention, busy schedules, or difficulty holding several numbers in working memory. The report is not a replacement for careful checking, but it gives me a good starting point for asking better questions about my habits.
Making the first setup less demanding
I would not begin by entering every old receipt. That approach turns a potentially helpful tool into a chore before its value becomes visible. A better method is to add current expenses for several days, use simple categories, and look for the first pattern. Once the categories feel natural, I can decide whether older entries are worth adding. This is especially helpful for users who find dense setup processes stressful or who need visible progress to stay motivated.
Another practical tip is to choose category names that match the language used at home. A category that sounds obvious to one person may be ambiguous to another, particularly in a shared household. Consistency matters more than creating a perfect taxonomy. If I have to pause every time to decide whether a purchase belongs in one of several nearly identical groups, the tracking habit becomes less accessible.
The app’s current version is 7.1.0, so it is not an early experiment with only a rough concept. Still, a version number alone does not guarantee that every interaction will suit every user. People who need very specific navigation behavior, extensive text customization, or assistive technology support should test the app directly on their own device before committing to it as their main financial system.
Motor and sensory considerations during daily use
Expense tracking is a task where small amounts of friction matter. If entering a purchase requires too many precise taps, a user with limited dexterity, tremors, joint pain, or one-handed use may postpone it. That postponement creates a familiar problem: the budget becomes less accurate precisely because recording it is inconvenient. Money Eco makes the most sense when used in short, repeatable sessions, so I would pay close attention to whether the entry process feels comfortable with the way I hold and operate my phone.
A useful personal routine is to record an expense at a calm moment rather than while walking through a crowded shop or carrying bags. This is not a special feature of the app; it is a way to reduce input errors and physical strain. If I am distracted, I am more likely to enter the wrong amount or category, and a visually polished report will then reflect bad information. The app can organize what I enter, but it cannot correct an inaccurate entry without my review.
Visual summaries are potentially helpful for sensory variety because they break up a wall of text and numbers. At the same time, visual finance reports should never be read as self-explanatory by everyone. A user with low vision, color-vision differences, or difficulty distinguishing visual sections may prefer to verify the underlying figures rather than rely only on the graphic impression. I would use the report as a prompt for investigation, not as the sole source of truth.
People who are sensitive to visual clutter may appreciate the app’s focused purpose, but finance screens can still feel intense when several categories and amounts compete for attention. I find it easier to review one period or one spending area at a time. Looking at everything simultaneously can encourage vague conclusions such as “I spend too much,” while a narrower review can produce an action I can actually take, such as adjusting a food budget or checking recurring purchases.
A workflow for users who tire quickly
For someone with fatigue, attention difficulties, or fluctuating energy, I would divide the task into three small visits. First, record only new expenses. Later, check whether the categories are consistent. On another occasion, review the visualization and choose one change. This prevents the app from becoming another demanding administrative task. The important benefit is not completing a perfect financial audit; it is keeping the information current enough to support decisions.
Users who rely on enlarged system text, screen magnification, voice control, or other device-level aids should check how Money Eco responds in practice. I would not assume that an app’s Everyone rating means every interface element is equally comfortable for every ability. Compatibility can vary with the phone, operating system settings, and the user’s preferred method of interaction. Testing one expense entry and one report review is a more reliable check than guessing from the store category.
The free price lowers the barrier to trying the basic experience, which is valuable for people who cannot justify paying before knowing whether a finance tool fits them. The app also offers in-app purchases ranging from under a dollar to around fifteen dollars per item. I would look carefully at the purchase screen before selecting anything, especially if I am trying to keep the budgeting process itself within a strict spending limit. A free download is useful, but it should not be confused with every possible function being free.
Situational access: when the app fits real life
Money Eco is most approachable when I have a few quiet seconds after a purchase. Imagine a weekday lunch: I pay, open the app later on the train, enter the amount, choose the appropriate category, and move on. At the end of the week, the report gives me a clearer view of whether lunches, transport, or small extras are shaping my spending. This scenario shows the app’s practical strength: it turns scattered decisions into something I can review without building a spreadsheet from scratch.
It can also suit a person who wants a private, manual overview rather than a tool that tries to connect every financial account. Manual entry takes discipline, but it gives me control over what is included and how it is labeled. That can be preferable for users who keep separate accounts, use cash, share some expenses with a partner, or simply do not want an automatic system making assumptions about transactions.
For a household, I would establish a shared category vocabulary before relying on the reports. One person might record a pharmacy purchase under health, while another might treat it as household spending. Either choice can work, but inconsistent choices make the visual summary misleading. The app is therefore better for a household that agrees on a method than for a group expecting automatic interpretation of every purchase.
The app may be especially useful for people who learn through reflection. Rather than setting a budget once and forgetting it, I can compare intention with behavior: what did I expect to spend, and what actually happened? That loop is more valuable than a single warning. It encourages me to adjust a plan based on real life, including irregular weeks, social events, or necessary purchases that do not fit neatly into a routine.
There are also situations where I would not depend on it alone. If I need automatic account synchronization, investment tracking, bill negotiation, shared real-time access, or advanced forecasting, a broader personal finance platform may be a better match. Money Eco’s focused design is an advantage for clarity, but that same focus means it should not be treated as a complete replacement for every kind of financial software.
Comparing it with spreadsheets and larger finance platforms
A spreadsheet offers almost unlimited customization, but it asks me to design the categories, formulas, summaries, and maintenance routine myself. Money Eco is more approachable for someone who wants a ready-made expense and visualization workflow. The trade-off is flexibility: a spreadsheet can be shaped around unusual household rules, while an app’s structure may feel restrictive if my finances do not resemble a conventional budget.
Large finance apps often win on automation and breadth. They may suit users who want one dashboard for accounts, investments, subscriptions, and long-term planning. Money Eco is the more sensible choice when the immediate goal is simply to understand spending and keep a budget habit alive. I would choose it for a clean manual overview, and a larger platform for a connected financial picture.
Compared with writing expenses in a notebook, the app has a clearer advantage in turning entries into visual reports. A notebook can feel calmer and more tactile, and some people remember information better when writing by hand. Money Eco is better when I want the review stage to be quicker and more structured. The right choice depends on whether the main obstacle is entering information or making sense of it afterward.
Remaining barriers and honest limitations
The biggest limitation is the dependence on consistent manual behavior. If I forget to record purchases, the reports may look reassuring simply because they are incomplete. This is a common weakness of manual trackers, but it matters greatly for users with memory difficulties, unpredictable routines, or demanding care responsibilities. I would not recommend it as the only tool for someone who needs automatic capture to maintain an accurate record.
There is also a learning trade-off in visual reporting. A chart can make a pattern obvious, but it can also encourage quick judgments without context. A large category may reflect a one-time necessity rather than a bad habit. I need to inspect the entries behind the summary and consider the period being reviewed. Users who prefer precise, line-by-line control may find visual summaries less satisfying than a spreadsheet or ledger.
The in-app purchase range deserves practical attention. Someone using the free experience should decide in advance whether optional spending fits their own plan, rather than treating an upgrade as an automatic part of budgeting. This is particularly important for younger users or anyone managing money under pressure. The Everyone content rating describes the audience level, not whether the app’s optional purchases are appropriate for every household.
Accessibility is another area where I would remain careful. The app’s focused purpose and visual approach may help many people, but I cannot assume that every user will find the text, controls, colors, gestures, and reports equally comfortable. A person who depends on a specific assistive setup should test the complete route from entering an expense to reading a report. If that route is tiring or unclear, a simpler notebook, spreadsheet designed around their needs, or a finance app with more explicit accessibility support may be the better option.
Finally, the rating is positive but based on around fifty ratings and about ten written reviews. That is enough to show that users have responded well, yet not enough for me to treat the score as proof that the app works equally well across every phone, financial routine, and accessibility need. I see it as a promising indicator, not a substitute for a short personal trial.
Inclusive verdict for everyday budgeting
I like Money Eco: Budget / Expense because it focuses on a problem many people actually have: not knowing where their money went by the end of the week. Its combination of manual expense tracking, budgeting, and visual reporting is approachable, and the free entry point makes experimentation easier. The developer, Apponance, Inc., has built something that can serve users who want more structure than a notebook without the complexity of a full financial dashboard.
My recommendation is strongest for people who can maintain a regular recording habit and who benefit from seeing spending patterns rather than reading a long ledger. It can also work well for users who prefer to keep financial information under their own control instead of relying on connected accounts. The most effective approach is to start small, use clear categories, review one area at a time, and verify visual conclusions against the individual entries.
I would steer away from it if automatic importing, advanced financial planning, extensive household collaboration, or highly specialized accessibility behavior is essential. In those cases, a broader or more customizable alternative may save time and reduce frustration. Money Eco is not trying to be every financial tool at once, and that is both its identity and its boundary.
For me, the inclusive value comes from its manageable scope rather than from any promise that one interface will suit everyone. It gives many users a realistic path from scattered expenses to a clearer picture, while still requiring honest attention to entry accuracy, visual interpretation, and device compatibility. If that balance matches the way you handle money, Money Eco: Budget / Expense is worth trying as a focused personal finance companion.
FAQ
What is Money Eco: Budget / Expense used for?
Money Eco: Budget / Expense is designed to help you organize your personal finances in one place. You can record income and expenses, categorize transactions, monitor spending habits, and review your financial activity over time. It is especially useful for users who want a simple overview of where their money goes and who prefer tracking daily purchases manually rather than relying entirely on bank connections.
Is Money Eco: Budget / Expense free to download and use?
The application may be available to download at no initial cost, but some features can depend on the version offered through the Google Play Store or Apple App Store. Before installing, check the current listing for information about advertisements, optional purchases, subscriptions, or premium tools. The free version may provide basic budgeting and expense tracking, while advanced functions could require payment.
Can I use Money Eco: Budget / Expense without connecting my bank account?
Yes, the app is suitable for manual financial tracking, so you can generally enter your income, bills, purchases, and other transactions yourself without linking a bank account. This can be helpful for privacy-conscious users or people whose financial institutions are not supported. However, manual entry requires consistency, because the accuracy of your reports depends on keeping every transaction updated.
Does Money Eco: Budget / Expense protect my financial information?
Because budgeting apps can contain sensitive information, you should review the application’s privacy policy and permissions before adding detailed financial records. Avoid entering unnecessary account credentials, card numbers, or other confidential data unless the app clearly explains how that information is protected. If features such as PIN access, biometric locking, backup, or synchronization are available, enable them to improve account security.
Is Money Eco: Budget / Expense suitable for families or shared budgets?
Money Eco: Budget / Expense can be useful for individuals and may also help families plan spending by organizing household income, recurring bills, and expense categories. However, you should verify whether the current version supports multiple users, shared accounts, synchronization across devices, or collaborative budgets. If those tools are unavailable, each person may need to record transactions separately and compare the results manually.











