

Money App - Cash Advance
4.2FinanceUpdated October 5, 2026
Screenshots
Pros
- Simple application process with minimal paperwork
- Fast eligibility checks can provide quick access to funds
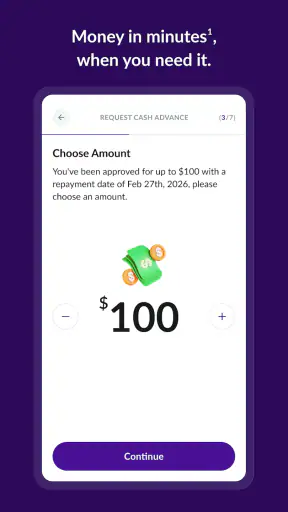
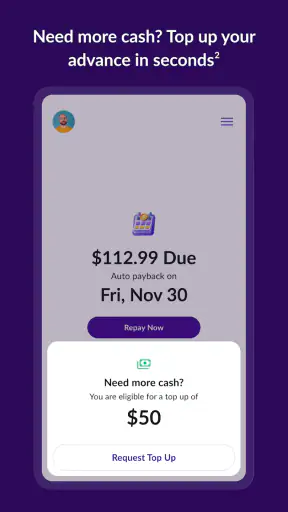
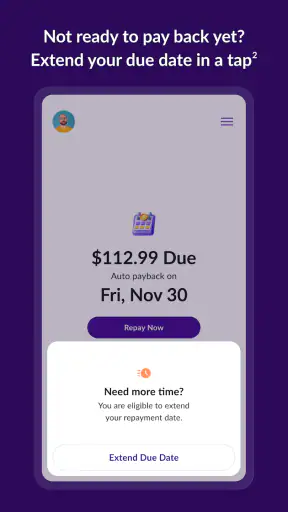
- Repayment dates and loan details are shown clearly
- Useful for covering unexpected short-term expenses
- Available through a convenient mobile interface
Cons
- Advance fees may make borrowing expensive
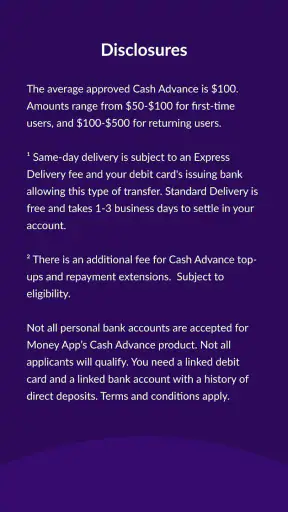
- Approval and loan amounts depend on eligibility
- Late payments could lead to additional charges
- Not available in every country or U.S. state
- Repeated advances may encourage a cycle of borrowing
 Analysis By Mobexer
I approached Money App - Cash Advance as a practical finance tool rather than a general budgeting companion. Its purpose is straightforward: help people look into emergency cash when an unexpected expense arrives. That narrow focus is important, because the app makes more sense during a short-term money problem than as an everyday replacement for a bank account, savings plan, or full budgeting service.
Developed by PRG Ventures, it is a free finance app with an Everyone content rating. It has reached over 500 thousand installs and holds a 4.2 average from around 10 thousand ratings, which suggests that many people find the basic idea useful while still leaving room for mixed experiences. I found the strongest reason to consider it is convenience: it puts an emergency-cash request into a mobile workflow instead of making the user begin with a branch visit or a long search through unrelated financial products.
How Money App feels to use when you need help quickly
Readability and navigation matter more than flashy design
With an emergency-finance app, clear wording is not a cosmetic detail. A person opening it may already be stressed, tired, or trying to solve a bill before a deadline. The best experience is one that makes the next step obvious, keeps the amount of information manageable, and avoids making the user guess whether a button starts an application, displays an estimate, or moves toward an actual offer.
My advice is to read each screen slowly even if the layout feels simple. Cash-advance products can involve important conditions, eligibility checks, repayment expectations, or account requirements. A large action button can make a process feel easy, but it should not replace careful reading. I would treat every summary as an invitation to inspect the details rather than as the whole agreement.
The app’s focused purpose can help people who become overwhelmed by broad financial dashboards. Someone looking only for emergency cash does not have to sort through investing charts, spending categories, or credit-monitoring features first. That focus is one of its more useful design choices. At the same time, a narrow purpose means the app may feel less helpful to a user who wants a complete view of income, recurring bills, savings, and debt in one place.
I also recommend preparing the information you may need before starting. Have a clear idea of the expense, the amount you can realistically repay, and the account details requested during the process. This is a small but meaningful accessibility improvement: it reduces backtracking, prevents rushed guesses, and makes the experience easier for someone who has difficulty switching between screens or remembering instructions.
Motor and sensory considerations during an urgent request
Financial apps are often used one-handed, on a small screen, or while the user is moving between work, home, and a service counter. That makes touch accuracy and readable controls especially important. People with limited dexterity may benefit from taking the process at a table rather than trying to complete it while walking or holding other items. A stable position also lowers the chance of tapping the wrong option when the consequences of a mistake are financial rather than merely inconvenient.
For users with low vision, the practical test is whether the text remains comfortable at the device’s enlarged display setting and whether important distinctions rely on more than color. I would not assume that every screen will remain equally clear after increasing text size, so checking the full flow before an emergency is sensible. If a label becomes clipped, overlaps another control, or forces horizontal movement, that is a real barrier even when the original layout looks tidy.
People with dyslexia, attention difficulties, or cognitive fatigue may find short screens easier than dense financial explanations, but brevity can also hide context. I would pause at every point where the app summarizes an amount, timing, or obligation and read the supporting text before continuing. A useful personal habit is to take notes in plain language: “amount requested,” “amount received,” and “amount expected back.” That separates the immediate need from the longer-term cost.
For users who are deaf or hard of hearing, a finance workflow should ideally communicate important status changes in text rather than depending on sound. I would keep notifications visible and check the app directly after submitting information instead of relying on an alert tone. For blind users, compatibility with the phone’s screen reader is something to test early, especially around unlabeled controls, form fields, and confirmation messages. I cannot treat general mobile compatibility as proof that every part of this particular app is equally accessible.
Situational access: when the app is useful and when timing changes everything
A realistic use case is a broken household appliance or an urgent travel expense arriving just before payday. In that situation, a person may want to explore emergency cash from a phone rather than spend an afternoon comparing unrelated services. Money App can be a convenient starting point, particularly if the user already knows the amount needed and can review the terms without pressure.
However, convenience should not turn into automatic acceptance. I would first ask whether the expense can be delayed, reduced, covered by an existing emergency fund, or handled through a lower-cost option. If the request would only move the same shortfall into the next pay period, the app may solve today’s problem while making the following weeks harder. That is the central trade-off: speed and simplicity can be valuable, but they do not remove the underlying affordability question.
The app may also suit people who are comfortable completing forms on a phone and checking financial information digitally. It is less suitable for someone who needs face-to-face explanation, printed documents, a translator, or a support person present before making a borrowing decision. In those situations, a local financial counselor, bank representative, or trusted adviser may provide better communication than a mobile-first process.
Situational access includes connectivity and privacy. I would avoid beginning a financial request on public Wi-Fi or while surrounded by people who can see the screen. A quiet, private setting gives the user time to review details and reduces the risk of exposing personal information. If the phone is shared with family members, I would also think carefully about who can see notifications or recent activity before using a finance app.
What it does better than familiar alternatives
The usual alternatives fall into several groups: asking a bank about an overdraft or personal loan, using a credit card, borrowing from someone close to you, visiting a community organization, or using another cash-advance service. Money App’s appeal is that it creates a dedicated mobile route for exploring emergency cash without requiring the user to begin with a broad banking relationship or a face-to-face appointment.
That does not make it automatically cheaper or safer than every alternative. A bank product may offer clearer ongoing account support for an existing customer. A community resource may be more appropriate when repayment would be difficult. A credit card may be more flexible for a purchase, while a personal loan may be more suitable for a larger, planned expense. I would compare the full obligation, timing, and consequences rather than choosing based only on how quickly the first screen appears.
One useful workflow is to use the app as an information checkpoint, not as a decision shortcut. Before accepting anything, write down the requested amount and the total repayment expectation shown in the process, then compare that with two alternatives. This takes only a few minutes but prevents the common mistake of comparing only the cash received today. For a small, genuinely temporary gap, that distinction can determine whether the solution is manageable.
Remaining barriers and points where users should slow down
The biggest limitation is inherent to the category: emergency cash is not free money. Even though the app itself is free to install, the financial product explored through it should be judged separately from the download price. Users should pay attention to any conditions, repayment timing, eligibility language, and account impact presented during the process. I would never treat the word “free” as a description of the borrowing outcome.
Another barrier is emotional pressure. When a bill is urgent, people may skim, accept the first available option, or request more than they need because the process feels immediate. The app cannot solve that judgment problem for you. I found it more responsible to decide the maximum affordable amount before opening the request and to stop if the terms do not fit that limit.
Accessibility can also break down through small details: text that is difficult to enlarge, unclear error messages, form fields that do not explain what went wrong, or a confirmation that does not make the next step obvious. If any of those appear, I would not repeatedly submit the same information. I would check the entry carefully, save a private note of what happened, and seek support through the appropriate channel rather than risking duplicate requests.
Users who need extensive budgeting tools may outgrow the app quickly. It is not the first choice I would make for tracking spending patterns, organizing long-term goals, or planning debt reduction. A dedicated budgeting app or a bank’s account-management tools may offer a more complete picture. Likewise, people who cannot confidently predict how they will repay an advance should consider non-borrowing support before using a cash-focused service.
Device support, trust, and everyday preparation
The app runs on Android devices using version 7.0 or later, so it is available to people who keep an older compatible phone rather than upgrading frequently. That can be helpful for users on limited budgets, although practical performance will still depend on the device, screen, connection, and other apps running at the same time. Before an urgent need arises, I would open the app once, inspect the navigation, and make sure the phone’s text and accessibility settings work comfortably with it.
The current version is 2.47.0, and the app was released on February 12, 2024. Those details are useful when checking whether the installed build is current, especially if a screen shown in an older guide looks different. I would rely on the app’s own current wording rather than screenshots from another person, because financial flows and explanations can change between versions.
PRG Ventures is the developer behind the app, and the public response gives it a solid but not flawless 4.2 average. I read that as a reason to investigate rather than as a guarantee. A rating can tell you that the broad experience works for many people, but it cannot decide whether a particular cash request is affordable or whether the interface will meet an individual’s accessibility needs.
My inclusive verdict for different kinds of users
I would recommend Money App to an adult who needs a focused way to explore emergency cash, can review financial conditions independently, and has a realistic repayment plan. Its free entry point, dedicated purpose, and mobile format make it easier to consider than starting from a collection of unrelated financial tools. It is also a reasonable option for someone who prefers reading and completing a process privately on a phone.
I would be more cautious for users with low vision, limited dexterity, cognitive fatigue, language barriers, or a need for human explanation. The right approach is to test the early screens before an emergency, enlarge text, enable the phone’s preferred accessibility tools, and ask a trusted person to help review the meaning of the offer without handing over control of personal accounts. That preparation is more valuable than assuming a general Everyone rating covers every access need.
My final view is balanced: this is a useful emergency-cash doorway, not a complete financial safety net. I like the focused workflow, but I would only use it after comparing alternatives and writing down what repayment would mean for the next pay period. The most inclusive way to use Money App is to slow down the decision even when the app makes the request feel quick. If the language is clear on your device, the controls work with your settings, and the obligation fits your budget, it may be worth considering. If any of those conditions fail, a bank, community service, or human adviser is likely to be the better route.
FAQ
What is Money App - Cash Advance, and how does it work?
Money App - Cash Advance is designed to help eligible users request access to a small amount of money before their regular payday. After creating an account, you may be asked to provide personal, employment, income, and banking information so the service can evaluate your request. Approval, available limits, transfer speed, and repayment conditions depend on the provider’s policies and your individual profile.
Is Money App - Cash Advance a loan, and does it charge fees or interest?
Although the app may present itself as a convenient cash advance service, the exact product can vary by location and provider. Some advances may include subscription charges, express-transfer fees, optional tips, or other costs, while partner lenders may apply interest or an annual percentage rate. Before accepting an advance, carefully review the total repayment amount, due date, fees, and applicable disclosures.
Who can use Money App - Cash Advance, and what information is required?
Eligibility is generally limited to adults who live in supported regions and meet the service’s identity, income, employment, and banking requirements. During registration, the app may request details such as your legal name, address, date of birth, government identification, bank-account information, and permission to verify income. Requirements can differ significantly depending on your state or country.
How quickly can I receive money through Money App - Cash Advance?
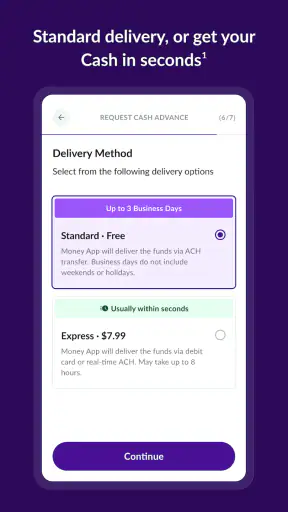
The time required to receive funds depends on approval, bank verification, processing schedules, and the delivery option selected. Standard transfers may take longer and can arrive within one or several business days, while an instant option may be available for an additional fee. The app should display the expected delivery date and any charge before you confirm the transaction.
What should I know about repayment, privacy, and using a cash advance responsibly?
Repayment is usually scheduled for a specific date, often when your next paycheck arrives, and the amount may be collected automatically from your linked account. Make sure sufficient funds are available to avoid failed payments or additional charges. Also review the privacy policy before granting access to financial data, and avoid relying on advances repeatedly because fees and short repayment periods can make financial difficulties worse.











