

MoBill Budget and Reminder
4.0FinanceUpdated October 2, 2026
Screenshots
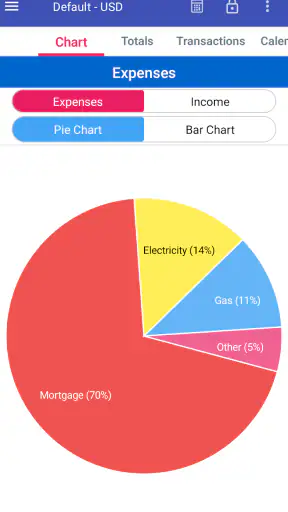
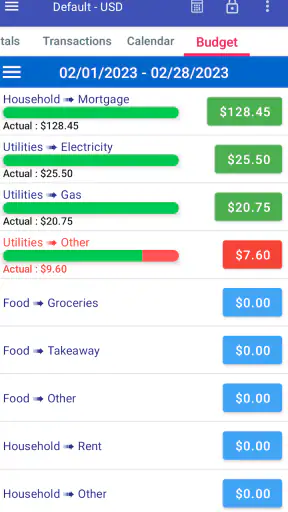
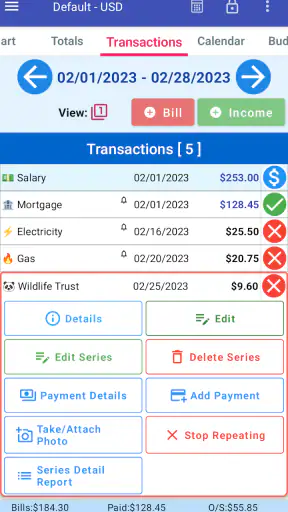
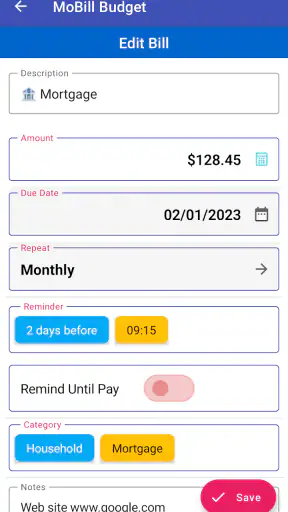
Pros
- Simple budget tracking with clear spending categories.
- Useful reminders help prevent missed bills and payments.
- Quick expense entry makes daily updates less time-consuming.
- Supports better awareness of recurring monthly expenses.
- Clean interface is approachable for users new to budgeting.
Cons
- Some advanced budgeting tools may require a paid upgrade.
- Manual transactions can become tedious for frequent purchases.
- Customization options may feel limited for complex finances.
- Reminder reliability can depend on device notification settings.
- May not offer full bank synchronization in every region.
 Analysis By Mobexer
I tend to be careful with finance apps because convenience is only half the question. The other half is whether the app gives me enough control to understand what I am entering, what it is storing, and how much of the process depends on my own choices. MoBill Budget and Reminder takes a straightforward personal-finance approach: it is designed to help organize a budget and keep upcoming obligations visible, rather than turning money management into a complicated planning exercise.
After spending time with it, I see the appeal. The app is compact, focused, and easier to approach than many modern finance tools that immediately ask users to connect accounts or build an elaborate financial profile. At the same time, that simplicity means I have to do more of the setup and maintenance myself. For someone who wants a hands-on budget notebook with reminders, that can be a strength. For someone expecting automatic account synchronization, investment analysis, or a polished household-finance dashboard, it may feel limited.
How MoBill Budget and Reminder earns trust
MoBill Budget and Reminder comes from MoBill Apps and sits in the finance category. It is free to install, carries an Everyone age rating, and has been available since February 28, 2011. Its long presence and broad adoption give it useful context: it is not presented as a brand-new experiment, and its user base has had time to form a practical opinion. The app has an average rating of 4.0 from around 3.8 thousand ratings, with more than 1.6 thousand written reviews and over 500 thousand installs.
Those figures do not automatically prove that an app is right for me, but they do make the product easier to evaluate than an unknown finance utility. I still prefer to judge it by the choices it puts in front of me. In this case, the important question is not whether it promises to solve every money problem. It is whether I can use it without surrendering the basic visibility I need over my own budget.
The current version is 5.3.1 and requires Android 8.0 or later. That requirement is reasonable for people using a relatively recent Android phone, although anyone keeping an older device should check compatibility before planning a long-term budgeting routine around it. A finance app becomes most useful when it is available consistently, so operating-system support is not a minor detail here.
I also appreciate that the basic download does not require an upfront purchase. Optional in-app items range from around two and a half dollars to nearly eleven dollars per item. That makes it important to pay attention during any upgrade or purchase screen rather than assuming every tool is included automatically. The free entry point is helpful, but users who want the full experience should decide deliberately whether an optional expense is worthwhile.
What the app feels like in everyday use
The central experience is built around entering and reviewing personal money information. I think of it less as a bank replacement and more as a private control panel for planned spending and recurring financial obligations. That distinction matters. I am not opening it to move money between accounts; I am opening it to remind myself what needs attention and to keep my spending plan from becoming vague.
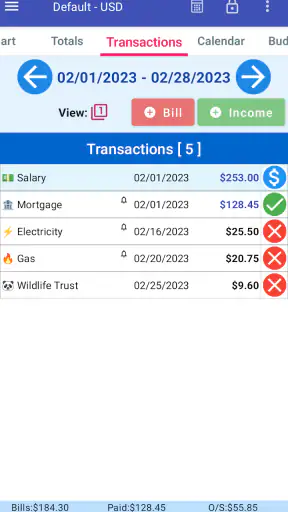
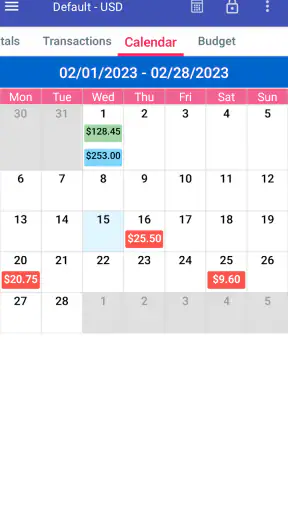
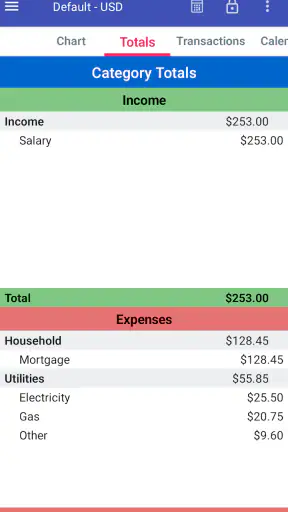
A realistic use case is a monthly household routine. I can sit down after payday, record the bills that need to be covered, note regular spending categories, and then return to the app before the next round of due dates. If a payment date changes, the value comes from correcting the plan immediately instead of relying on a paper note or a memory. The app is most useful when I treat it as a living record rather than a one-time setup screen.
That workflow also reveals its main trade-off. Manual finance tools can feel more transparent because I decide what goes in, but they depend on discipline. If I forget to record a cash purchase or postpone updating a changed bill, the picture becomes less accurate. Automatic aggregation is more convenient in that situation, while MoBill’s approach is better suited to people who prefer to enter information intentionally.
Controls matter more than a polished dashboard
When I review a finance app, I look for moments where it lets me pause and make a clear choice. Adding an obligation, changing a budget item, or deciding whether to purchase an optional feature should not feel like an accidental commitment. MoBill Budget and Reminder is most comfortable for users who want to remain directly involved in those decisions instead of handing the entire process to automation.
That user-controlled style is also useful for separating essential information from noise. I can focus on the bills and spending areas that matter to my situation rather than accepting a generic financial picture built around services I do not use. Someone with a simple budget may find that refreshing. A person with several accounts, shared finances, irregular income, and investments may instead want a more connected platform with broader reporting.
I would not use a finance app casually without checking its visible settings and purchase prompts. Before entering sensitive financial details, I would inspect what the app asks me to provide, review any available account or privacy controls, and avoid entering information that is not necessary for my budgeting purpose. That is not a criticism unique to this product; it is a sensible habit for any tool that handles personal money information.
The important point is that I should be able to understand my own workflow. If I cannot tell whether an entry is a planned bill, an actual expense, or a reminder for later, the app stops being helpful. MoBill works best when I establish a consistent naming and recording habit from the beginning. For example, I would use the same wording for a recurring utility payment each month and keep one-off purchases separate from planned obligations.
Where financial data needs extra care
Finance information is sensitive even when it is only a list of bills and budget amounts. A phone may be shared, lost, repaired, or replaced, and a visible reminder can reveal more than I intended. I would therefore avoid entering unnecessary account credentials, full payment details, or identifying notes into a budgeting record. A simple label such as “monthly service” may be safer than writing a complete account reference when the extra detail is not needed.
I would also think about the difference between a reminder and proof of payment. A scheduled item can tell me that something should happen, but I should still verify the actual transaction through the relevant provider or bank. This is one of the app’s practical limits: a personal budget record is only as reliable as the information I maintain. It should support my financial routine, not replace checking the source of a payment.
The same caution applies when changing phones. Before relying on the app as the only record of a budget, I would look through its available export, backup, or transfer choices and make a separate copy if the app offers a suitable method. I would not assume that every finance entry will automatically appear on a new device. Keeping a secure backup plan is especially important when the information represents several months of household planning.
Notifications deserve attention too. A reminder that appears at the wrong time or displays too much detail on a lock screen can be inconvenient or revealing. I would adjust notification behavior at the phone level where possible and choose reminder wording that does not expose sensitive information. This is a small habit, but it improves the privacy of any bill-tracking routine.
Who gets the most value from it
I think MoBill Budget and Reminder is a good match for someone who wants a focused budgeting and bill reminder app without committing to a large financial ecosystem. It suits users who are comfortable entering their own figures, checking them regularly, and making decisions based on a clear personal plan. It can also work well for a person who wants to keep budgeting separate from banking rather than connecting every financial account to one service.
It is particularly practical for people whose main problem is forgetting dates or losing track of planned expenses. A student managing rent and recurring services, a household organizing monthly bills, or a freelancer setting aside money for predictable obligations could all benefit from a dedicated reminder routine. The advantage is not magic automation; it is creating one place to revisit the commitments that are easiest to overlook.
I would be more cautious about recommending it to someone who wants automatic transaction imports, shared real-time household access, detailed investment tracking, tax preparation, or advanced forecasting. Those needs usually call for a broader financial platform. Likewise, anyone who dislikes manual entry may abandon this app quickly, because a budgeting system only works when its records are kept current.
It may also be the wrong choice for a user who expects a highly guided financial coaching experience. The app’s value is closer to organization than instruction. It can help me see and remember my own plan, but it should not be mistaken for professional financial advice or a substitute for dealing directly with creditors, banks, or service providers.
Three habits that make the app more dependable
My first recommendation is to set up the recurring obligations before adding a large amount of optional spending. That establishes the fixed shape of the month and makes it easier to see what money is already committed. Only after that would I add flexible categories, because otherwise a long list of small purchases can hide the payments that have the greatest consequences if missed.
Second, I would review the app at two different moments: once when planning and again after the relevant payments or purchases occur. Planning answers “what should happen,” while the later check answers “what actually happened.” Keeping those two mental steps separate reduces the risk of treating an old estimate as a confirmed transaction.
Third, I would use neutral descriptions for sensitive entries and avoid storing more personal detail than the budget requires. This makes the record easier to scan and reduces the impact if someone briefly sees the screen. It also improves consistency: short, repeatable labels are faster to review than long notes that vary from month to month.
A fourth useful habit is to test the reminder routine with a low-risk upcoming item before depending on it for an important payment. That gives me a chance to understand how the notification appears, whether the timing suits my schedule, and whether I need a second reminder outside the app. I would never make one application my only safeguard for a critical financial deadline.
How it compares with common alternatives
Compared with a spreadsheet, MoBill Budget and Reminder is more purpose-built for recurring personal finance tasks. A spreadsheet offers greater freedom, custom formulas, and easy rearrangement, but it also requires me to design the structure and maintain it. MoBill is the more approachable option when I want a ready-made budgeting habit rather than a small accounting project.
Compared with a banking app, it can provide a more deliberate planning view because it is not limited to transactions that have already passed through one institution. I can think about upcoming obligations and personal categories in one place. The banking app remains stronger for confirming actual balances and payments, so I see the two as complementary rather than interchangeable.
Compared with an account-aggregation service, MoBill may feel less automatic and less comprehensive. Aggregation can save time and reveal patterns across accounts, but it introduces a different trust decision because I may be asked to connect financial services. A manually maintained tool gives me more control over what I record, while demanding more effort and offering less complete automatic visibility.
That comparison explains the app’s proper niche. It is not trying to be a full financial command center in my daily routine. Its usefulness comes from keeping a personal plan and reminders close at hand, with the user responsible for deciding what belongs there and checking whether the information remains accurate.
My cautious verdict
After weighing the convenience against the manual work, I see MoBill Budget and Reminder as a sensible choice for people who value direct control and a focused budgeting routine. The free starting point, Everyone rating, long availability, and substantial user adoption make it approachable, while the current Android requirement keeps it relevant for many devices. I also like that its role is easy to understand: organize money plans and remember obligations.
My recommendation comes with a clear condition: use it as an aid to personal organization, not as an unquestioned source of financial truth. Keep entries current, verify payments elsewhere, protect sensitive details, and review any optional purchase before accepting it. Those steps are especially important because manual control is both the app’s strength and its responsibility.
If I wanted a simple, hands-on way to structure bills and spending reminders, I would consider MoBill Budget and Reminder worth trying. If I needed automatic bank connections, collaborative household features, investment tools, or deep financial analysis, I would choose a more specialized alternative instead. For the right user, the strongest benefit is knowing exactly what I chose to record and why; for the wrong user, the same lack of automation may become the reason the budget falls out of date.
FAQ
What is MoBill Budget and Reminder used for?
MoBill Budget and Reminder is designed to help you organize personal finances by tracking bills, recurring payments, budgets, and payment reminders in one place. After setting up your accounts and due dates, the app can give you a clearer view of upcoming expenses and help reduce the risk of forgetting subscriptions, utilities, rent, loans, or other regular obligations.
Can I create recurring bills and payment reminders in MoBill?
Yes, recurring bills and reminders are among the app’s most useful features. You can record expenses that repeat on a schedule, such as monthly rent, weekly services, annual renewals, or installment payments. Before relying on notifications, check the reminder settings, repeat frequency, and phone permissions to ensure alerts are allowed and scheduled according to your needs.
Does MoBill Budget and Reminder support budgeting and expense tracking?
The app is intended not only for listing bills but also for monitoring spending against planned budgets. You can use categories or payment records to understand where your money is going and compare expected expenses with your available funds. The experience is most helpful when entries are kept up to date, since missing transactions can make budget information less accurate.
Is MoBill Budget and Reminder safe for storing financial information?
MoBill may contain sensitive information such as bill amounts, account names, due dates, and spending habits, so users should review its privacy policy and permissions before entering personal data. Avoid adding passwords, card PINs, or complete banking credentials unless the app explicitly provides a secure, trusted feature for them. Also protect your device with a lock screen and keep the app updated.
Is MoBill Budget and Reminder free, and does it require an internet connection?
Availability of free features, premium options, advertisements, and in-app purchases can vary by platform and app version, so check the current Google Play or App Store listing before downloading. Basic bill management may work without constant internet access, but features such as synchronization, backups, updates, or external integrations could require connectivity. Review the store description for the latest requirements.











