

Jim: sell & get paid instantly
4.3FinanceUpdated October 5, 2026
Screenshots
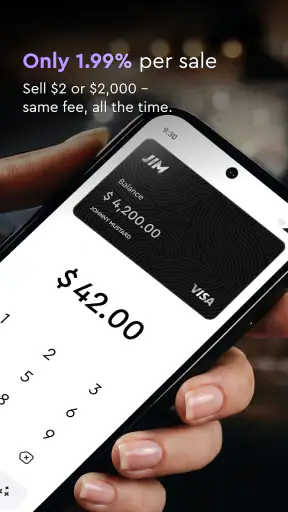
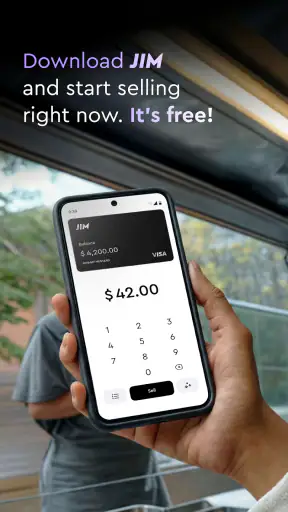
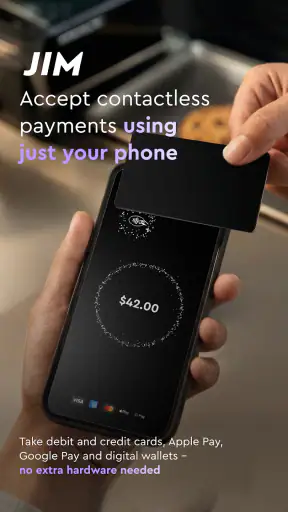
Pros
- Instant payment collection helps improve cash flow.
- Simple interface makes sending payment requests quick.
- Useful for freelancers and small businesses.
- Digital records make transactions easier to track.
- Supports convenient cashless payments for customers.
Cons
- Availability may vary by country or supported payment methods.
- Transaction fees can reduce the amount you receive.
- Requires internet access for most payment actions.
- Account verification may take time before full use.
- Refunds and payment disputes may not be immediate.
 Analysis By Mobexer
I tested Jim: sell & get paid instantly as a finance app for the moment when a normal card terminal is inconvenient, unavailable, or simply too much equipment to carry. Its basic idea is easy to understand: use your phone as the point where a customer pays. That makes Jim interesting for independent sellers, mobile professionals, small stalls, and anyone who occasionally needs to accept a card payment away from a traditional checkout.
What I like most is that the app is built around a practical situation rather than a complicated financial dashboard. You begin with a sale, move through the payment process on your phone, and finish with money collected. The experience feels most useful when speed and portability matter more than a full retail system. At the same time, I would not treat it as an automatic replacement for every card reader. The quality of the experience depends on how well the seller prepares, how comfortable the customer is with the handoff, and whether the business needs records and controls beyond taking a payment.
From a sale on the move to a completed payment
The starting condition: when carrying a terminal is the problem
Imagine I am selling handmade items at a small market. A customer chooses something, but I do not want to send them away because I accept only cash. Carrying a separate card machine would solve that problem, but it also means another device, another battery to monitor, and another object to remember before leaving home. Jim approaches the situation differently by placing the payment starting point on the phone I already carry.
That same workflow can make sense for a repair worker collecting payment after a visit, a tutor finishing a lesson, a pop-up seller working from a temporary table, or a small business that receives occasional in-person orders. The app belongs to the finance category, but I found its value to be very physical and immediate: it connects the conversation with the customer to the payment action without requiring a conventional checkout counter.
Jim is free, rated for Everyone, and developed by CloudWalk. Its current version is 1.4.19, and it runs on Android 7.0 or later. Those details make it approachable for people who are not using a brand-new phone, although a compatible operating system alone does not guarantee that every payment situation will feel equally smooth. I would still prepare the phone before meeting customers rather than treating installation as something to do during a busy sale.
Preparing before the customer is standing in front of me
The first useful habit is to separate setup from selling. I would install Jim, open it in a quiet moment, and walk through the account and payment screens before relying on it in public. This is not glamorous advice, but it prevents the most awkward failure: discovering that I still need to understand a confirmation step while a customer is waiting.
I would also check the phone itself. A nearly empty battery, a dirty screen, weak connectivity, or an operating system that has not been maintained can turn a short transaction into a long explanation. Because the phone becomes part of the checkout, I would keep it charged, remove unnecessary distractions, and use a clear screen lock routine. A dedicated work phone is not essential, but it can make the boundary between personal messages and customer payments easier to manage.
Another preparation step is deciding how I will describe the payment to customers. A phone-based card reader can be unfamiliar to someone who expects a separate terminal. A calm explanation such as “I’ll take the payment here on my phone; please follow the payment prompt” is better than silently passing the device over. The customer should know when they are expected to act and when the transaction is complete.
The step-by-step flow during a real sale
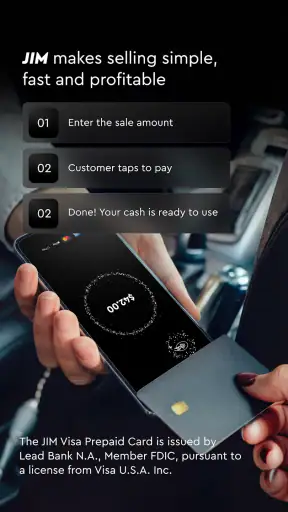
My preferred workflow starts before I open the payment screen. I confirm the item or service, repeat the total aloud, and only then begin the transaction. That small pause reduces the risk of entering the wrong amount while trying to remember what was agreed. It also gives the customer a chance to correct the total before any payment action begins.
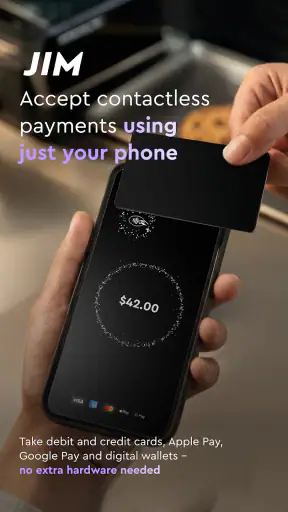
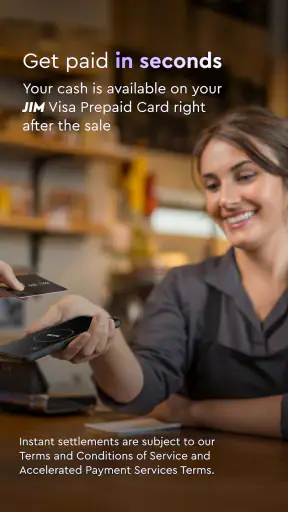
Next, I use Jim to start the sale on the phone. The app’s central promise is turning the handset into a card-reading point, so the phone is no longer just displaying information; it is the object through which the customer completes the purchase. I would keep the device steady and make sure the relevant screen is visible, rather than continuing to hold it at an angle while talking or packing an item.
The customer then takes the appropriate part of the interaction. This is where a clear handoff matters. I would avoid touching the phone while the customer is completing the payment, and I would not ask them to hurry. Even when the app is designed for fast payment, the customer needs enough time to read what is shown and act confidently. Speed is useful only after the sequence is understood.
Once the payment appears to finish, I would wait for the app’s confirmation before handing over the product or closing the conversation. This is one of the most important practical distinctions between “the customer tried to pay” and “the sale is complete.” If the screen has not clearly reached the finished state, I would treat the transaction as pending from my point of view and resolve that before releasing goods.
For a busy stall, I would create a simple rhythm: confirm the order, enter the amount, let the customer complete the payment, verify the result, and only then move to the next person. Trying to serve two customers while one payment is still open is an avoidable source of confusion. The phone-based format is compact, but it does not remove the need for orderly queue management.
The handoffs that decide whether Jim feels easy
The first handoff is between seller and customer. I control the amount and initiate the transaction; the customer needs to understand when to participate. If I hold onto the phone throughout, the customer may be unsure whether they should touch it. If I pass it over too early, they may see a screen that is not ready. Jim works best when I treat the handoff as part of the sale rather than as an afterthought.
The second handoff is from the payment screen back to the seller’s record of the sale. I would immediately note what was sold and to whom, especially if I am handling several orders. A phone reader can complete the money movement without automatically replacing the business habits that keep inventory, appointments, or service notes organized. For a very small operation, a manual note may be enough; for a larger one, the separation becomes more noticeable.
The third handoff is the customer’s confidence in the result. A customer may ask whether the payment worked, whether they can leave, or whether they will receive confirmation. I would show the completed state on the phone and provide whatever transaction evidence the app makes available in the normal flow. The important point is to make the ending visible instead of simply saying “done” while the screen is still changing.
These handoffs reveal a useful trade-off. Jim can reduce the equipment burden, but it places more responsibility on the seller’s communication and discipline. A traditional terminal often looks self-explanatory because customers recognize its shape and sequence. With a phone, the seller must create that clarity through words and timing.
A realistic everyday scenario
Suppose I run a small weekend table selling prints. A customer chooses two items while another person is browsing. I confirm the combined total, open Jim, and start the payment while keeping the selected prints aside. I then give the phone to the first customer for the payment step, wait for the completed confirmation, and mark the sale in my notebook before serving the next person.
The non-obvious advantage here is not merely that I avoided carrying a terminal. The phone also lets me keep the payment tool close to the rest of my working routine. I can move from the table to a nearby customer without changing the basic setup. That is particularly helpful when sales happen irregularly rather than through a fixed checkout line.
The weakness appears when the environment becomes crowded. If people are waiting, the phone is also being used for calls, messages, navigation, or product photos, and the payment process takes longer than expected, the compact setup can become a bottleneck. I would therefore use Jim confidently for mobile or occasional selling, but I would think twice before making it the only checkout method for a high-volume event.
What happens after the payment?
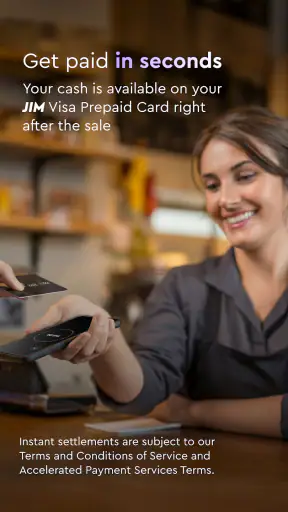
The immediate result is the part Jim communicates most clearly: the customer has paid through the phone-based reader, and I can move toward completing the sale. For a simple exchange, that may be all I need. The app’s appeal is strongest when the desired outcome is direct payment collection rather than a large back-office operation.
Afterward, I would build a short closing routine. I would confirm the payment state, record the order, put the phone back into a secure position, and only then hand over the goods or continue the service. This order matters because it protects against mixing a successful payment with a different customer’s order. It also makes end-of-day reconciliation less dependent on memory.
For sellers who work alone, that routine can be more valuable than it sounds. There is nobody else checking totals, watching the screen, or remembering which customer paid. Jim can shorten the equipment list, but I still need a deliberate method for matching each completed payment to the item or service delivered.
Where the flow breaks down
The first likely break is connectivity or device readiness. A phone-based payment experience cannot be judged only by how quickly the screen opens in ideal conditions. If the network is unreliable, the battery is low, or the phone is overloaded with other tasks, the seller may face a delay at exactly the moment trust matters most. I would always have a backup plan for a customer who cannot complete the payment immediately, such as another accepted method or a clear way to pause the sale.
The second break is customer hesitation. Some people are comfortable paying through a phone; others are more familiar with a dedicated terminal. The app does not remove that human difference. I would explain the process without pressuring the customer, keep the phone steady, and give them time to read the screen. If my business serves many people who expect a conventional terminal, a standard card reader may create less friction even if it is less portable.
The third break is operational scale. Jim may be a sensible fit for one person taking occasional payments, but a team with several sellers, complicated inventory, refunds, detailed receipts, or formal reconciliation needs may outgrow a phone-centered workflow. In that case, a full point-of-sale system could be better because the payment is only one part of the job. I would not choose Jim simply because it is free if the surrounding record-keeping becomes difficult.
A fourth issue is the phone handoff itself. Passing a personal device to a stranger can feel uncomfortable, and the seller must remain alert to what is visible on the screen. I would close unrelated apps, avoid displaying private notifications, and use a work profile or separate device when customer volume justifies it. This is a practical privacy habit, not a feature claim, and it improves the professionalism of the exchange.
How it compares with the usual alternatives
Compared with cash, Jim removes the need for the customer to carry the exact amount and can make spontaneous purchases easier. Cash still has the advantage of working without a phone-centered handoff and may feel simpler for very small transactions. I would choose Jim when card acceptance helps me close sales, not because it makes every payment method obsolete.
Compared with a dedicated card terminal, the app wins on portability and the number of devices I need to carry. A terminal usually communicates its purpose immediately and can be more comfortable for repeated transactions. Jim is the better fit when I value minimal equipment and already have a suitable phone in hand; the terminal is the safer choice when checkout volume, shared use, or customer familiarity matters more.
Compared with a broader point-of-sale app, Jim appears more focused on the act of getting paid. A full system may be preferable for stock control, staff permissions, detailed sales reporting, or a larger catalog. I would use Jim for a lean workflow and avoid forcing it to serve as an entire business-management platform.
Its audience size suggests that the concept has found interest: Jim has more than one hundred thousand installs, an average rating of 4.3 from around two thousand ratings, and 471 written reviews. I see those figures as encouraging signs of adoption, but not as a guarantee that the app will suit every phone, customer group, or selling environment. My own decision would still be based on the transaction flow I actually need.
Who should use it, and who should skip it?
I would recommend Jim to independent sellers, mobile service providers, occasional vendors, and small operators who want to accept card payments without building a full checkout station. It is especially appealing when the same person handles the customer, the product, and the payment, and when portability is more important than advanced business administration.
I would be more cautious if I ran a busy shop, shared payment duties with several employees, needed a robust inventory process, or could not tolerate a phone becoming unavailable during a sale. I would also skip it as my only option if my customers strongly prefer a familiar terminal or if my work routinely happens in places where the phone connection is unreliable.
Before committing to it for regular business, I would run several low-pressure test transactions, rehearse the customer handoff, and decide how I will record each completed sale. I would also test my backup payment method and make sure the people working with me understand when a transaction is genuinely finished. Those steps expose workflow problems before they become customer-facing problems.
My final take after following the whole workflow
Jim: sell & get paid instantly is a focused finance app with a clear practical purpose. I like it because it treats the phone as a lightweight payment tool, which can be a real advantage for sellers who move around or do not want another piece of hardware. The free price and Everyone age rating also make it easy to consider, while CloudWalk gives the product a clearly identified developer behind it.
My recommendation comes with one condition: use it as part of a prepared selling routine, not as a magic shortcut. The strongest experience comes when I confirm the amount, guide the customer through the handoff, wait for the finished payment state, and record the sale immediately. If that workflow matches the way you work, Jim can make card acceptance feel much less cumbersome. If you need a complete retail system or the reassurance of a dedicated terminal, another option will likely serve you better.
For the right user, the central benefit is simple: less equipment without abandoning in-person card payments. That is a meaningful advantage for mobile and occasional sellers. I would install it for a small operation, test it before a busy event, and keep a backup method ready. Used with that level of preparation, Jim feels practical rather than flashy, and that is exactly why I would recommend giving it a serious try.
FAQ
What is Jim: sell & get paid instantly?
Jim: sell & get paid instantly is a marketplace app designed to help users list unwanted items, communicate with potential buyers, and arrange sales through a mobile device. The app focuses on making local or direct selling more convenient, with tools for creating listings, adding photos, describing products, and managing buyer interactions without needing a traditional computer.
How do I sell an item on Jim?
To sell an item, you generally create a listing by uploading clear photos, entering a title and description, selecting the appropriate category, and setting a price. Before publishing, it is worth checking that the condition, measurements, location, and collection or delivery details are accurate. Detailed listings usually attract more serious buyers and reduce repetitive questions.
Do I get paid instantly when an item sells?
The name suggests fast payments, but the exact timing can depend on the payment method, the transaction process, and whether the buyer has completed all required steps. Users should review the payment terms shown inside the app before accepting an offer. Never hand over an item based only on a payment screenshot; confirm that the money is visible in the official account or transaction history.
Is Jim safe to use for buying and selling?
Jim can make selling more organized, but users should still follow standard marketplace safety practices. Keep conversations within the app when possible, avoid sharing unnecessary personal information, and be cautious of buyers who pressure you to move immediately to another service. For local transactions, meet in a public place, take someone with you, and inspect payment confirmation carefully.
What fees or requirements should I know about before using Jim?
Before listing or purchasing, check the app’s current fee structure, payment rules, identity requirements, and any restrictions on prohibited or regulated products. Charges may vary depending on the type of transaction or payment option, and policies can change over time. Also confirm whether shipping, refunds, cancellations, and seller protection are available for your specific location and item category.











