

Instant Cash Advance
4.6FinanceUpdated October 2, 2026
Screenshots
Pros
- Fast application process with minimal paperwork
- Clear repayment schedule shown before accepting an advance
- Useful for covering unexpected short-term expenses
- Funds may arrive quickly after approval
- Simple interface makes account details easy to review
Cons
- Advance fees can make borrowing expensive
- Eligibility and limits may vary by applicant
- Repayment is often required within a short period
- Late payments may lead to additional charges
- Availability may depend on location and banking support
 Analysis By Mobexer
Instant Cash Advance is a finance app built around one clear promise: helping users look for fast access to funds from a phone. After spending time with it, my view is fairly simple: it is most useful as a starting point for a short-term cash request, not as a complete solution to ongoing money problems. The focused design makes the purpose easy to understand, but that same narrow focus means you need to approach every borrowing decision carefully.
The app is free to install and is published by Janssen Herman. It has reached over ten thousand installs and holds a 4.6 average from around 1,800 ratings, with 58 written reviews. Those figures suggest that people are finding the basic experience approachable, although popularity alone should never be treated as proof that a loan is affordable or suitable for every user.
What using Instant Cash Advance feels like
The first thing I noticed is that the app does not try to be a general-purpose banking dashboard. It is aimed at one task: connecting a person with an instant cash advance request. That narrow purpose is helpful when you are dealing with an urgent expense and do not want to sort through budgeting charts, investment tools, card controls, and unrelated financial features.
Its store summary presents it as a way to access fast funds through a trusted loan app, while the short description reduces the idea to “Instant Cash Advance.” In practical terms, I would treat that wording as an invitation to explore an application rather than a guarantee that money will arrive immediately. Approval, eligibility, timing, repayment terms, and the total cost are the details that matter most before accepting anything.
For a first-time user, the sensible workflow is to open the app with a specific amount and repayment plan already in mind. Do not begin by thinking, “How much can I get?” Begin with, “How much can I repay without disrupting rent, food, utilities, or existing commitments?” That small change in perspective makes the tool less tempting to use impulsively.
I also recommend reading every screen slowly, even if the process feels urgent. A fast interface can encourage quick taps, but financial agreements deserve the opposite approach. Check the amount requested, any repayment information shown, the dates involved, and the final amount you would owe. If a screen is unclear, pause instead of assuming the most favorable interpretation.
Where the app is genuinely useful
The strongest case for this app is a short-lived cash gap with a clearly understood solution. Imagine a household facing an unexpected repair just before payday. If the repair is necessary, the amount is modest, and the borrower already knows where the repayment will come from, a focused cash-advance app may be more convenient than visiting a branch or making several phone calls.
That convenience is especially relevant for people who manage most of their daily tasks on a mobile device. The app is available for Android devices running version 6.0 or later, so it can work on many older phones rather than requiring a recent handset. The content rating is Everyone, which makes the presentation broadly accessible, though adults still need to make the financial decision and understand the agreement.
Another useful scenario is comparing an urgent advance with familiar alternatives before committing. You might check whether your bank offers an overdraft option, ask an employer about an advance, or speak with a utility provider about a payment arrangement. Having this app available can make one option easier to investigate, but it should not prevent you from checking whether another route costs less.
In my experience, the best use is deliberate and occasional. I would not open it every time a nonessential purchase feels attractive. A cash advance can solve a timing problem, but it does not remove the underlying expense. If the same shortfall appears every month, the app is signaling a budget problem rather than fixing one.
The details I would inspect before requesting money
The most important part of the experience is not the button that starts an application. It is the information surrounding the offer. Before accepting, I would look for the total repayment amount, the repayment schedule, any applicable fees, and what happens if payment is late. These details determine whether “fast funds” are actually manageable.
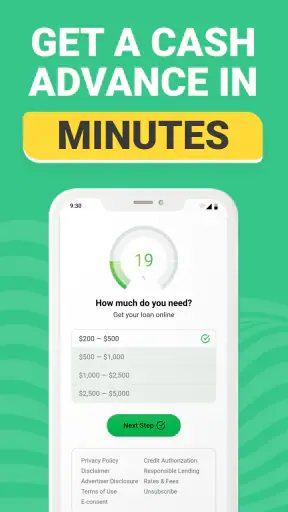
I would also check whether the amount offered matches the amount needed. Borrowing extra simply because it is available can turn a small emergency into a larger obligation. If the app presents a range of choices, I would select the smallest amount that solves the immediate problem and avoid treating the maximum as a recommendation.
A practical tip is to write the repayment date in a calendar immediately after accepting an advance. Add a reminder several days earlier and make sure the money will remain available after essential bills are covered. This is a simple step, but it prevents the common mistake of remembering the loan only when the due date arrives.
Another useful habit is to save a private note with the amount borrowed, the total to repay, and the reason for borrowing. After a few weeks, that record tells you whether the app was used for a genuine one-off emergency or whether it is becoming part of your normal spending pattern. The latter is a strong sign that a different financial solution is needed.
What it does better than ordinary alternatives
Compared with asking a traditional bank for a small personal loan, the main attraction is immediacy and focus. A bank may offer broader account services and a more established relationship, but its application process can feel excessive when the need is small and time-sensitive. Instant Cash Advance is designed around that narrower moment.
Compared with borrowing from friends or family, the app may feel more private and less socially uncomfortable. That convenience has a trade-off: a personal loan from someone you trust may have more flexible repayment expectations, while a formal advance creates a financial obligation that should be treated seriously.
Compared with using a credit card, the right choice depends entirely on the terms. A card may be more convenient for an eligible purchase, but carrying a balance can become expensive. An advance may be easier to understand if its repayment details are clearly shown, yet it is not automatically cheaper. I would compare the total cost rather than choosing based on speed alone.
Compared with payday-style borrowing, the app’s modern mobile presentation may feel less intimidating, but a cleaner interface does not change the economics of the agreement. The question is always how much you receive, how much you repay, and how quickly the obligation ends. A polished screen should never replace that calculation.
The main weakness: speed can hide the need for caution
My biggest concern is not that the app focuses on cash advances; it is that the category itself can make urgency feel normal. When someone is stressed about money, a quick application can seem like the obvious answer. The danger is accepting an offer before checking whether the repayment will create another shortage later.
The app also cannot solve an income problem through convenience. If your regular expenses already consume nearly everything you earn, another advance may only move the pressure forward. In that situation, I would first contact creditors, review subscriptions, ask about bill extensions, or build a basic weekly spending plan. Those steps are less exciting, but they address the cause rather than the symptom.
There is also a psychological trade-off in using a dedicated borrowing tool. Because it is always available on a phone, it may be easier to return to than a slower alternative. I would remove the temptation to browse casually and open it only when I have a defined need. A finance app should support a decision, not encourage one.
Users should also remember that an app’s rating reflects the experience of people who reviewed it, not the affordability of every offer. Instant Cash Advance currently shows a 4.6 average, which is encouraging for usability, but it does not tell me whether a particular borrower will receive suitable terms. Personal eligibility and the details presented during the application remain more important than the public score.
Who should consider it, and who should skip it
I think the app is best suited to an adult who has a one-time, clearly defined cash shortage, understands the repayment plan, and has dependable income arriving soon. That person should be comfortable comparing the advance with a bank option, an employer advance, a payment arrangement, or another lower-cost alternative.
It may also suit someone who values a mobile-first process and wants to investigate an advance without handling a broad banking app. The current version is 1.7.4, and the Android requirement of 6.0 or later keeps the technical barrier relatively low for users with older devices.
I would advise skipping it if you are looking for long-term debt consolidation, regular help with groceries, or money for discretionary purchases. It is also the wrong first choice if you do not know exactly how repayment will fit into your next budget. In those situations, a nonprofit debt adviser, a bank conversation, an employer resource, or a structured budget review is likely to be more useful.
Anyone who is under the applicable legal borrowing age should not use a financial product simply because the app carries an Everyone content rating. That label describes the general presentation, not permission to enter a loan agreement. Adults should make sure they understand the terms and local requirements before proceeding.
A careful way to use the app
My preferred approach is a five-step check. First, define the emergency and the exact amount required. Second, compare the advance with at least one alternative. Third, read the repayment information and calculate the real total. Fourth, confirm that essential bills remain covered after repayment. Fifth, set reminders and keep a record of the agreement.
- Decide whether the expense is urgent, necessary, and temporary.
- Request no more than the amount needed to handle it.
- Review the complete repayment obligation before accepting.
- Check the due date against your actual income and bills.
- Reassess afterward so the same shortfall does not become a habit.
This workflow is more important than any single convenience feature because it puts control with the borrower. It also answers a question many people have after installing a cash-advance app: how do I avoid turning a quick fix into repeated borrowing? The answer is to use the app only within a written plan and to treat a second request as a warning that the underlying budget needs attention.
If you are wondering whether the app is free, it is free to install. That does not mean an advance itself is free, so I would never confuse the download price with the cost of borrowing. The amount owed and the applicable terms shown during the process are what should guide the decision.
If you are wondering whether approval is assured, I would not assume that it is. A loan application still depends on the provider’s process and the information requested. The store summary describes access to fast funds, but responsible use means checking the actual result presented to you instead of planning around money before it is available.
If you are wondering whether it replaces a bank, my answer is no. It is a focused finance app for exploring a cash advance, while a bank account, credit union, employer program, or community assistance service may offer a better answer for broader or recurring needs. The best option depends on cost, timing, flexibility, and your ability to repay.
My final view
Instant Cash Advance is a convenient, narrowly focused tool, but its value depends more on disciplined borrowing than on speed. I like that it gives users a direct way to investigate a short-term advance, works on older Android versions, and avoids burying its purpose under unrelated financial features. The free installation and accessible presentation make it easy to try.
Still, I would recommend it only to someone with a temporary need and a realistic repayment plan. The app should not be treated as spare income, an emergency fund, or a substitute for fixing recurring financial pressure. If you compare alternatives, read the full terms, borrow the minimum, and set a repayment reminder, it can be a practical option to consider.
My recommendation is therefore cautious but positive: use it as one part of a comparison, not as the automatic answer. For a one-off cash gap, it may save time. For ongoing money trouble, I would choose advice, restructuring, or a lower-cost source of support instead.
FAQ
What is Instant Cash Advance, and how does it work?
Instant Cash Advance is a financial app designed to help eligible users request a short-term cash advance through their mobile device. After creating an account, you typically provide personal, employment, and banking information so the service can assess eligibility. If approved, the requested amount may be transferred to your linked bank account, although approval, timing, and available amounts vary by user and provider.
Is Instant Cash Advance a legitimate and safe app to use?
Before using Instant Cash Advance, download it only from an official app store and carefully verify the developer, privacy policy, permissions, and customer-support details. A legitimate financial app should clearly explain its fees, repayment terms, data practices, and lending partners. Avoid applications requesting unnecessary permissions or upfront payments, and never share account credentials outside the secure in-app process.
How much money can I borrow, and how quickly will I receive it?
The amount available through Instant Cash Advance depends on factors such as your eligibility, income, account history, location, and the provider’s policies. Some users may receive funds quickly after approval, while others may experience delays caused by bank processing, verification, weekends, or holidays. The app should display the exact amount, delivery method, and estimated arrival time before you accept.
What fees, interest, and repayment terms should I expect?
Cash advances can involve service charges, subscription fees, expedited-transfer fees, interest, or other costs, depending on the specific product and your location. Review the total repayment amount, due date, annual percentage rate when applicable, and consequences of late payment before confirming a request. Never assume that “instant” or “no credit check” means the advance is free.
What information and permissions does Instant Cash Advance require?
To evaluate an application and deliver funds, Instant Cash Advance may request information such as your identity details, income, employment, bank account, and contact information. Some features may also request device or notification access, but permissions should be relevant and clearly explained. Read the privacy policy, limit unnecessary access, and confirm how your data is stored, shared, and deleted.











