

Instant Cash Advance: CashHoop
4.6FinanceUpdated October 5, 2026
Screenshots
Pros
- Simple application process with a clear
- user-friendly interface.
- May provide quick access to funds for eligible users.
- Loan details and repayment terms are presented before acceptance.
- Useful for covering unexpected short-term expenses.
- Can be accessed from a mobile device without visiting a branch.
Cons
- Availability and loan terms may vary by location and eligibility.
- Fees and interest can make borrowing expensive.
- Repayment deadlines may be short for some users.
- Late payments could lead to additional charges or financial stress.
- Requires sharing personal and financial information during registration.
 Analysis By Mobexer
CashHoop is the kind of finance app that catches your attention when a routine expense suddenly becomes urgent. Its focus is cash advances and tax filing, so it is aimed at people who need to deal with a short-term money problem rather than manage a full household budget. I spent time looking at how it fits into that situation, and my main impression is that the app is most useful when you approach it as a quick financial application tool, not as a replacement for a bank account or a long-term debt plan.
That distinction matters. The promise of getting help in minutes sounds simple, but financial applications usually depend on accurate personal information, identity checks, eligibility decisions, and the details of the request. A smooth experience starts before tapping the application button. If you are prepared, CashHoop can feel direct and approachable. If you open it while rushing, with incomplete information or an unstable connection, the process can feel much less instant than the store wording suggests.
Getting past the points where a cash advance app can stall
CashHoop is a free finance app from Biskup Apps, with an Everyone content rating and support for Android 7.0 and later. It has built a sizeable audience, with more than a million installs and an average rating of 4.6 from roughly 26 thousand ratings. Those figures suggest that the basic idea is resonating with many users, although popularity should not be confused with approval for every applicant or with a guarantee that every request will be completed in the same way.
The first place users are likely to get stuck is the transition from browsing to applying. A cash advance request is more sensitive than ordering a product or trying a calculator. You may need to enter personal and financial details carefully, and even a small mismatch can create extra friction. My practical advice is to use your legal name and current contact information consistently, check every digit before moving forward, and avoid switching between several different versions of your details simply because one looks more convenient.
A second sticking point is expectation. “Instant” describes the intended speed of the service, not an unconditional promise that money will appear immediately for every person. An application still has to go through its own process. If you are considering CashHoop for an unexpected bill, leave yourself enough time to explore another payment arrangement as a backup. I would never wait until the final few minutes before a payment is due and assume that an advance app will solve everything.
The app is also not the right place to make a rushed borrowing decision. Before submitting anything, I would write down the bill, the amount needed, and the date the money would need to be repaid or covered. That simple step exposes an important trade-off: solving a small emergency today may create a larger problem later if the repayment plan does not fit your next income cycle. CashHoop can help with access, but it cannot make an unaffordable obligation affordable.
Prepare the phone before starting
Setup friction is often blamed on the app when the real problem is the device or connection. Before beginning, I would update the application if an update is available, close other apps, and use a reliable Wi-Fi or mobile connection. CashHoop is currently listed as version 1.0.15, and it can run on Android devices using version 7.0 or newer. If the phone is older, heavily cluttered, or short on storage, basic preparation can prevent a form from freezing halfway through.
I would also make sure the phone has enough battery and that its date and time are set correctly. These sound like minor details, but financial forms are more frustrating when a session expires or the device changes networks during submission. If a page takes longer than expected, avoid repeatedly tapping the same button. That can create duplicate attempts or simply make it harder to tell whether the request has moved forward.
Another useful check is notification access at the phone level. If CashHoop sends an important status message through the app or the device notification system, a blocked notification setting can make you think nothing happened. I would review the app’s notification setting without enabling anything unrelated, then check inside the app itself for a status or message area. This is a safer troubleshooting step than uninstalling immediately, especially if you have already entered information.
Privacy should be part of setup too. Because this is a finance application, I would read each screen rather than granting access automatically. Only provide information when you understand why it is being requested and where you are in the process. I would avoid completing an application on public Wi-Fi, on a shared phone, or while someone else can easily see the screen. Convenience is useful, but financial details deserve the same care as online banking information.
A calmer workflow for taxes and urgent bills
CashHoop has two noticeably different use cases: filing taxes and dealing with an unexpected bill. I would not treat them as one combined task. Tax preparation rewards patience and organized records, while a cash advance request is usually driven by time pressure. Separating the two helps prevent a hurried borrowing decision from becoming mixed up with a tax task that needs careful review.
For a tax-related workflow, gather your documents first and keep the figures visible while entering them. Do not rely on memory for income or deductions. If you are interrupted, save your work only through the app’s own controls and note where you stopped. When you return, review the previous entries rather than assuming that a partially completed screen was accepted. The most valuable “advanced” habit here is not a hidden button; it is creating a clean paper trail before you begin.
For an urgent bill, start with the exact amount and the reason you need it. Then compare that amount with the amount you can realistically handle later. If the bill is from a utility, landlord, medical provider, or service company, contact that organization as well. A payment extension, split payment, or hardship arrangement may be less expensive than borrowing. CashHoop is worth considering when speed and access are the main obstacles, but it should be one option in a short decision process, not the only option.
If the app appears to stop during a request, first wait briefly and check whether the screen or status has changed. Next, confirm the connection, reopen the app, and look for an existing application status before starting over. This sequence is important because repeating a submission without checking can cause confusion. If the app returns you to an earlier step, compare the information carefully and continue only when you know whether the previous attempt was saved.
Taking screenshots of non-sensitive confirmation screens can help you remember what happened, but I would not capture passwords, full account details, or identity documents unless there is a clear and necessary reason. Keep any notes private. If you need support, describe the exact screen, the time of the problem, and whether the app displayed an error. A precise report is more useful than saying only that “it does not work.”
When restarting the app will not solve the problem
Some failures are outside CashHoop. A bank-side delay, an incorrect account detail, a carrier outage, or a temporary identity-verification issue can look like an application problem. Restarting the app may refresh the screen, but it cannot correct information held by another service. This is why I prefer checking the status and the details already submitted before clearing app data or reinstalling.
Reinstallation should be a last resort when you have an unfinished financial application. It may remove local session information, and you may have to sign in or repeat steps. If the app is crashing, try closing it normally, restarting the phone, and checking the available storage first. If the trouble continues, record the app version, Android version, and the action that caused the failure. Those details make troubleshooting more focused without guessing at a cause.
There is also a difference between technical trouble and an eligibility outcome. If an application is not approved or does not proceed, repeatedly submitting it is unlikely to improve the situation and may make your financial planning more stressful. I would treat the result as a signal to compare alternatives, review the amount requested, and contact the relevant support channel. Never pay an unrelated person who claims they can unlock an advance, and never share security codes with someone who contacts you unexpectedly.
CashHoop is less suitable for people who want detailed spending categories, automatic budgeting, investment tracking, or a broad view of their financial life. A traditional banking app is usually better for account history and transfers, while a dedicated budgeting tool is better for planning recurring expenses. Someone with stable savings may also prefer using an emergency fund, because that avoids the cost and repayment pressure associated with borrowing. The app’s strength is its focused purpose, and that same focus limits its value outside urgent cash access and tax-related work.
Who will benefit and who should look elsewhere
I can see CashHoop working well for an adult who needs a straightforward place to explore a cash advance and is willing to read the terms carefully. It may also appeal to someone who wants tax filing and short-term financial help in one app rather than searching through several unrelated services. The free download lowers the barrier to trying it, and the Everyone rating makes it broadly accessible from a content perspective.
However, “free” should be read as the cost of downloading the app, not as a promise that every financial service connected with it will have no cost or obligation. Before accepting anything, I would examine the amount received, the amount to be repaid, the timing, and any applicable conditions shown during the process. If those details do not fit your budget, stop there. A fast application is not a good deal simply because it is easy to begin.
I would skip CashHoop if I needed a guaranteed same-day solution, if I could not repay an advance without missing another essential bill, or if I was uncomfortable entering sensitive financial information into a mobile application. I would also choose a tax specialist or a more established tax-focused service when my return is complicated enough that a quick mobile workflow might not provide the guidance I need. The better alternative depends on the problem: bank support for account issues, the biller for payment relief, and professional tax help for complicated filing situations.
One practical advantage of using a focused app is that it can reduce the number of steps between recognizing a problem and exploring a possible solution. The trade-off is that focus can make it tempting to overlook the wider financial picture. I recommend opening CashHoop only after deciding what outcome you need. If the goal is to cover one specific bill, keep that bill and your repayment plan in front of you. If the goal is filing taxes, prepare the documents and review the final entries separately.
My final view after weighing speed against responsibility
My overall view of CashHoop is cautiously positive. It is a focused finance app from Biskup Apps that makes sense for people exploring cash advances or tax filing from an Android phone. Its strong user response, free availability, and simple purpose make it worth considering when an unexpected expense creates pressure. I especially like the idea of having a clear starting point instead of hunting through unrelated financial apps.
My caution is equally important: the app cannot remove the normal responsibilities of borrowing. Approval, timing, repayment, information accuracy, and outside service issues all matter. The best experience will come from a prepared user who checks the details, protects personal information, and keeps a backup plan. The worst experience would be opening it in a panic, submitting incomplete information, and assuming that an instant request automatically means instant relief.
For me, CashHoop earns a place on the shortlist for a narrow situation: a short-term financial need where I have already considered cheaper or less risky alternatives and understand what I can repay. It is not a complete money-management system, and it is not a substitute for savings, a bank, a biller’s hardship program, or professional tax advice. Used with that perspective, it can be a practical tool. Used as a last-second promise, it is likely to create more questions than it answers.
FAQ
What is Instant Cash Advance: CashHoop, and how does it work?
Instant Cash Advance: CashHoop is a financial app designed to help eligible users request a short-term cash advance through their mobile device. After creating an account, you generally provide personal and financial information, review the available offer, and complete the requested verification steps. Approval, advance amounts, fees, and delivery times can vary, so read the terms carefully before accepting any offer.
Is CashHoop a legitimate loan provider or a loan-matching service?
Before using CashHoop, it is important to understand exactly what role the app plays. Some cash advance applications provide financial services directly, while others connect users with third-party lenders or providers. The company responsible for your offer, the applicable fees, repayment schedule, and privacy practices should be clearly identified in the app’s terms and disclosures. Do not proceed if essential information is unclear.
How much money can I receive through CashHoop, and how quickly is it delivered?
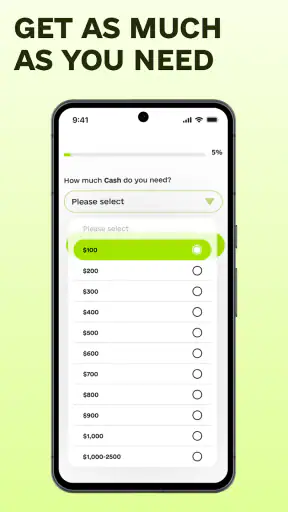
The amount available through CashHoop depends on factors such as your eligibility, income information, account history, and the provider’s approval criteria. An advertised “instant” advance does not always mean immediate access to funds, because identity checks, bank processing, weekends, and external transfer times may cause delays. Review the final offer for the exact amount, delivery method, and expected arrival time.
What fees, interest, and repayment conditions should I check before accepting an advance?
Users should carefully examine the total cost of any CashHoop advance before confirming it. Depending on the offer, costs may include service charges, subscription fees, transfer fees, interest, or other applicable charges. Check whether repayment is automatic, when the payment is due, and what happens after a failed or late payment. Only accept an advance if the complete repayment amount fits your budget.
Is CashHoop safe to use, and what personal information does it require?
CashHoop may request sensitive details such as your name, contact information, identification data, income, employment information, and bank account details to assess eligibility and process an advance. Before registering, review the privacy policy, permissions, data-sharing practices, and security information. Download the app only from an official app store, use a secure connection, and avoid sharing account credentials or verification codes with anyone.











