

Instacart Shopper Rewards
4.3FinanceUpdated October 2, 2026
Screenshots
Pros
- Rewards can add extra value to regular shopping activity.
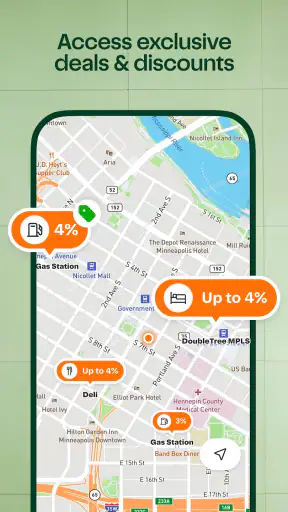
- The program may offer personalized savings and partner benefits.
- Progress and available rewards are easy to monitor in the app.
- Useful for shoppers who already use Instacart frequently.
- Digital rewards avoid the need to carry physical coupons or cards.
Cons
- Reward availability and value can vary by location and account.
- Some benefits may require meeting spending or activity conditions.
- Rewards may expire if they are not used within the stated period.
- The program does not guarantee lower prices on every order.
- Terms and eligible purchases can change without much notice.
 Analysis By Mobexer
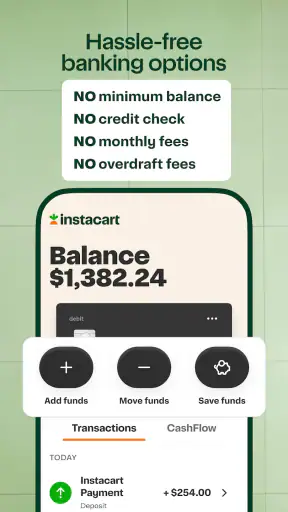
Instacart Shopper Rewards is a finance app built for people who shop and deliver through Instacart. I approached it less like a general banking tool and more like a work companion: something to check before a shift, use while managing earnings, and keep organized between deliveries. Its main idea is straightforward—give shoppers a debit-card-focused way to handle money connected with their work—but the value depends heavily on whether that matches your routine.
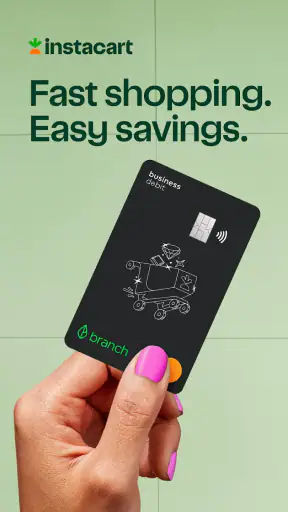
The app is developed by Branch Messenger, and its store summary points to a new debit card. That immediately sets the right expectation. This is not an all-purpose budgeting suite, an investing platform, or a replacement for every financial service on your phone. It is aimed at shoppers who want their work-related money and card activity in one place, with less switching between unrelated apps.
How I used it as a shopper-focused money tool
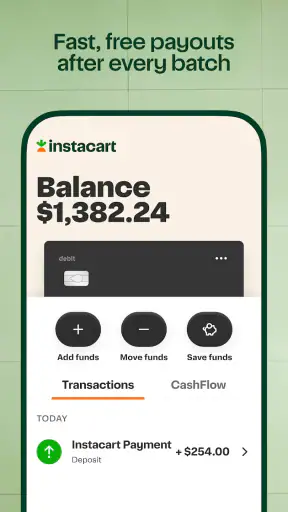
My baseline workflow would be simple: open the app before going online, check the available balance, review recent activity, and make sure the card is ready for the day’s spending. After working, I would return to confirm that the latest movement appeared correctly and separate work-related spending from everything else. That habit matters because delivery work can produce many small transactions, and relying on memory makes it surprisingly easy to lose track.
The strongest part of this approach is the clear connection between the app and the shopper role. When an app is designed around a specific kind of work, the useful question is not “Can it do everything my bank does?” but “Can I complete my regular workday without unnecessary detours?” For an Instacart shopper, that may mean checking card activity during a break, keeping the work card distinct from a personal account, or confirming that money is available before buying something needed on the road.
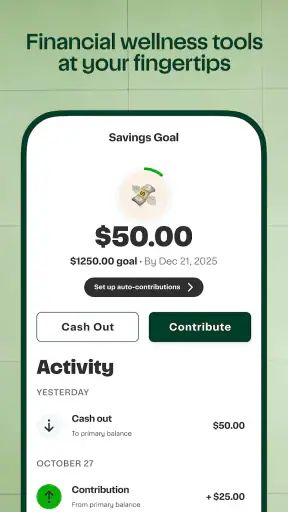
I would not treat it as a complete financial command center. A traditional bank app may still be better for long-term savings, bill management, joint accounts, detailed statements, or a broad range of account types. The practical advantage here is focus. If your main need is a shopper-oriented debit card experience, a focused tool can feel less cluttered than a full banking app.
One everyday scenario shows where it fits. Imagine starting a busy afternoon with fuel, parking, and a quick meal likely to appear in your spending. Instead of mixing those purchases with your household account, you can use the shopper-oriented card and review the activity later. That does not automatically create a complete tax record or replace careful bookkeeping, but it gives you a cleaner starting point for understanding what happened during the shift.
That distinction is important. I would still save receipts and follow whatever record-keeping method works for your situation. The app can help you see transactions; it should not be treated as professional tax advice or as proof that every work expense has been categorized correctly. Experienced shoppers will get more from it when they pair the app with a repeatable note-taking habit rather than expecting the software to do all the organization.
What to check before relying on the card
Before making it part of my daily routine, I would confirm the account setup, card status, available balance, and the exact destination of any money I expect to use. These checks sound basic, but they prevent the most frustrating kind of problem: discovering during a shopping run that the payment method is not ready for the purchase you planned to make.
I would also spend a few minutes learning where recent activity appears and how quickly I can recognize a transaction. The best workflow is not to inspect every screen repeatedly. It is to know the two or three places that matter—balance, activity, and card controls if available—and use them consistently. That is a small efficiency gain, but it becomes meaningful when repeated across many shifts.
Settings deserve attention because a work card is easier to manage when its notifications and security choices match your habits. I would review alert preferences rather than accepting every default automatically. Too many alerts can become background noise, while too few can make unusual activity harder to notice. The right choice depends on how often you check the app and whether your phone is usually with you during deliveries.
I would also keep the app updated. The current version is 2026.8.2, and the minimum operating-system requirement is Android 10. That makes compatibility worth checking before installing on an older phone. A shopper who depends on a device during work should avoid discovering an operating-system issue at the start of a shift, especially if the phone is already handling navigation and delivery communication.
Another useful preparation step is deciding what the card is for. I would choose one clear purpose, such as workday purchases or money connected with shopping, and avoid gradually turning it into an unstructured second wallet. Clear boundaries make the activity list easier to read and reduce the temptation to use the account for unrelated spending that complicates later review.
Repeatable habits that make the experience faster
Experienced users rarely become faster by tapping quickly. They become faster by repeating the same sequence. My preferred pattern would be: check the balance before going online, use the card only for the intended category of spending, glance at activity after the shift, and record anything that needs follow-up while the details are still fresh.
This is more useful than opening the app randomly throughout the day. A scheduled check reduces interruptions and gives each review a purpose. The exception is a purchase that looks unfamiliar or a balance that does not match expectations. In those cases, I would investigate immediately rather than waiting until the end of the week.
A second pattern is to keep the app near the tools used during a shift. On a phone, that may mean placing it where it is easy to reach without searching through several screens. I would not recommend creating complicated automation or assuming that a shortcut exists unless the device and app visibly support it. The simple win is reducing friction between finishing a purchase and confirming that it is recorded as expected.
A third pattern is to review activity in batches. If several ordinary purchases appear, I would scan them together and flag only the items that need attention. That keeps the app from becoming a source of constant checking while still preserving control. It also helps reveal habits—such as repeated small purchases—that are easy to overlook one at a time.
For shoppers who use more than one financial service, I would decide which app is the source of truth for each task. Instacart Shopper Rewards can be the place for its debit-card activity, while a separate bank or budgeting tool can handle broader household planning. Trying to force every financial question into this app is likely to create frustration; assigning it a specific job is more efficient.
One non-obvious trade-off is convenience versus separation. Keeping shopper-related spending apart can make review easier, but it also creates another balance to monitor. If you already struggle to track multiple accounts, the extra separation may not be worth it. In that case, a conventional bank account with stronger all-in-one budgeting may suit you better, even if it is less tailored to the shopper experience.
Where the focused design reaches its limits
The app’s specialization is both its appeal and its boundary. Someone looking for a broad personal-finance system may find the experience too narrow. A shopper who needs investment tools, extensive budgeting categories, complex transfers, or family banking features should compare it with a conventional financial institution before making a switch.
I would also be cautious about treating the debit card as a universal emergency solution. A card connected with work can be useful, but every shopper should have a backup payment method and enough awareness of their available funds to avoid being stranded during a shift. That is not a criticism unique to this app; it is a sensible rule whenever one card becomes part of your work routine.
Another limitation is that a clean transaction list does not automatically explain the business meaning of each purchase. The app may show activity, but the shopper still has to decide whether a cost was personal, work-related, mixed, or worth documenting. For anyone who needs detailed expense reporting, a dedicated spreadsheet or bookkeeping app may remain necessary.
Privacy and security habits matter just as much as the interface. I would use a device lock, avoid sharing account access, and review unexpected activity promptly. I would also be careful when checking financial information in public places or on a phone being used by other people. The app can support a safer routine, but it cannot replace the user’s judgment.
Support expectations should be realistic as well. A focused app can simplify the most common shopper tasks, but unusual account or card situations may still require patience and careful reading of the available instructions. I would keep essential account details accessible through secure means and avoid assuming that every problem can be solved instantly from the main screen.
The audience fit is therefore quite specific. This is a strong candidate for an active Instacart shopper who wants a dedicated debit-card experience and is comfortable managing one more finance app. It is less convincing for someone who does not shop through Instacart, someone seeking a full replacement for a traditional bank, or someone who wants automatic financial planning without maintaining any personal habits.
How it compares with ordinary alternatives
Compared with a normal bank app, Instacart Shopper Rewards feels more purpose-built around the shopper context. A bank usually offers wider financial coverage, but that breadth can mean more menus and less emphasis on the particular rhythm of delivery work. If your priority is general banking, the conventional option probably wins. If your priority is keeping shopper-related card activity distinct, the focused approach has a practical advantage.
Compared with a prepaid spending card or a general digital wallet, the important difference is the connection to the Instacart shopper use case. A generic wallet may be perfectly adequate for occasional purchases, but it does not necessarily feel organized around the needs of someone earning through shopping and delivery. The choice comes down to whether that specialization improves your routine enough to justify another account.
Compared with a budgeting app, this tool should be viewed as a transaction and card companion rather than a complete planning system. A budgeting app may offer categories, goals, trends, and broader account aggregation. Those features are useful when planning household finances. This app is more relevant when the immediate concern is using and reviewing a shopper-oriented debit card without mixing it into every other financial decision.
That comparison also answers a common practical question: should you close your existing bank account? In my view, no—not simply because this app is convenient for shopper activity. Keeping a primary bank relationship can provide flexibility for bills, savings, and backup access. The better approach is to give each service a defined role and see whether the extra step genuinely saves time.
The app is free, which lowers the barrier to trying it. Still, “free” does not mean every financial decision becomes costless or risk-free. I would read the applicable card and account terms carefully, especially before changing how I receive or spend work-related money. The right decision depends on the complete arrangement, not just the download price.
My verdict after building a routine around it
Instacart Shopper Rewards makes the most sense when you want a finance app that stays close to the daily realities of Instacart shopping. I like the focused purpose: check the balance, use the debit card for a defined job, and review activity without burying that information inside a much larger financial dashboard. The experience rewards users who create a consistent workflow instead of expecting the app to manage every part of their money.
Its public reception is encouraging, with a 4.3 average from around 549 ratings and more than 100 thousand installs. Those figures suggest that the concept has found an audience, while the app’s Everyone age rating keeps it broadly accessible. I would treat those signals as a reason to investigate, not as a substitute for checking whether the card and account structure fit your own needs.
My recommendation is strongest for active shoppers who value separation, quick checks, and a repeatable workday routine. I would skip it if you are looking for a full-service bank, advanced household budgeting, or a single app that handles every financial goal. In those cases, a traditional banking app or dedicated budgeting tool is likely the better foundation.
The best way to judge it is to give it a defined trial role rather than moving everything at once. Use it for the shopper-related workflow, monitor how often you actually open it, and see whether reviewing activity becomes easier or merely adds another task. If the separation helps you understand your work spending and the debit card fits your routine, the focused design earns its place. If it creates more account management than clarity, keeping your usual financial setup may be the smarter choice.
For me, the lasting lesson is simple: the app works best when paired with a habit, not used as a substitute for one. Check before work, review after work, keep records that matter, and maintain a backup payment option. Used that way, Instacart Shopper Rewards is a practical companion for the right shopper—not a universal answer to personal finance.
FAQ
What is Instacart Shopper Rewards?
Instacart Shopper Rewards is a benefits program designed for eligible Instacart shoppers. It may provide access to discounts, savings, partner offers, or other perks connected with shopping and working on the platform. The exact rewards can depend on your location, shopper status, and current program rules, so it is important to review the terms shown in the app before relying on a particular benefit.
Who can use Instacart Shopper Rewards?
The program is generally intended for people who shop and deliver orders through Instacart, but eligibility may not be identical for every shopper. Requirements can vary by country, state, market, account type, and activity level. After signing in, check the rewards section or official eligibility information to see whether your account qualifies and which offers are currently available to you.
Is Instacart Shopper Rewards free to join?
In most cases, accessing a shopper rewards program does not require a separate subscription fee, although some individual offers may have their own conditions, exclusions, or costs. Before activating a benefit, read the complete offer details carefully. Pay particular attention to expiration dates, minimum purchases, participating merchants, taxes, and whether a reward is automatically applied or requires a code.
How do I redeem rewards in Instacart Shopper Rewards?
Redemption depends on the specific reward. Some benefits may be claimed directly from the app, while others can require tapping an activation button, following a partner link, entering a promotional code, or presenting account information. Open each offer before using it and confirm the instructions, expiration date, and eligibility requirements. Taking a screenshot of important terms can also help avoid confusion later.
Is Instacart Shopper Rewards available everywhere?
Availability is not necessarily universal. Rewards and partner benefits can differ according to your location, local regulations, shopper classification, and changes made by Instacart or participating partners. Even if another shopper has access to a particular offer, it may not appear on your account. Keep the app updated, enable account notifications if desired, and check the official program information for the most accurate details.











