

Grant Cash Advance
4.8FinanceUpdated October 5, 2026
Screenshots
Pros
- Simple application process with minimal paperwork required.
- Useful for handling unexpected expenses between paychecks.
- Loan terms and repayment details are presented clearly.
- Funds may arrive quickly after approval
- depending on eligibility.
- Accessible to users who may not qualify for traditional bank loans.
Cons
- Interest and fees can make the total repayment expensive.
- Approval and loan amounts depend on personal eligibility checks.
- Short repayment periods may be difficult for some borrowers.
- Late payments could lead to additional charges or collection activity.
- Availability and terms may vary by location and lender.
 Analysis By Mobexer
I approached Grant Cash Advance as a short-term finance tool rather than a general budgeting app, and that distinction matters. Its central appeal is speed: when an unexpected bill arrives and waiting for a conventional loan is not practical, the app is designed to help users explore a cash advance without a traditional credit-check process. My overall view is positive but cautious. It can be useful for a narrow, urgent need, yet it should not be treated as a replacement for an emergency fund, a bank account, or a long-term borrowing strategy.
Developed by Kikoff Inc., this free finance app has built a substantial audience, with more than a million installs and an average rating of 4.8 from roughly 134 thousand ratings. Those figures suggest that many people find the experience approachable and worthwhile, although popularity should never be confused with affordability for every individual. I found the strongest case for it is simple: someone needs to understand whether a cash advance may help before committing to a more complicated borrowing route.
How Grant Cash Advance works in everyday use
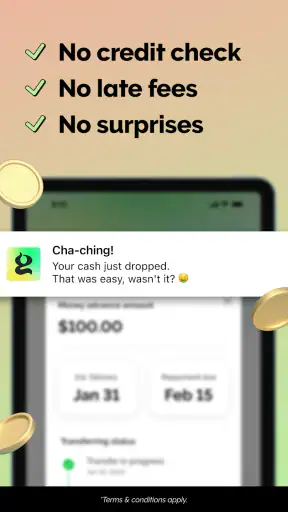
The first thing I would tell a friend is to think of Grant Cash Advance as a decision point, not automatic free money. The store summary highlights cash access without a credit check and without interest, but a careful user still needs to read every screen before accepting anything. “No interest” is an important distinction from many payday-style products, but it does not remove the need to understand eligibility, repayment expectations, timing, or any conditions shown during the application.
The app’s free download and Everyone content rating make it easy to try without an upfront purchase. It runs on Android 7.0 or later, which keeps it accessible to people using older compatible phones. The current version is 2.67.1406, so I would still keep the app updated before starting a financial request. Updates can matter more in a finance app than in a casual utility because account access and transaction flows need to remain dependable.
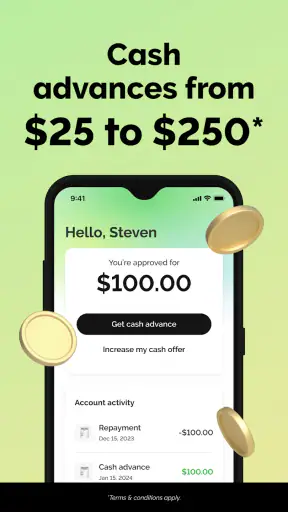
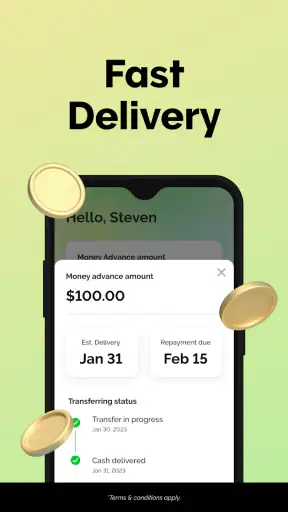
In practical terms, the useful workflow is to open the app when a specific shortfall appears, review the available advance information, and compare the proposed arrangement with the date money will actually be available. For example, imagine a utility bill falls due before payday. A sensible user would first write down the bill amount, the next confirmed income date, and the amount that can be repaid without making the following week difficult. Only then would I use the app to examine whether the advance fits that gap.
That small preparation step is more valuable than it sounds. It prevents the common mistake of borrowing the maximum simply because it appears available. A cash advance should solve a defined problem, not become extra spending room. I would also avoid starting an application while distracted, travelling, or rushing through a checkout line. Financial decisions deserve enough attention to inspect the final terms and save any confirmation details.
The strongest reason to consider it
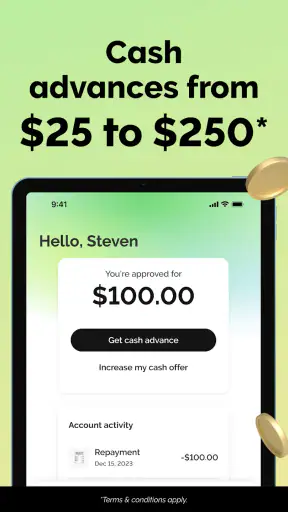
The clearest strength is accessibility. Traditional borrowing can involve a credit review, a lengthy application, or a level of paperwork that feels disproportionate when the need is modest and temporary. Grant Cash Advance presents itself as a simpler alternative for people who may not want a conventional credit-based route. That does not guarantee approval or suitability, but it makes the app relevant to users who are mainly looking for a quick way to assess an emergency cash option.
The no-interest positioning is another meaningful advantage when compared with many familiar short-term borrowing products. Interest can make a small advance harder to predict, especially when a user is already working with a tight budget. A clearer repayment picture is easier to plan around. Still, I would not interpret the phrase as permission to skip the fine print. A user should distinguish interest from any other possible obligation or condition presented in the app before proceeding.
I also like that the app’s purpose is focused. It is not trying to be a full investment platform, a banking replacement, and a credit education course at the same time. For someone who arrives with one immediate cash-flow question, that focus can reduce the mental load. The experience is most useful when the user already knows why they are opening it and what outcome they need.
Its public reception reinforces that the basic experience works for a large number of people. The app has around 8.8 thousand written reviews alongside its much larger rating total, and the overall average is 4.8. I treat that as encouraging evidence about usability, not as proof that every applicant will receive the same result. Finance apps can feel excellent to one person and unsuitable to another because eligibility, repayment capacity, and urgency vary so much.
Where it fits beside ordinary alternatives
Compared with asking a bank for a personal loan, Grant Cash Advance may feel less burdensome for a small, immediate need, particularly for someone who wants to avoid a traditional credit-check process. A bank may be the better choice when the amount is larger, the repayment period needs to be longer, or the borrower wants a more established relationship with a financial institution.
Compared with a credit card, the app may be more attractive to someone who does not want to add a revolving balance or pay interest. A credit card can still be more flexible for planned purchases, recurring expenses, or situations where repayment timing is uncertain. The right comparison is not simply “which one is faster?” but “which option creates the least pressure after the emergency has passed?”
Compared with a payday loan, the app’s no-interest message is potentially reassuring, because high borrowing costs are a major danger in that category. However, I would still compare the complete obligation rather than relying on labels. A product can be cheaper than a payday loan and still be the wrong decision if repayment lands before the next stable income arrives.
Compared with borrowing from a friend or family member, Grant Cash Advance offers privacy and a formal digital process. Personal borrowing may cost less, but it can affect relationships and create uncomfortable conversations. I would choose based on both financial consequences and personal circumstances, not on embarrassment or convenience alone.
Important limitations before requesting money
The biggest weakness is that speed can encourage impulsive borrowing. When an app is designed around urgent access, the user may focus on getting funds and overlook the second half of the decision: how the repayment will affect rent, food, transportation, or other fixed expenses. The product may be convenient, but convenience is not the same as affordability.
I would also be careful with the phrase “no credit check.” That feature may make the service appealing to people with limited or damaged credit histories, but it should not be read as a guarantee that everyone qualifies. It also does not mean the app can ignore a person’s ability to repay. Eligibility and the amount available can depend on the process shown inside the app, so expectations should remain realistic.
Another limitation is that this is not the right tool for a recurring deficit. If someone needs an advance every pay cycle to cover ordinary living costs, the immediate solution may be masking a deeper budget problem. In that situation, a nonprofit debt adviser, a bank account review, a spending plan, or a conversation with creditors could be more useful than repeatedly seeking short-term cash.
The most important trade-off is simple: faster access can solve today’s gap while making the next income date tighter. I would write down the repayment amount and date before accepting anything, then subtract it from the money that will be available after essential bills. If that calculation leaves no room for groceries, transport, or another predictable expense, I would stop and look for a different option.
Three practical habits that improve the experience
First, use the app only after separating an emergency from a want. A medical expense, necessary travel, or an overdue household bill deserves a different level of consideration from an optional purchase. This sounds obvious, but the app’s convenience makes that distinction worth making deliberately. I would name the expense in a note before opening the application and refuse to borrow more than that specific need.
Second, check the timing rather than focusing only on the amount. A smaller advance arriving at the wrong moment can be more damaging than no advance at all. Look at when the obligation must be repaid and what other automatic payments are scheduled around that date. This is a useful workflow because it turns a vague feeling of urgency into a calendar decision.
Third, keep a record of the final arrangement. I would save the confirmation screen or write down the repayment details immediately, using a private location on the phone. That makes it easier to check whether the transaction matches expectations later and helps prevent the advance from disappearing into ordinary spending. This habit is especially useful when several bills are competing for attention.
A fourth habit is to compare the app with the least expensive realistic alternative before accepting. That might be delaying a nonessential purchase, asking a provider for a payment arrangement, using an existing savings balance, or choosing a conventional product with terms that better match the situation. Grant Cash Advance is most valuable when it is one considered option, not the first button pressed whenever money feels tight.
Who will benefit most from it
I think the best audience is an adult who has a clearly defined, short-lived cash-flow problem, expects dependable income, and wants to investigate an option that does not rely on a conventional credit check. The app may also suit someone who values a digital process and prefers not to discuss a temporary shortfall with friends or family. For that person, the focused design and free access make it a practical app to keep available.
It is less suitable for anyone whose income is unpredictable, whose essential budget is already short, or who is considering an advance for discretionary spending. I would also steer away from it when the expense is large enough to require extended repayment. In those cases, a bank, credit union, structured assistance program, or qualified financial counsellor may offer a more appropriate path.
Users who are uncomfortable reading financial terms on a phone should not rush. Ask a trusted person to review the arrangement, or use a larger screen if that makes the details easier to understand. The app can simplify access, but it cannot make a difficult financial decision risk-free. A clean interface should never replace independent judgement.
My final assessment
After looking at its purpose, audience, and trade-offs, I see Grant Cash Advance as a narrowly useful emergency finance app. Its strongest qualities are the straightforward focus, free access, broad Android compatibility, and the possibility of exploring a cash advance without a traditional credit-check route or interest. Those points explain why it has attracted over a million installs and such a strong average rating.
My recommendation comes with a firm condition: use it for a specific, temporary gap only when repayment is already realistic. Do not use the app to make an unaffordable budget appear workable, and do not assume that a fast application removes the need to inspect the details. For a one-off emergency with a clear repayment plan, I would consider trying it. For repeated shortfalls, large borrowing, or uncertain income, I would choose a more structured alternative.
In short, this is a useful option rather than a universal answer. Grant Cash Advance earns a recommendation for careful users who need to investigate short-term help quickly, but the best result depends on what happens after the money arrives. If the advance fits a written plan and leaves essential expenses protected, the app can be practical. If it merely postpones an unavoidable shortage, closing the app and seeking broader financial help is the wiser decision.
FAQ
What is Grant Cash Advance, and how does it work?
Grant Cash Advance is a financial app designed to help users explore short-term cash advance options through a mobile device. After creating an account, you may be asked to provide personal, employment, income, and banking information so the service can evaluate your request. The app may connect users with third-party lenders or financial providers, so approval, loan terms, fees, and funding times can vary.
Is Grant Cash Advance a direct lender?
Before submitting an application, users should understand whether Grant Cash Advance provides funds directly or acts as a connection service for independent lenders. In many cash advance platforms, the app collects application details and shares them with potential providers in its network. Review the lender’s name, annual percentage rate, repayment schedule, fees, privacy policy, and authorization details carefully before accepting any offer.
What information does the app require?
Grant Cash Advance may request identifying and financial details such as your full name, address, phone number, email address, employment information, income, bank account details, and Social Security number or equivalent identification. This information can be sensitive, so only enter it through the official app or website. Check the privacy policy and make sure you understand how data may be stored or shared.
How much does Grant Cash Advance cost, and when must it be repaid?
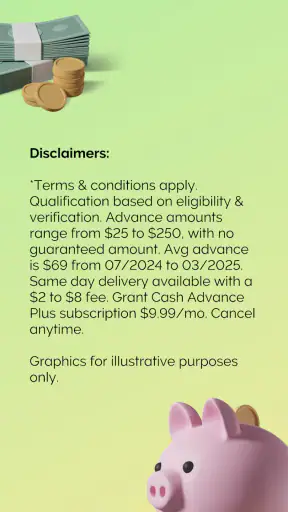
The cost and repayment terms depend on the provider, your eligibility, the amount requested, and local regulations. A cash advance may include interest, an origination charge, subscription cost, expedited-transfer fee, or other service fees. Do not rely only on an advertised amount. Read the final agreement carefully, confirm the total repayment figure and due date, and make sure repayment will not disrupt essential expenses.
Is Grant Cash Advance safe and available everywhere?
The app’s availability, eligibility rules, and services may differ by state or country, and some users may not qualify. Treat any request for upfront payment, guaranteed approval, or unusually favorable terms as a warning sign. Download only from an official app store, verify the publisher, use secure account credentials, and contact customer support through official channels if you notice suspicious activity or an unexpected withdrawal.











