

Get Paid Early: Cash Advance
4.2FinanceUpdated October 5, 2026
Screenshots
Pros
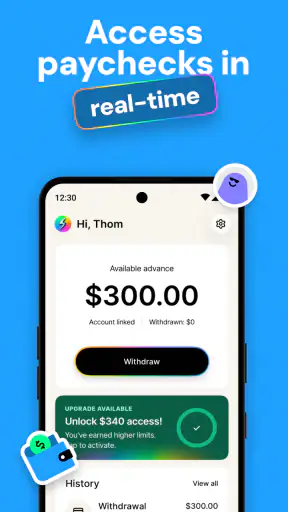
- Fast access to part of your earned wages before payday.
- Simple application process with minimal paperwork.
- Transparent repayment schedule shown before accepting an advance.
- Useful alerts help track upcoming repayments and account activity.
- May help cover unexpected expenses without using a credit card.
Cons
- Eligibility and advance limits may vary based on income and employer data.
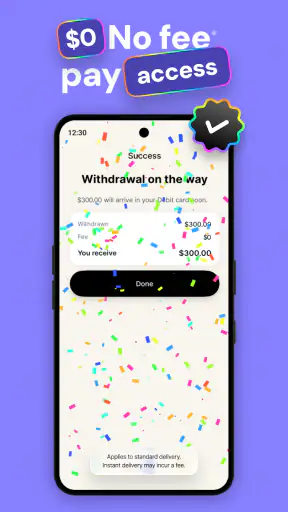
- Optional express transfers can involve additional fees.
- Repayment is usually deducted automatically from a future paycheck.
- Frequent advances may make it harder to manage the next payday.
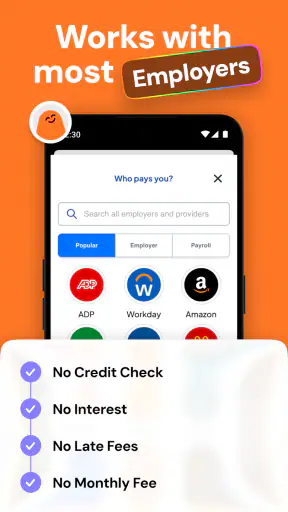
- Availability may depend on employer
- payroll provider
- or location.
 Analysis By Mobexer
When an unexpected bill lands before payday, the problem is often timing rather than long-term money management. Get Paid Early: Cash Advance is a finance app from StreamFunds, Inc. built around that narrow situation: helping eligible users access earned pay sooner, with the store positioning it as a no-loan, no-interest, no-hidden-fee option. I found the idea easy to understand, but the real question is whether the experience feels dependable when the request is urgent. My overall impression is that it can be useful for smoothing a short gap, provided you treat it as a limited cash-flow tool rather than a replacement for budgeting or emergency savings.
The app is free to install and aimed at Everyone, which makes it approachable for a broad audience. It has reached over 50 thousand installs and holds a 4.2 average from more than 700 ratings, with over 160 written reviews. Those figures suggest a reasonably positive reception, although they should not be mistaken for a guarantee that every user will receive money at the same speed or qualify in the same way. Access to earned pay naturally depends on the relationship between the app, the user’s work income, and the information needed to verify that income.
How Get Paid Early: Cash Advance feels in real use
Speed is the main reason to open it
The strongest part of the concept is its focus. This is not trying to be a complete banking dashboard, investment platform, or credit-card replacement. I would open it when I needed to deal with a short-lived mismatch between an incoming paycheck and an expense due today or tomorrow. That focused purpose makes the first decision fairly simple: if the money has already been earned, getting part of it earlier may be more sensible than turning to a conventional loan.
Still, “early” should be understood as a goal rather than a promise that every request will move instantly. A cash-access app has to identify the user, connect the request to earned income, and decide whether the request can proceed. Any delay in those steps matters much more when the payment deadline is close. My practical advice is to set up and understand the app before an emergency, not during the final minutes before a bill is due.
That preparation is one of the less obvious advantages of testing the service in a calm moment. You can learn what information it asks for, see how its screens are organized, and understand the point at which a request becomes final. Doing that early also gives you time to notice whether your employment and pay situation fit the app’s intended workflow. The best use of Get Paid Early: Cash Advance is planned short-term flexibility, not last-second financial rescue.
A realistic everyday scenario
Imagine that a utility payment is scheduled before your next regular payday, while your income for the current pay period has already been earned. In that situation, I would use the app to explore whether early access could cover the gap, then check the repayment or pay-cycle effect before confirming anything. The important part is not simply receiving money; it is making sure the next payday still leaves enough for rent, food, transport, and other fixed commitments.
This is where the app can be more practical than a traditional personal loan. A loan application usually introduces a larger borrowing decision, a longer repayment horizon, and interest considerations. Get Paid Early: Cash Advance is designed around a smaller timing problem. That narrower approach may reduce the temptation to borrow more than the immediate expense requires. On the other hand, someone facing recurring shortages may need a proper spending review or professional financial guidance instead of repeatedly moving pay forward.
What happens when the app is under pressure?
Heavy-use moments are less about having many screens open and more about urgency. A user may be checking the app while commuting, switching between the app and a payment service, or trying to complete a request with a weak connection. In those moments, a clean flow matters more than decorative features. I prefer a finance app that keeps the central action obvious and does not bury the consequences of a cash advance under unnecessary menus.
There is also a behavioral pressure that deserves attention. Easy access can make a temporary advance feel like extra income, even though it is really an adjustment to the timing of money already expected. I would write down the exact expense first, request only what is needed, and avoid using the available amount simply because it appears on screen. This small habit turns the app from an impulse tool into a controlled part of a weekly cash plan.
Another useful workflow is to pair the request with a calendar reminder for the next pay cycle. That reminder is not a feature claim about the app; it is a simple safeguard I would add myself. It helps prevent the common mistake of forgetting that an early-access decision can affect the amount available later. If your budget is already tight every pay period, this check is more important than the speed of the initial request.
Reliability matters more than visual polish
For a finance app, reliability means more than launching without crashing. I want the displayed status to be understandable, the next step to be clear, and the user to know whether an action is still being processed or has completed. When money is involved, uncertainty is stressful. A polished interface cannot compensate for unclear timing or a confusing confirmation screen.
My confidence in the app would therefore come from using it once before depending on it. I would check how quickly the main screens respond, whether the information remains consistent after reopening the app, and whether the request flow explains what I am agreeing to. If anything looks ambiguous, I would stop rather than assume that a repeated tap will speed things up. Repeatedly submitting a financial request is exactly the kind of behavior that can create avoidable confusion.
The developer, StreamFunds, Inc., has kept the product centered on early pay access rather than presenting it as a broad financial super-app. That focus is helpful because it makes the intended job clear. At the same time, a focused app gives users fewer reasons to stay inside it for broader money management. I would use it alongside my normal bank account and budgeting method, not as the single place where I track every financial decision.
Device limits and day-to-day practicality
The current version is 3.0.39, and the app supports Android 7.0 and later. That minimum is useful for people who keep an older phone, although an older operating system can bring practical limitations of its own. A device with limited storage, aggressive background restrictions, or an outdated system may make any finance workflow feel less smooth, even when the app itself is functioning properly.
I would also keep the phone’s system software and app installation current where possible, especially for an application dealing with income access. Avoiding a request on a nearly full device is sensible because low storage can affect updates and general responsiveness. If the phone is old enough that other banking applications already struggle, I would not choose this app as my only route to money in an urgent situation.
Resource demands are difficult to judge from the app’s purpose alone, but this is not the kind of product I would expect to need constant active use. Its value comes from completing a focused financial task, then closing it. That makes it more suitable for occasional checking than for leaving open all day. I would still avoid using it on a shared or unsecured device, and I would lock the phone and sign out according to my normal financial-app habits after finishing.
Recovery is another practical consideration. If the app closes, the connection drops, or the phone restarts halfway through a request, I would reopen it and inspect the current status before trying again. I would not assume that an interrupted screen means the request failed, and I would not submit a second request until the first one is clearly resolved. This cautious recovery habit is especially important in any app where a duplicate action could affect access to earned pay.
Who will get the most value?
I think the app is best suited to workers who occasionally experience a short gap between earned income and a necessary payment. It may appeal to someone who wants an alternative to overdraft charges or a conventional loan, particularly when the amount needed is modest and the next paycheck is reasonably predictable. The free price also lowers the barrier to trying the service and learning whether its process fits your circumstances.
It is less suitable for anyone who needs a large amount, has unpredictable income, or is already using early access repeatedly to cover ordinary living costs. In those cases, the convenience can hide a deeper cash-flow problem. A bank overdraft, credit product, employer-based pay option, or personal loan may have different costs and rules, so comparing the total consequences matters more than choosing whichever button is fastest.
I would also skip it if I could not clearly explain how an advance would affect my next pay cycle. The phrase “no interest” does not remove the need to understand timing, eligibility, and any conditions attached to the transaction. Before using it, I would ask myself three practical questions: what exact bill am I covering, when will the replacement income arrive, and what essential expense might be squeezed afterward?
How it compares with familiar alternatives
Compared with waiting for a standard payday, the obvious benefit is flexibility. The trade-off is that moving money forward can make the following pay period feel smaller. Compared with a credit card, the app’s earned-pay focus may feel more directly connected to income already generated, while a card can encourage spending beyond that income. Compared with a personal loan, it appears aimed at a shorter and more contained need rather than a multi-month borrowing plan.
None of those alternatives is automatically better. Someone with savings should normally consider using a small emergency reserve before borrowing or advancing pay, because savings do not reduce a future paycheck. Someone with a persistent income shortfall should investigate budgeting changes, benefits, or lower-cost credit advice. Someone who needs a purchase-specific payment method may find a card more convenient. Get Paid Early: Cash Advance makes the most sense when the problem is timing and the user has a clear plan for the next income event.
The app’s store positioning around no loans, no interest, and no hidden fees is appealing, but I would still read every confirmation screen carefully. “No interest” is not the same as “no financial consequence,” because receiving money earlier can change what is available later. A careful user should distinguish the absence of interest from the broader question of whether advancing pay improves or worsens the month’s budget.
My performance verdict
After looking at the product through the situations that matter most, I see Get Paid Early: Cash Advance as a focused convenience rather than a complete financial solution. Its perceived speed is the main attraction, its narrow purpose keeps the idea understandable, and its free availability makes an initial trial relatively easy. The positive average rating and growing install base also indicate that the concept has found an audience, though personal eligibility and timing remain central to the experience.
Its limitations are equally important. Urgent users may expect immediate access when verification or other steps take longer. People with unstable income may not get the predictable relief they want. And anyone who repeatedly advances pay risks turning a temporary bridge into a recurring cycle. The app cannot solve expenses that consistently exceed income, no matter how simple the request screen feels.
My recommendation is to install it only with a specific use case in mind, test the workflow before a deadline, and keep a second payment plan available for genuinely urgent bills. Use the smallest amount that solves the problem, confirm how the next pay cycle will look, and treat the service as a timing adjustment rather than free extra money. For that disciplined user, this finance app can be a convenient option. For someone looking for long-term debt relief, comprehensive budgeting, or guaranteed instant cash, a different financial tool will be the better choice.
FAQ
What is Get Paid Early: Cash Advance?
Get Paid Early: Cash Advance is a financial app designed to help eligible users access part of their expected income before their regular payday. After creating an account and completing the required verification, the app may display available advance options, repayment details, and any applicable fees. Availability and features can vary depending on your employer, income, location, and account history.
How does the cash advance process work?
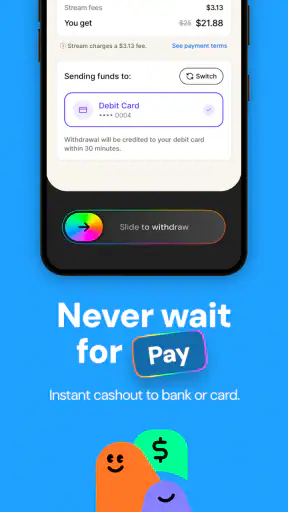
The app generally connects your financial information or eligible income source to estimate how much you may be able to receive early. If you qualify, you can review the offered amount, delivery method, repayment date, and total cost before confirming. Funds may arrive quickly through an expedited option, while standard delivery can take longer. Always read the final agreement carefully.
Are there fees or interest charges for using the app?
Cash advance services may involve optional express-transfer fees, subscription charges, or other costs, depending on the features you use and the terms shown in the app. A cash advance is not automatically free simply because it does not work like a traditional loan. Before accepting an advance, check the fee disclosure, repayment amount, and any recurring membership terms.
Who can use Get Paid Early: Cash Advance?
Eligibility is usually based on factors such as age, residence, a supported bank account, regular income, and the ability to verify your identity and financial information. Approval is not guaranteed, and meeting the basic requirements may not be enough to receive an advance. The service may also be unavailable in certain states, regions, or for some types of income.
When and how is a cash advance repaid?
Repayment is commonly scheduled for your next payday or another date specified during the advance process. The app may withdraw the amount automatically from a linked account, so users should ensure sufficient funds are available. Missing repayment can lead to account restrictions, bank charges, or other consequences. Review the repayment schedule and contact support promptly if your payday changes.











