

Gerald - Cash Advance
4.4FinanceUpdated October 2, 2026
Screenshots
Pros
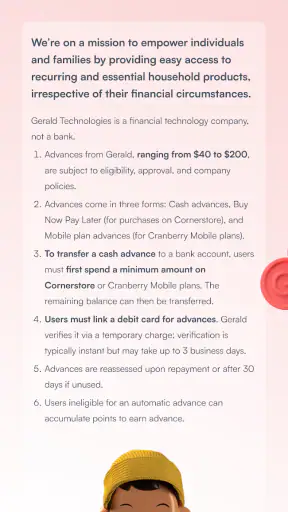
- Simple application process with minimal paperwork required
- Helpful repayment reminders can reduce the risk of missed due dates
- Loan details are presented clearly before accepting an offer
- May be useful for covering unexpected short-term expenses
- Account access is convenient through a mobile device
Cons
- Approval and loan availability may vary by state and applicant
- Short repayment periods can make budgeting difficult
- Late payments may lead to additional fees or credit consequences
- Personal and financial information is required during registration
- Not suitable as a long-term solution for recurring financial needs
 Analysis By Mobexer
When a small expense lands between paydays, I understand why a cash-advance app can look attractive. Gerald - Cash Advance is a finance app from Gerald Technologies, Inc. that focuses on giving users a way to request cash without a traditional credit check or interest charge. I tested it with a practical question in mind: could it fit into an ordinary household where more than one person uses the same phone, shares expenses, or needs to coordinate money without confusing one account for another?
My overall impression is that it is best viewed as a short-term budgeting tool, not a replacement for income, savings, or a regular bank account. The app is free to download, aimed at Everyone, and its current version is 69.0.9 for devices running Android 7.0 or later. That broad compatibility makes it accessible, but the important part is understanding the boundaries around any cash advance before treating the balance as available household money.
How Gerald fits into real household money decisions
A useful option when one person needs a small bridge
The most believable use case is simple: I have an essential bill or everyday purchase to cover, payday is approaching, and I want to avoid putting the expense on a high-cost credit card. In that situation, Gerald can serve as a temporary bridge. The appeal comes from its no-interest positioning and its promise of no credit check, which makes the app feel less intimidating than a conventional loan application.
That convenience should not be confused with free money. A cash advance still has to be managed against the next incoming payment. Before requesting anything, I would write down the amount needed, the expected repayment timing, and the bills that will arrive afterward. This extra step matters even more in a household, because money that looks available on one person’s phone may already be mentally assigned to rent, groceries, transport, or another shared obligation.
For a shared household, I would use the app as an individual tool rather than a communal wallet. One adult might request an advance to handle a personal shortfall, while the household budget remains tracked somewhere everyone already understands. That separation is a strength: it reduces the risk of assuming that another person can see or manage the same financial activity.
Why a shared phone changes the setup conversation
If two people use the same device, I would be careful during setup and every time the app is opened. Finance apps involve personal information, and a shared phone can blur account boundaries quickly. I would make sure the correct person is signing in, avoid handing the unlocked device around after opening the app, and never assume that a partner, roommate, or older child should automatically have access to the account.
This is not a criticism of Gerald specifically; it is a practical rule for any app connected to money. The app should be treated as belonging to the account holder, even when the phone belongs to the household. If one person is helping another with installation or navigation, I would keep the account holder involved at each step instead of completing financial actions on their behalf.
A useful household routine is to decide in advance which expenses qualify for an advance. For example, an adult might agree to use it only for an urgent utility payment or necessary travel, not for routine shopping that can wait. That agreement is more valuable than simply installing the app, because the main risk is often not the interface but the decision to borrow repeatedly for ordinary spending.
What I would check before requesting cash
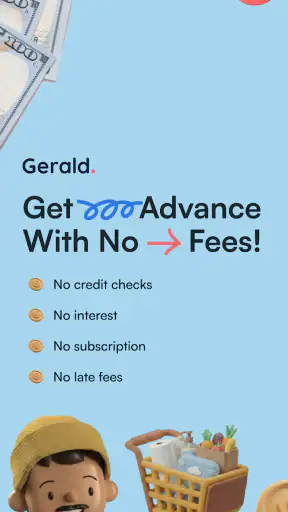
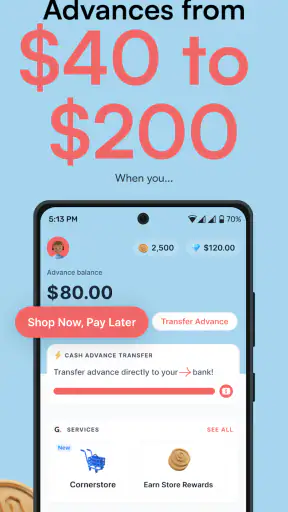
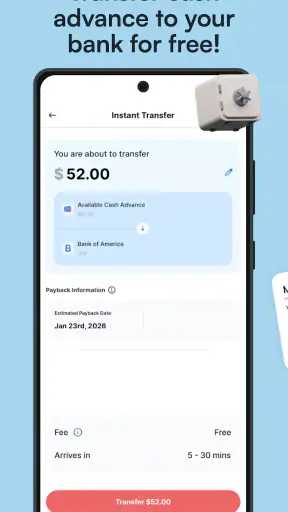
I would begin by reading the request screen carefully rather than tapping through quickly. The store summary emphasizes fast access, no credit check, and no interest, but those phrases do not remove the need to understand the actual flow inside the app. I would look for the amount available, the expected timing, any delivery choices shown, and what the app says about repayment before confirming.
I would also check whether the requested amount solves the immediate problem without creating a larger one. If a smaller advance covers the essential gap, that is usually easier to absorb than taking the maximum visible amount. This is one of the less obvious trade-offs with an app that makes borrowing feel simple: a smooth request process can reduce the pause that normally occurs when someone has to speak with a bank or fill out a longer application.
Another practical tip is to record the transaction outside the app. I would add the expected repayment to my personal budget or calendar and label it clearly. In a shared household, I would tell the person responsible for the relevant bill that the money is being handled separately. That avoids a common coordination mistake: one person assumes the bill is covered while another assumes the advance has already been used for something else.
Coordination without treating the app as a family account
Gerald makes the most sense when coordination happens around it, not inside a shared login. If a couple divides expenses, one person can use the app for their own shortfall while both continue using their normal method for tracking rent, food, and recurring payments. I would not create a shared password or leave the account open for convenience. Financial transparency should come from an agreed household conversation, not from passing a personal account between devices.
For roommates, the boundary is even clearer. An advance requested by one roommate should not be counted as proof that the household has extra funds. If the money is intended for a joint expense, I would agree beforehand who owes what and when. Otherwise, the app can unintentionally turn a shared bill into a private borrowing decision that affects everyone’s cash flow.
Parents may also wonder whether this is appropriate for a teenager using a family phone. I would keep the account with an adult who understands the repayment responsibility. The Everyone content rating describes the app’s general age suitability, but it should not be read as financial independence for every age group. A young person can be present while an adult explains budgeting, yet the adult should remain responsible for account decisions and personal financial information.
Trust, privacy, and the right person using the account
Trust matters more here than the app’s simple interface. I would only use the service for my own financial need or with an adult household member who has clearly agreed to the arrangement. I would not ask a friend to apply on my behalf, use another person’s identity, or let someone else control the account because they are more comfortable with technology.
On a shared device, I would close the app after use and review the phone’s general privacy settings. I would also avoid discussing account details in a group chat or leaving screenshots where other people can see them. These are small habits, but they prevent a convenience tool from exposing sensitive information to the wrong household member.
The app’s popularity gives it some context: it has a 4.4 average from around 10 thousand ratings and has passed 500 thousand installs. I see that as evidence that many people are willing to try it, not as a guarantee that every request will suit every financial situation. A rating cannot tell me whether the service is right for a household with irregular income, existing debt, or several upcoming bills.
Where it compares well with ordinary alternatives
Compared with a credit card cash advance, Gerald’s central attraction is the absence of interest and a credit check in its store positioning. That can make it preferable for someone who wants to avoid adding a high-cost balance or does not want a credit inquiry to be part of the process. Compared with asking a family member for money, it may feel more private and less emotionally uncomfortable.
However, a bank account buffer or an emergency savings fund is still healthier when those options are available. Savings do not create a repayment event after the emergency, and a bank’s established overdraft or credit product may offer clearer terms for someone who needs a larger, more predictable facility. I would choose Gerald for a limited shortfall, not for rent that is likely to be unaffordable again next month.
It also differs from a budgeting app. A budgeting app helps me plan money I already have; Gerald is relevant when I am considering access to money before my normal cash flow arrives. That distinction is important. If the underlying problem is that household spending is consistently higher than income, an advance may postpone the problem rather than solve it. In that case, a direct conversation about bills, a spending plan, or assistance from a trusted financial adviser would be the better next step.
Friction I would expect in everyday use
The main friction is psychological rather than technical: fast access can encourage fast decisions. I would resist opening the app every time an optional purchase feels inconvenient to delay. The most responsible workflow is to identify the bill, confirm the amount, check the next pay cycle, and then decide whether borrowing is genuinely necessary.
Another limitation is that household coordination remains manual. I would not expect the app to replace a shared spreadsheet, banking arrangement, or conversation about who is paying which bill. If several people need simultaneous visibility into one family budget, a dedicated shared-finance system may be a better fit. Gerald is more naturally suited to the individual who needs to manage their own request.
I would also avoid assuming that the phrase “no interest” means there can never be any other condition, timing issue, or cost connected with the way funds are delivered. The responsible approach is to read every in-app disclosure shown before confirmation. If the final terms do not match what I can comfortably repay, I would stop rather than proceed simply because the request appears quick.
Three practical workflows that make the app safer to use
My first recommended workflow is the “single-purpose advance.” I would decide the exact bill or necessity first, request only what addresses it, and immediately record the repayment expectation. This prevents the money from blending into general spending and gives the household a clear explanation of where it went.
The second is the “two-person check,” useful for couples sharing major expenses. The account holder remains the only person operating the account, but they tell their partner how the advance affects the household plan. This preserves account boundaries while preventing surprises in the shared budget.
The third is the “no-repeat test.” Before taking another advance, I would ask whether the previous one has been fully absorbed by the budget and whether the next need is genuinely different. If the answer is no, the app is no longer acting as an occasional bridge; it is becoming part of regular income. That is the point where I would stop using it and look for a more durable solution.
Who should use it and who should skip it
I think Gerald is most suitable for an adult who understands their upcoming cash flow, needs a temporary solution, and values avoiding a traditional credit-check process. It can also suit a household where one person handles their own shortfall but communicates clearly about any effect on shared expenses.
I would skip it if I could not identify exactly how the advance would be repaid, if my income timing was too uncertain, or if I was already relying on advances to cover ordinary bills. I would also choose another option if several people need joint access, if the household requires detailed shared budgeting, or if an emergency fund can cover the expense without creating a future obligation.
For families, I would not install it on a child’s device as a shortcut to teaching money management. A parent can discuss the idea of short-term borrowing, but the account should remain under the control of the adult who accepts responsibility. For a shared-device household, separate user habits and clear conversations matter more than convenience.
My household verdict
After looking at Gerald as both a cash tool and a household coordination issue, I see a focused product rather than an all-purpose financial solution. Its free access, no-interest positioning, and no-credit-check approach make it appealing for a carefully chosen short-term gap. The app’s broad Android compatibility and Everyone rating also make it easy for many households to consider.
Still, I would recommend using it with deliberate limits. Keep the account personal, discuss any shared consequence with the household, read the final request details, and record the repayment in a budget outside the app. Those steps address the areas where a quick financial tool can create confusion: who owns the account, who is responsible for the money, and whether the next paycheck can realistically absorb the advance.
My recommendation is cautious but positive: Gerald can be useful when the need is specific, the amount is modest, and repayment is already clear. I would not use it to disguise a recurring budget shortfall or to give a child independent access to borrowing. Used as an occasional bridge by a responsible adult, it has a practical place; used as a substitute for savings or stable income, it is the wrong tool.
Gerald Technologies, Inc. has built an app that addresses a real moment of financial pressure, and the response from users is reflected in its 4.4 average and more than 4 thousand reviews. My final advice is to treat that popularity as a reason to investigate the app, not a reason to skip personal judgment. For the right household situation, Gerald - Cash Advance can make a narrow problem easier to manage. The best results will come from keeping that purpose narrow.
FAQ
What is Gerald - Cash Advance, and how does it work?
Gerald is a financial app designed to help eligible users access short-term cash advances and manage everyday spending. After creating an account and completing identity and eligibility checks, users may see an available advance amount in the app. The money can be transferred according to the options offered, while repayment terms, limits, and availability may vary based on individual account activity and Gerald’s current policies.
Who can use Gerald, and what information is required to sign up?
Gerald is generally intended for adults who meet its eligibility requirements and have a supported bank account or other qualifying financial connection. During registration, the app may request personal details, identity verification information, employment or income data, and permission to connect a bank account. Approval is not guaranteed, and availability can depend on location, account history, income patterns, and other verification results.
Does Gerald charge interest, fees, or a monthly subscription?
The total cost of using Gerald depends on the specific product and features available to your account. Some services may be advertised without traditional interest, but optional features, expedited transfers, membership plans, or other charges could apply. Before accepting an advance or activating a paid feature, carefully review the in-app pricing, repayment information, and terms so you understand exactly what will be deducted and when.
How and when do I repay a Gerald cash advance?
Repayment is usually scheduled through the payment method or bank account connected to your Gerald profile, with the due date and amount displayed in the app. You should confirm that sufficient funds are available before the scheduled repayment date. Missing a payment or having a failed debit may affect your access to future advances and could result in additional consequences under the applicable account agreement.
Is Gerald safe to use, and should I download it?
Gerald uses account verification and security measures intended to protect user information, but no financial app can eliminate every privacy or security risk. Download the application only from an official app store, check the developer name, and review permissions before connecting your bank account. Gerald may be useful for eligible users facing a temporary cash shortage, but it should not replace a sustainable budget or emergency fund.











