

Félix Pago
4.5FinanceUpdated October 5, 2026
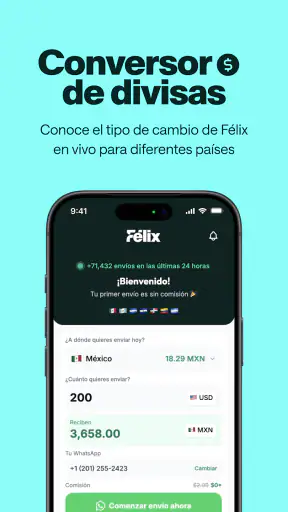
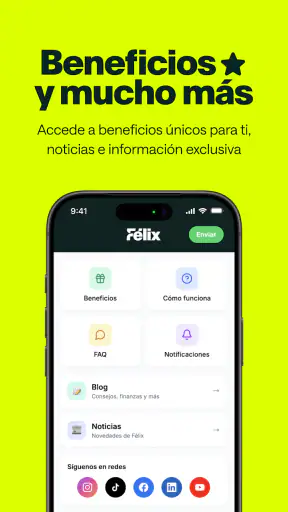
Screenshots
Pros
- Fast international money transfers through a simple mobile interface.
- Supports convenient remittances to selected Latin American countries.
- Clear transfer tracking helps users monitor payment progress.
- Useful for recurring family support and everyday cross-border payments.
- Digital-first service reduces the need to visit a traditional money-transfer office.
Cons
- Availability and features vary depending on the sender’s country.
- Exchange rates and fees may differ by transfer method and destination.
- Recipients may need identification or additional verification to collect funds.
- Transfers can be delayed by compliance checks
- weekends
- or partner networks.
- Customer support options may be limited outside regular service hours.
 Analysis By Mobexer
Sending money from the United States can be simple in theory and surprisingly awkward in practice. The right choice depends less on having the longest feature list and more on whether the service fits the way you actually support people, handle transfers, and keep track of your finances. I approached Félix Pago with that decision in mind: not as a general-purpose banking replacement, but as a finance app focused on making transfers feel less complicated.
Developed by Félix Pago, the app is free and aimed at everyone, which makes it easy to consider without committing money upfront. It has reached over one hundred thousand installs and holds a 4.5 average from around one thousand six hundred ratings, with roughly eight hundred fifty reviews. Those figures suggest that the app has found a real audience, but they do not remove the need to ask an important question: is its focused approach suitable for your particular transfer habits?
What I looked for before recommending it
My first test for a money-transfer app is clarity. I want to understand what I am doing before I confirm anything: who receives the money, what amount is being sent, and whether the process feels manageable when I am in a hurry. An app can be technically capable and still be a poor everyday tool if its screens make a routine payment feel like paperwork.
That is where Félix Pago makes a strong first impression. Its identity is narrow and easy to understand: it is built around sending money from the United States. Instead of approaching it like a full financial dashboard, I see it as a dedicated starting point for people who regularly need to move money across borders and do not want to navigate unrelated banking functions first.
The next criterion is repetition. A one-time transfer can tolerate a little friction, while a transfer made every week or month needs a workflow that becomes familiar quickly. I paid attention to whether the app’s purpose stayed visible throughout the experience and whether I could think in terms of the recipient and the reason for the payment instead of constantly thinking about the software.
I also considered the practical questions people usually ask after installing a finance app. Is it suitable for helping family members? Does it replace a bank account? Is it a better fit than a traditional remittance service? Should someone use it for business payments or large, infrequent transfers? The answers depend on the role you expect it to play, and confusing that role is the easiest way to choose the wrong tool.
A useful distinction between sending and managing money
One of my most important takeaways is that a transfer app should not automatically be judged by the standards of a banking app. A bank may be better for holding balances, organizing bills, viewing broader account activity, or managing several financial products in one place. Félix Pago is more appealing when the immediate task is sending money from the United States and you want that task to remain the center of attention.
This distinction also helps set expectations around the free price. Free makes the app approachable, but it should not be interpreted as a promise that every possible money service is included or that every transfer situation will be equally suitable. I would still review the final transaction details carefully before confirming a payment, especially when exchange rates, delivery arrangements, or recipient information matter to the person receiving the funds.
Where Félix Pago feels strongest
The clearest strength is focus. When I open a specialized transfer app, I do not want to feel as if I am entering a general financial supermarket. Félix Pago’s purpose is easier to grasp than that. For someone who primarily wants to send money from the United States, this focused identity can reduce the mental effort involved in deciding which section, product, or service to use.
That matters in real life. Imagine that a family member needs help with an urgent household expense. You are between errands, you already know the amount you want to send, and you do not want to compare a collection of unrelated financial tools. In that situation, a dedicated transfer workflow is valuable because it keeps the task direct. The app is not solving every financial problem; it is helping you concentrate on the one in front of you.
The best reason to choose Félix Pago is its focused job: sending money without turning the process into a broader banking project. That focus is especially useful for people who support relatives, send regular assistance, or need a repeatable way to initiate transfers from the United States.
It suits recurring personal support better than occasional experimentation
I think the app makes the most sense when sending money is part of your routine. A repeat user can develop a personal checklist: confirm the recipient, verify the amount, inspect the final details, and submit. This kind of habit is more valuable than a flashy interface because it lowers the chance of rushing through a familiar but important financial action.
A practical tip is to decide on your own confirmation routine before sending. I would check the recipient’s details slowly, even if I have used the app before, and keep a record of the transfer outside the app when the payment is connected to a household budget. That is not a special feature claim; it is a sensible way to use a focused transfer tool responsibly. Convenience should not replace verification.
The app’s broad age rating also makes its intended accessibility clear. It is marked for Everyone, so it does not present itself as a niche professional finance product. Still, accessibility should not be confused with suitability for every financial need. A person can find the app easy to approach and still need a bank, accountant, or another service for more complex money management.
The free entry point lowers the decision barrier
There is no purchase price to overcome, which makes trying Félix Pago less intimidating than committing to a paid financial tool. That is useful for someone comparing transfer categories rather than choosing between two identical products. You can evaluate whether the workflow fits your habits before deciding whether it deserves a permanent place in your routine.
My advice is to treat the first use as a learning transfer, not as a moment to rush through a large or highly sensitive payment. Explore the screens, note what information is requested, and make sure the recipient details are comfortable to review. This approach gives you a better sense of the app’s practical fit than relying on its short description alone.
The current version is 1.1.14, and the app requires Android 7.0 or later. That makes the technical entry requirement fairly approachable for people using an older supported Android device. If you are deciding whether to install it on a particular phone, the operating-system requirement is one of the first checks I would make before building your transfer routine around it.
What I would not overlook during a transfer
Specialized apps can feel faster because they remove distractions, but financial speed should never mean skipping the final review. I would pause at the point where the transfer details are presented and compare the recipient information with the message or request that prompted the payment. This is particularly important when several relatives have similar names or when you are sending from a busy place.
I would also avoid treating the app as a place to improvise. Decide the amount and purpose before opening it, rather than browsing through the process while negotiating the payment in your head. That small change makes the app feel more efficient and reduces the chance of making a mistake caused by distraction rather than by the interface.
When another category may be a better fit
Félix Pago is not automatically the best choice for everyone who sends money internationally. If your main goal is to manage your entire financial life, a traditional bank app may be more appropriate. Banks are usually the natural place to review accounts, handle domestic payments, organize savings, and keep a wider record of your finances. A transfer-focused app can complement that setup, but it should not be selected as a replacement without checking what you actually need.
A dedicated remittance service may also be preferable if your priorities center on comparing delivery methods, recipient access options, or a highly established transfer workflow. I am not assigning features or prices to any particular competitor here; the useful comparison is between categories. Félix Pago appeals through simplicity and purpose. A broader remittance platform may appeal more to someone who wants a larger menu of transfer arrangements and is willing to spend more time comparing them.
For business use, I would be cautious. A person sending occasional help to family has a different need from a small company paying contractors, suppliers, or overseas staff. Business users may require formal records, approval steps, accounting integration, or controls that are outside the narrow personal-transfer question. I would not choose Félix Pago for organizational payments without first confirming that its workflow matches those responsibilities.
Who should probably skip it
I would look elsewhere if you want one app to hold money, track spending, pay bills, and coordinate multiple financial accounts. The appeal here comes from not trying to do all of those things at once. If your ideal app is a complete financial command center, this focused approach may feel limited rather than refreshingly simple.
I would also hesitate if you rarely send money and prefer to compare every possible provider before each transaction. A specialized app is most convincing when its directness saves you effort repeatedly. For a single unusual transfer, another option might offer a better match for your exact destination, delivery preference, or documentation needs.
Finally, people who need extensive transaction organization should think about their record-keeping before switching. A convenient sending experience does not necessarily replace a personal spreadsheet, bank statement, or household budgeting system. If you need to reconcile transfers with rent, tuition, medical costs, or family contributions, create a simple tracking habit from the beginning rather than assuming the app will become your complete financial archive.
The real cost of switching
Because the app is free, the most important switching cost is not the download. It is the time spent learning a new transfer routine and deciding whether it is reliable enough for the people who depend on you. That cost is small when you are merely testing the experience, but it becomes more meaningful once you have recurring payments and recipients expecting a familiar process.
I would switch gradually. First, identify the transfers you make most often and write down the information you normally verify. Then use Félix Pago for a modest, non-urgent transaction while keeping your existing method available. This gives you a chance to judge the workflow without putting an important deadline or family obligation at risk.
A second hidden cost is habit disruption. If you already use a bank or remittance service, you may know exactly where to find receipts, review past activity, and confirm that a payment was completed. Moving to a new app means rebuilding those habits. The app may be simpler at the moment of sending, but your overall process is only better if you can also keep your records clear afterward.
There is also a human cost to consider. If you send money to someone who is not comfortable with new payment routines, the sender’s convenience may not be the only deciding factor. Before changing your method, make sure the recipient understands what to expect and has the practical ability to receive the money through the chosen arrangement. A smooth sender experience is not enough if the other side is confused.
How I would compare it with the usual alternatives
I would compare Félix Pago with three broad choices. A bank app is the strongest candidate when your priority is centralized financial management. A conventional remittance service is worth considering when you want to compare transfer arrangements in detail. An informal method may feel familiar, but it can be harder to organize and evaluate consistently. Félix Pago sits between those ideas as a purpose-built option for sending from the United States without requiring you to adopt a full banking ecosystem.
The trade-off is straightforward. You gain a clearer, narrower purpose, but you should not expect that narrow purpose to answer every financial question. You may spend less time finding the transfer function, while still needing your own process for budgeting, receipts, and recipient verification. That is a good trade for a repeat sender who values simplicity, but a less convincing one for someone who wants maximum breadth in one place.
My recommendation after using it
I recommend Félix Pago to people in the United States who regularly send money and want a dedicated finance app rather than a complete banking replacement. Its free price, approachable positioning, and focused purpose make it easy to test. The 4.5 average and more than one hundred thousand installs also show that it is not an obscure experiment with no visible user base.
My recommendation comes with a clear boundary: use it because its focused transfer workflow matches your need, not because a specialized app must be better than every bank or remittance alternative. If you need broad account management, detailed business controls, or a large range of transfer choices, another category may serve you better.
For a careful first setup, I would install it on a supported Android device, prepare the recipient information before starting, review each confirmation screen, and keep a personal note of the transaction. That routine turns convenience into something dependable. I would also make sure the recipient is ready for the chosen payment process and avoid making the first test a payment that cannot tolerate delay or correction.
In the end, Félix Pago earns my recommendation as a focused tool, not as an all-purpose financial solution. I like the fact that its purpose is easy to understand, and I can see why recurring personal senders would prefer that directness. The right user will appreciate having fewer distractions between deciding to send money and completing the task. The wrong user will feel constrained by the same focus.
If your question is “Should I try it?”, my answer is yes when sending money from the United States is a regular part of your life and you want to evaluate a simpler workflow. Try it carefully, compare it with the category that currently serves you, and judge the complete routine rather than just the opening screen. That is the fairest way to decide whether this app genuinely makes your transfers easier.
FAQ
What is Félix Pago and how does it work?
Félix Pago is a digital payment service designed to make money transfers and everyday financial transactions more accessible through a mobile device. Depending on your location and the services currently available, you may be able to send or receive money, pay bills, or manage other supported transactions. The app guides you through each operation, displays the applicable exchange rate or fee, and asks you to confirm before completing the transfer.
Is Félix Pago safe to use for sending and receiving money?
Félix Pago uses account verification and security measures intended to protect users and their transactions, but no financial application is completely risk-free. Before using it, download the official version, create a strong account password, and never share verification codes with anyone. Always check the recipient’s information carefully, keep your phone updated, and contact official support if you notice unfamiliar activity or a delayed transaction.
What countries and currencies does Félix Pago support?
Availability depends on the country where you live, the destination of the transfer, and the services Félix Pago offers at the time you use the app. Supported currencies, transfer corridors, identity requirements, and payment methods can change. The app normally shows whether a destination is eligible before you proceed. We recommend checking the current service list and reviewing the final amount, exchange rate, and fees inside the app.
Are there fees or limits when using Félix Pago?
Félix Pago may apply fees, exchange-rate margins, or transaction limits depending on the type of operation, funding method, destination, and account verification status. The exact cost is not necessarily the same for every user or transfer. Before confirming a payment, review the summary carefully to see the amount the recipient will receive, any service charges, and the estimated delivery time.
What should I do if my Félix Pago transfer is delayed or incorrect?
First, open the transaction history and check whether the operation is pending, completed, rejected, or cancelled. Confirm that the recipient details and payment method were correct, then allow for possible processing delays caused by banks, partners, weekends, or verification checks. If the problem remains, contact Félix Pago through its official in-app support or help channels and provide the transaction reference without sharing your password or security code.











