

FaithFi: Faith & Finance
3.6FinanceUpdated October 2, 2026
Screenshots
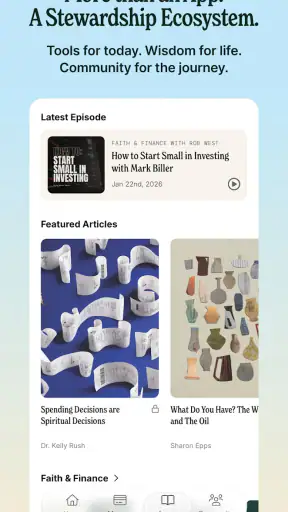
Pros
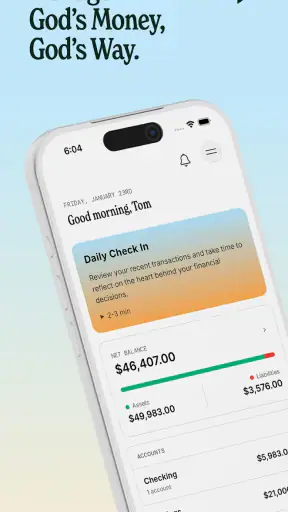
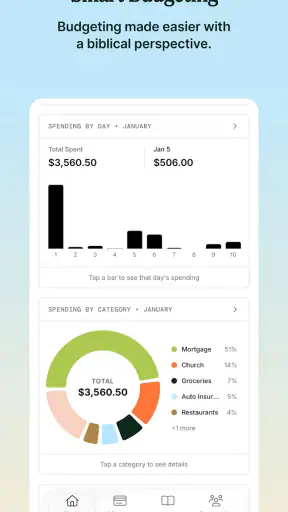
- Combines budgeting tools with Bible-based financial guidance.
- Simple interface makes tracking spending approachable for beginners.
- Offers practical lessons on saving
- giving
- and managing debt.
- Encourages intentional spending through faith-centered financial goals.
- Helpful reminders can support consistent budgeting and saving habits.
Cons
- Some features may require a paid subscription or in-app purchase.
- Religious perspective may not suit users seeking secular finance advice.
- Advanced investment and tax-planning tools are limited.
- Content may feel repetitive for experienced budgeters.
- Requires regular manual updates if bank syncing is unavailable.
 Analysis By Mobexer
I approached FaithFi: Faith & Finance as a beginner looking for a calmer way to connect personal money decisions with Christian faith. The app sits in the finance category, but it does not feel like a conventional banking dashboard or a spreadsheet replacement. Its main appeal is the way it frames everyday financial choices around reflection, responsibility, and practical habits rather than treating money as a collection of transactions.
That distinction matters before you install it. I would not choose this app as my only tool for checking balances, moving money, filing taxes, or managing investments. I would choose it as a companion for thinking more deliberately about spending, saving, giving, and the motivations behind those choices. The developer, FaithFi: Faith & Finance, has built something aimed at people who want financial guidance to sit alongside their beliefs instead of being completely separate from them.
The app is free to download and is suitable for Everyone, which makes it easy to try without committing money at the start. There are optional in-app purchases ranging from $3.99 to $11.99 per item, so I would still look carefully at any upgrade screen before confirming a purchase. Its store presence shows over 10K installs and an average rating of 3.6 from around 160 ratings, a modest reception that suggests the experience will suit some users much better than others.
What the first session feels like
My first impression is that FaithFi works best when I treat it as a guided financial reflection tool, not as a universal money manager. The store summary, “Where Faith Meets Everyday Finances,” describes the central idea clearly, but the useful question is how that idea fits into an ordinary week. I can imagine opening it after payday, during a monthly budget review, or when I am trying to decide whether a purchase is genuinely useful or simply impulsive.
The strongest reason to try it is focus. Many finance apps push me toward charts, categories, account connections, and numerical targets. Those tools can be valuable, but they do not always help with the emotional side of money. FaithFi gives that side more attention. For a user who wants reminders of stewardship, generosity, contentment, or intentional decision-making, that perspective can make a routine financial check-in feel more personal.
At the same time, expectations need to stay realistic. This is not an app I would recommend to someone who mainly wants automatic expense imports, detailed investment analysis, or a replacement for a bank’s secure mobile application. A traditional budgeting app is likely better for people who want granular reports and extensive customization. FaithFi makes more sense when the purpose is to develop a faith-informed money routine.
Who is likely to benefit most
I see three especially good audiences. The first is someone beginning to manage money independently and wanting values to be part of the process from the beginning. The second is a person who already budgets but feels that their system has become purely mechanical. The third is a household looking for a shared language around spending, saving, and giving without turning every conversation into an argument about numbers.
It can also help someone who repeatedly makes a budget and then abandons it. In that situation, another spreadsheet may not solve the real problem. A values-based prompt or moment of reflection can make the budget feel connected to a larger purpose. That does not guarantee discipline, but it can make the next decision easier to understand.
I would be more cautious if I wanted a highly technical finance product. Users who need extensive account synchronization, tax records, debt amortization, or professional investment tools should probably keep using specialized services. The app’s faith-centered approach is its reason to exist, but that same focus means it should not be judged as though it were a full financial institution.
Getting through setup without overthinking it
For a first-time user, my advice is to begin with one financial question rather than trying to redesign your entire life in a single session. Before opening the app, decide whether your immediate goal is controlling discretionary spending, becoming more consistent with saving, thinking about generosity, or simply creating a regular money check-in. A narrow starting point makes the experience more useful because you have something concrete to compare with your daily decisions.
I would also keep a note nearby during the first session. Not a full list of every transaction, but a few observations: where money tends to disappear, which purchases create regret, and which financial choices feel aligned with your priorities. This turns the app from something I merely read into something I use to notice patterns. The important first step is not entering perfect information; it is identifying one habit worth examining.
Because the app is free to start, I can explore its basic experience before deciding whether any paid item is worthwhile. That is a sensible order. I would not purchase anything just because an upgrade appears during setup. First I would learn whether the app’s tone, guidance, and workflow actually fit the way I think about money. If I use it consistently for a while, then I can decide whether additional content or functionality justifies the cost.
The current version is 5.1.3, and the listed minimum operating system is Android 7.0. That makes the app accessible to people using older Android devices, although I would still install it from the official store and keep the operating system reasonably maintained. The age rating of Everyone is reassuring for households, but it does not mean every financial lesson will be equally useful for every age group. A child, student, couple, and retiree will naturally bring different questions to the same material.
A practical setup routine
I would use this sequence for the first session:
Choose one area of money that currently causes the most friction.
Write down the decision you want to make more intentionally, such as whether a recurring purchase still serves you.
Read or work through the relevant guidance without trying to complete every possible activity immediately.
Turn the reflection into one small action that can be checked within the next few days.
Return after that action and decide whether the app helped you think differently or merely repeated ideas you already knew.
This approach is more effective than treating the app like a course that must be finished quickly. Faith and Finance is most useful when its ideas become part of a repeated routine. I would rather spend a few minutes making one honest decision than spend a long session collecting notes that never affect my behavior.
The first meaningful success
For me, a successful first action would be choosing one spending decision and connecting it to a clear personal value. Imagine receiving a paycheck on Friday and noticing that several small purchases are competing with a goal to build a more stable month. Instead of only cutting random items, I could use the app’s faith-oriented perspective to ask which expenses support my responsibilities and which ones are simply automatic.
The outcome does not need to be dramatic. I might cancel one unused service, delay a nonessential purchase, or set aside money before the weekend begins. The important part is that the decision is deliberate rather than reactive. A finance app earns its place on my phone when it helps me do something differently, not merely when it gives me another screen to browse.
A second realistic example involves giving. Someone may want generosity to be consistent but find that it happens only when there is money left over. A values-based review can encourage that person to think about giving as an intentional part of the plan instead of an afterthought. The app cannot make the decision for them, and I would not expect it to replace personal prayer, church guidance, or a household conversation. Its role is to help bring the question into the normal rhythm of financial planning.
For couples, I think the best first use is not comparing every purchase. It is agreeing on one shared question, such as what financial security means to both people or how they want to approach generosity. That creates less defensiveness than opening with a list of mistakes. One person can use the app privately first, then bring one useful insight into the conversation rather than presenting the whole experience as a set of rules.
Three details that make the workflow more useful
First, separate reflection from record keeping. I would continue using a bank app, notebook, or established budget for exact transaction history and use FaithFi for the meaning behind those numbers. Mixing both jobs can create frustration if I expect a faith-based companion to behave like accounting software.
Second, attach every insight to a calendar moment. A lesson about contentment is easy to appreciate and easy to forget. I would revisit it before grocery shopping, payday, or a planned purchase. Linking the idea to a predictable decision is more powerful than reading it once and hoping it remains active in my mind.
Third, use it before a problem becomes urgent. Financial reflection is most valuable before an overdraft, an argument, or a large impulse purchase. A short weekly check-in can reveal that a budget is drifting while there is still time to adjust. This is a quieter use case, but it is probably more sustainable than opening the app only during a crisis.
Where new users may get confused
The biggest possible confusion is assuming that a faith-centered finance app automatically provides complete financial planning. It does not make a bank account, a debt counselor, or a licensed adviser unnecessary. I would use it beside those resources, especially when the decision involves legal obligations, complex debt, investing, or a major household commitment.
Another point of friction is that values-based guidance can feel broad if I arrive expecting a precise answer. Money decisions often depend on income, family responsibilities, location, debt terms, and personal convictions. An app can offer a framework, but it cannot responsibly tell every user exactly how much to spend, save, or give. I appreciate the framework more when I treat it as a prompt for wiser judgment rather than a universal formula.
The rating of 3.6 is worth keeping in mind without treating it as a final verdict. With around 85 written reviews, the public response is still relatively small, and ratings cannot explain whether dissatisfaction came from technical problems, expectations, content preferences, or missing finance features. I would use the app personally for a short trial and judge whether it changes my decisions. That test is more useful than relying on an average number alone.
Paid content may also create uncertainty for first-time users. Since individual purchases can cost from $3.99 to $11.99, I would read the purchase description carefully and confirm whether the item addresses a specific need I already identified. A paid option is easier to evaluate when I know exactly what problem I want it to solve. If I am still exploring the app’s basic approach, staying with the free experience is the safer choice.
There is also a subtle risk of guilt. Financial faith content can be encouraging, but some users may interpret every money mistake as a moral failure. I prefer to use the app with honesty and proportion. A missed budget target is information about a habit, not proof that a person lacks character. If a particular exercise increases shame instead of helping me act wisely, I would step back and discuss the issue with a trusted person rather than forcing myself through it.
How it compares with familiar alternatives
Compared with a standard budgeting app, FaithFi is less about building a detailed numerical model and more about bringing beliefs into everyday choices. A conventional budget wins when I need categories, reports, forecasts, or transaction-level precision. FaithFi wins when the missing ingredient is purpose. In practice, I would be comfortable using both: one to show what happened and the other to help decide what should happen next.
Compared with a bank app, the difference is even clearer. A bank application is the right place for balances, transfers, statements, and account security. FaithFi is not a substitute for those tasks. Its value begins after I have seen the numbers and need to interpret them. That makes it complementary rather than competitive.
Compared with financial books, sermons, or podcasts, the app is more convenient for a short personal check-in because it is already available during the moment when a decision occurs. Books can provide deeper context, while a church community can provide accountability and wisdom tailored to a person’s circumstances. I would not expect an app to replace either. Its advantage is accessibility; its limitation is that its guidance cannot know my full story.
Making the habit last beyond the first week
After the first successful action, I would establish a simple recurring pattern. One session could happen near payday, when I decide what deserves priority before money is spent. Another could happen at the end of the month, when I review whether my choices matched my intentions. These sessions do not need to be long. Consistency matters more than creating an elaborate ritual that becomes difficult to maintain.
I would keep the app focused on decisions that are easy to recognize. “Spend better” is too vague. “Pause before replacing a working device” or “decide on giving before discretionary spending” gives me a clear moment to apply what I learned. This is one of the most practical ways to turn faith and finance from an abstract theme into a repeatable behavior.
For a household, I would suggest agreeing on privacy boundaries before using the app together. Not every person will want to disclose every purchase, and a shared values conversation does not require total financial surveillance. Decide which goals are shared, which decisions are individual, and when you will review progress. That small agreement can prevent the app from becoming another source of tension.
I would also reassess the app after several sessions. Does it help me pause before spending? Does it make conversations about money more constructive? Does it encourage a clearer plan for saving or giving? If the answer is yes, it has earned a regular place in my routine. If I only open it, agree with the ideas, and return to exactly the same habits, a different tool or a conversation with a financial professional may be more useful.
My main recommendation is to use FaithFi as the values layer of a broader money system. Keep precise records wherever they are easiest to maintain, then use this app to ask whether those financial choices reflect the life and faith you are trying to build. That division of labor avoids the most common disappointment while preserving the app’s strongest quality.
Overall, I think FaithFi is worth trying for Android users who want a Christian perspective woven into ordinary financial decisions and who are comfortable with guidance rather than a complete accounting platform. It is free to begin, accessible on older Android versions, and gentle enough for a first step. I would skip it if I needed advanced financial automation or strictly numerical control, but I would recommend it to a friend who wants to make money conversations more intentional.
The best result will not come from reading everything in one sitting. It will come from opening the app with one real decision in mind, taking one practical action, and returning to see whether that action brought spending closer to your priorities. Used that way, FaithFi: Faith & Finance feels less like another finance utility and more like a quiet checkpoint between what I believe and what I do with money.
FAQ
What is FaithFi: Faith & Finance?
FaithFi: Faith & Finance is a personal finance app designed to connect money management with Christian principles. It typically offers educational content, budgeting guidance, devotionals, and practical resources intended to help users make thoughtful financial decisions. The app is aimed at people who want to improve their financial habits while reflecting on generosity, stewardship, saving, spending, and long-term financial responsibility.
What features can I expect from FaithFi: Faith & Finance?
The app focuses on faith-based financial education rather than functioning only as a conventional banking or budgeting tool. Depending on the current version, users may find articles, podcasts, videos, devotionals, financial lessons, budgeting resources, and guidance inspired by biblical stewardship. Before downloading, check the official store listing because available tools, content categories, subscriptions, and account requirements can change with updates.
Is FaithFi: Faith & Finance suitable for beginners in personal finance?
Yes, FaithFi can be useful for beginners because its content is generally presented in an accessible, encouraging way instead of assuming advanced knowledge of investing or financial planning. It may help users think through budgeting, debt, saving, generosity, and financial priorities. However, it should be viewed as educational guidance, not a replacement for personalized advice from a qualified financial professional.
Does FaithFi: Faith & Finance connect to my bank accounts?
FaithFi: Faith & Finance is primarily known as a faith-based financial education and content platform, so users should not automatically assume that it provides bank synchronization or account aggregation. If a specific version includes budgeting or connected-account features, review the permissions, supported institutions, privacy policy, and security information carefully before enabling them. Never share banking credentials outside the app’s approved secure process.
Is FaithFi: Faith & Finance free to download and use?
The app may be free to download while offering some content at no cost and reserving additional resources, courses, or features for subscribers or members. Pricing, trial periods, and available content can vary by platform and region. Before installing, review the Google Play or App Store listing for current in-app purchase details, renewal terms, cancellation instructions, and whether an account is required.











