

Expense IQ Money Manager
3.2FinanceUpdated October 2, 2026
Screenshots
Pros
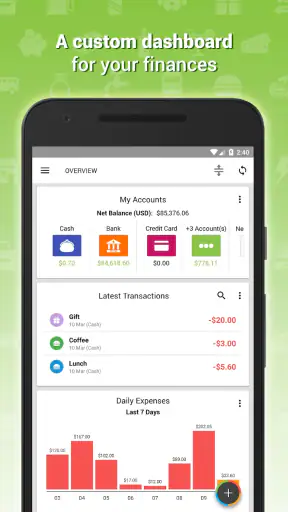
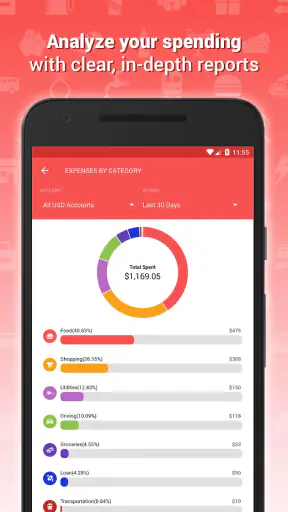
- Clear charts make spending patterns easy to understand.
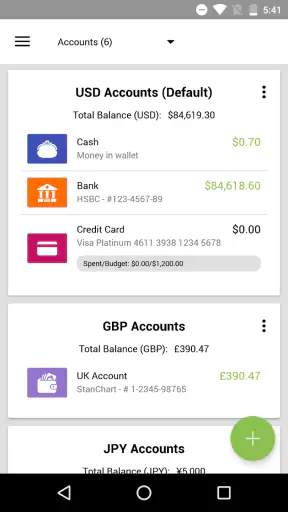
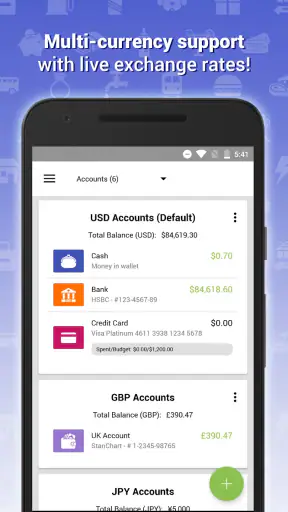
- Supports multiple accounts
- cards
- and cash wallets.
- Recurring transactions help track regular bills automatically.
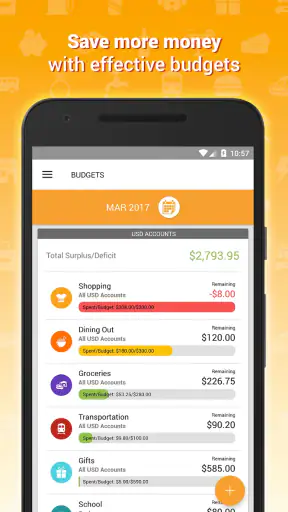
- Budget alerts can encourage better control of monthly spending.
- Useful search and filtering tools simplify transaction management.
Cons
- Some advanced features may require the premium version.
- The interface can feel dated compared with newer finance apps.
- Manual transaction entry may become tedious for frequent purchases.
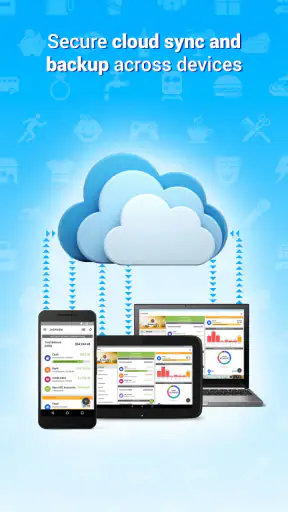
- Cloud sync and backup options may not meet every user’s needs.
- Limited bank integration can require extra manual tracking.
 Analysis By Mobexer
Managing money sounds simple until small purchases, recurring bills, cash withdrawals, and shared expenses start landing in different places. I tested Expense IQ Money Manager as a personal finance app from Handy Apps, and my impression is that it works best when you treat it as a daily record rather than a magic solution. It gives you a practical place to enter spending, plan a budget, and keep upcoming bills visible, but the value depends heavily on consistent setup and accurate entries.
The app is free to download and is suitable for everyone, with optional in-app purchases ranging from $3.49 to $124.99 per item. It has been available since May 14, 2014, and the current version is 2.3.2 for devices running Android 4.4 or later. Its average rating is 3.2 from around 23 thousand ratings, while the app has passed one million installs. Those figures suggest a sizeable audience, but also a mixed experience, so I paid particular attention to the points where a user can become confused or blame the app for a setup problem.
Getting past the points where money tracking usually breaks
Why the first few minutes matter more than they seem
The first challenge with Expense IQ is not entering a purchase. It is deciding how you want your financial life represented inside the app. If you rush through the initial setup, later reports and budget totals can become difficult to interpret. A grocery purchase entered under one account, a cash withdrawal treated as an expense, and a later cash payment recorded again can make your spending appear higher than it really is.
I recommend beginning with a small, realistic structure. Add the accounts you actually use, such as a bank account, a card, and a cash balance, rather than creating a separate account for every purpose. Then decide which expenses deserve their own categories. A category for household bills is useful; separate categories for every individual provider may create unnecessary maintenance unless you genuinely need that detail.
This is one of the less obvious trade-offs in a money manager: more categories feel more precise, but they also increase the chance that you will hesitate before saving a transaction. If recording a coffee takes too much thought, you will eventually stop recording coffees. A slightly broader category system that you use every day is more valuable than a perfect system abandoned after a week.
Checking the basics before blaming a missing total
When a balance looks wrong, I would first inspect the transaction date, account, category, and amount. These four fields explain many apparent errors. A payment entered into the wrong account can make one balance too high and another too low. A future bill entered with today’s date can distort the current month. A refund recorded as an expense instead of income can also affect the budget in an unexpected direction.
It helps to enter one transaction and immediately look at the account balance before adding a batch of older purchases. This creates a simple checkpoint. If the balance changes as expected, continue with the next entries. If it does not, correct the first transaction while the cause is still obvious. Importing or entering a large backlog without checking intermediate results makes troubleshooting much harder.
Another useful habit is to distinguish transfers from spending. Moving money from a bank account to a card is not the same as buying something with the card. Treating both actions as expenses can double-count the same money. Expense IQ can only reflect the logic you give it, so the important question is not merely “Did I enter this?” but “What kind of movement was this?”
Making the bills reminder useful instead of noisy
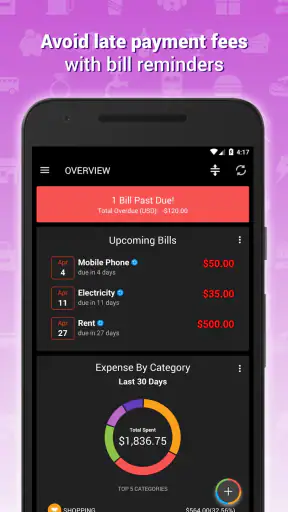
The bill-planning side is most helpful when it shows obligations you might otherwise forget. I would start with bills that have a fixed rhythm and meaningful consequences if missed, such as rent, utilities, subscriptions, or loan payments. Do not fill the reminder area with every minor purchase. A long list of low-value reminders can make important dates harder to notice.
For variable bills, use a cautious estimate rather than pretending the amount is always identical. When the real payment arrives, update the transaction with the amount actually charged. This keeps the planning view useful without turning an estimate into a false record. It also gives you a clearer picture of how much room remains in the month.
A practical workflow is to review upcoming bills before payday, then review completed payments a few days later. The first check is for preparation; the second is for reconciliation. These are different tasks, and combining them often leads to forgotten entries. The reminder feature is therefore not a replacement for checking your bank account. It is better understood as a personal prompt that supports a routine.
What to check when the app appears not to save your work
If a transaction seems to disappear, I would avoid entering it repeatedly. First return to the relevant account or date range and check whether the entry was saved under a different category or date. Search and filtering choices can make a valid transaction temporarily invisible, especially when you are looking at a limited period.
Next, close and reopen the relevant screen, then verify the account balance and recent activity. If the problem continues, record the exact sequence that caused it: which account was selected, whether the amount was edited, and whether the entry was new or recurring. That information is far more useful than simply saying that “the app lost a transaction.”
I would also be careful before clearing app data, reinstalling, or changing devices. Financial records are not ordinary disposable notes. Before taking a destructive troubleshooting step, make sure you understand how your records are being retained and whether you have a dependable copy or recovery method available. A clean reinstall may remove the visible symptom while creating a much bigger problem.
Recovering from an untidy month
Many people install a finance app after realizing that their spending has become difficult to follow. In that situation, trying to reconstruct every purchase from several months at once is discouraging. I found a staged approach more practical: begin with the current month, enter the major recurring items, then add recent card and cash activity in manageable groups.
When you discover an old mistake, correct the original transaction instead of adding a compensating entry unless there is a clear reason to preserve both records. Extra “fix” transactions can hide the real source of the problem and make later reviews confusing. Keep notes for unusual corrections, especially when a refund, reimbursement, or shared purchase is involved.
For shared expenses, decide whether you are tracking the full purchase or only your personal share. Either choice can work, but switching between them will make your reports inconsistent. If a friend owes you money, recording the entire restaurant bill as your own spending may be useful for cash-flow tracking, while recording only your share may better represent personal consumption. The right choice depends on what question you want the app to answer.
When the app is not the cause of the problem
Not every balance mismatch comes from Expense IQ. A bank transaction may still be pending, a card payment may appear before the final amount is settled, or a merchant may use a different posting date from the purchase date. Cash is even harder to reconcile because there is no automatic transaction trail to compare against.
For that reason, I would not expect the app to mirror a bank account perfectly at every moment. Use the bank or card statement as the financial source of truth, and use Expense IQ as your organized personal record and planning tool. If the two disagree, compare them line by line rather than assuming the app is wrong.
Phone-level issues can also look like app failures. A device with very little free storage, an interrupted update, or a temporary operating-system problem may affect saving or displaying information. General checks such as restarting the phone, confirming that the application is current, and testing again with a small non-critical entry are sensible first steps. I would not use a test transaction involving a real bill or a large amount.
Where this finance app fits against simpler alternatives
Compared with a paper notebook, Expense IQ offers a more structured way to connect transactions, budgets, and bills. Compared with a basic notes app or spreadsheet, it is more convenient for repeated personal entries because the information is organized around money rather than free-form text. That makes it appealing to someone who wants more guidance than a blank spreadsheet but does not want to build a financial system from scratch.
Its limitation is that structure creates responsibility. A spreadsheet user can invent exactly the columns and formulas they want, while a notebook user can adapt instantly to unusual situations. Expense IQ is strongest for a person who accepts its account-and-category approach and is willing to maintain it. It is less suitable for someone who wants every financial detail to update automatically with no manual review, or for someone who needs advanced investment analysis rather than everyday expense control.
The free entry point is helpful for trying the workflow before spending money. However, the optional purchases mean I would inspect the available upgrade details inside the app before assuming that every desired capability is included at no cost. I would not pay simply because a dashboard looks attractive. First use the basic recording routine long enough to see whether you actually maintain it.
Who will get the most from Expense IQ
I think the app suits people who want a clear view of ordinary household spending: groceries, transport, bills, cash, and discretionary purchases. It can also help someone who repeatedly forgets due dates, provided they are willing to enter and review reminders. A student, a first-time budgeter, or a household manager may appreciate having spending and planned obligations in one place.
It is particularly useful for people who make many small purchases and only notice the total at the end of the month. Entering those purchases individually can reveal patterns that a single bank balance cannot. The insight is not just that money was spent, but where the repeated small decisions are consuming room in the budget.
I would be more cautious recommending it to someone who needs effortless synchronization, complex shared finances, detailed investment tracking, or a highly customized reporting system. A dedicated service may be better for those needs. Likewise, if you know you will not record cash purchases or review bills, installing another tracker will not solve the underlying habit.
A realistic weekly routine
Imagine that I use one bank account, one payment card, and cash during the week. On the day I receive income, I review the planned bills and make sure the budget leaves enough room for fixed commitments. During the week, I enter purchases soon after making them, selecting the account that actually paid. When I withdraw cash, I record the movement separately from the later cash purchases so the same money is not counted twice.
At the weekend, I compare the app with recent bank and card activity. I correct dates or categories while the receipts are still easy to remember, then check whether the remaining budget looks realistic. If a bill was higher than expected, I do not simply ignore the difference; I adjust the record and decide which flexible category must absorb it.
This routine takes more discipline than checking a single account balance, but it produces a more useful answer: not only how much money remains, but whether that amount is already committed. That distinction is where Expense IQ earns its place for me. The app is not doing the financial thinking on my behalf; it is making the information easier to arrange.
My practical verdict after using its workflow
Expense IQ Money Manager is most convincing as a hands-on daily ledger with budgeting and bill planning attached. I like that it encourages a complete view of personal money instead of focusing only on one purchase or one account. The combination can make ordinary financial decisions less vague, especially when upcoming obligations compete with flexible spending.
Still, the experience is only as reliable as the setup. Wrong account selections, duplicated transfers, careless dates, and neglected cash entries can produce misleading results. Those are not dramatic flaws, but they are real friction points, and the average rating of 3.2 reflects that this will not be a perfect fit for everyone.
My recommendation is to start small, test the account logic with a few harmless entries, and build the budget around habits you can actually maintain. Use the app alongside your bank statements rather than treating it as an automatic authority. If you want a manual system that is more organized than notes and less open-ended than a spreadsheet, the free version is worth trying. If you want zero-maintenance tracking or specialized financial analysis, I would choose a different tool instead.
In short, this is a useful finance app for a user who is prepared to participate. It can turn scattered spending into a readable routine, but it cannot compensate for skipped entries or unclear decisions. After the initial setup is done carefully, its best quality is not flashy automation; it is the steady visibility that comes from recording money in a consistent way.
FAQ
What is Expense IQ Money Manager used for?
Expense IQ Money Manager is a personal finance app designed to help you track spending, organize income and expenses, monitor account balances, and understand your financial habits. During use, its main value comes from bringing transactions, budgets, bills, and reports into one place, making it easier to see where your money goes and plan upcoming payments.
Does Expense IQ Money Manager support budgets, bills, and recurring transactions?
Yes, the app is built around more than simple expense entry. You can create spending categories, set budget limits, record recurring income or payments, and receive reminders for bills or other scheduled transactions. These tools are particularly useful for users who want regular control over household costs, although the amount of automation available may depend on the app version and selected features.
Can I synchronize Expense IQ Money Manager across devices or back up my data?
Expense IQ Money Manager may provide backup, restore, or synchronization options so that financial records are not limited to one device. Before relying on it as your only record, check the current app settings and store description for the exact cloud, export, and device-transfer capabilities available in your region. It is also sensible to create periodic backups of important financial information.
Is Expense IQ Money Manager safe for recording personal financial information?
The app can be useful for managing sensitive details such as account balances, transaction notes, and spending patterns, so privacy should be considered before entering data. Review the developer’s current privacy policy, requested permissions, security options, and backup practices before downloading. Avoid storing unnecessary passwords, card security codes, or other information that the app does not need for budgeting.
Is Expense IQ Money Manager free, and are there premium features?
Expense IQ Money Manager may be available as a free download while offering optional premium tools, depending on the platform and current release. Basic tracking can be enough for casual users, but advanced reports, additional customization, synchronization, or an ad-free experience may require a purchase or subscription. Check the Google Play or App Store listing for the latest pricing and feature restrictions before installing.











