

Ditch: Pay Off Debt Faster
4.8FinanceUpdated October 2, 2026
Screenshots
Pros
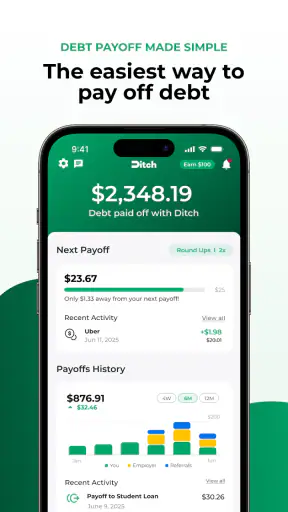
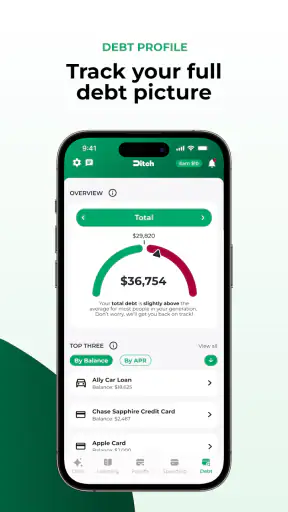
- Clear payoff tracking makes debt progress easy to monitor.
- Supports focused repayment planning for multiple debts.
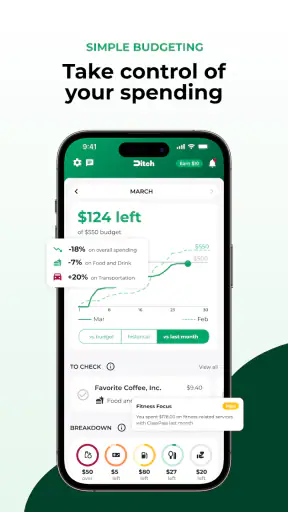
- Simple interface keeps daily financial tasks manageable.
- Visual progress can encourage consistent repayment habits.
- Useful for users seeking a debt-focused budgeting tool.
Cons
- May require manual updates if account syncing is unavailable.
- Limited value for users without outstanding debt.
- Some features may be restricted to a paid plan.
- Does not eliminate interest or negotiate with creditors.
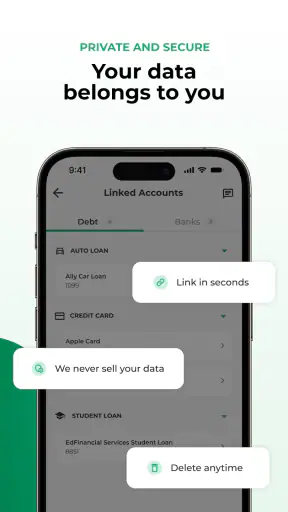
- Sensitive financial data requires careful attention to privacy settings.
 Analysis By Mobexer
Debt payoff tools are most useful when they turn a vague financial worry into a routine I can actually follow. That is the promise I see in Ditch: Pay Off Debt Faster, a finance app from Ditch Technologies, Inc. It is free to install, aimed at Everyone, and built around automating payoff planning and keeping debt progress visible. After spending time with it, I would describe it as a focused companion for people who need structure more than another complicated spreadsheet.
My first impression is that the app makes sense for someone managing several balances and struggling to decide what deserves attention first. The difficult part of debt is often not understanding that payments matter; it is maintaining a consistent plan when bills, due dates, interest, and everyday spending compete for attention. Ditch is designed to put that plan in one place. Its store summary, “Automate Payoff & Track Debt,” is brief, but it points to the two jobs the app is trying to handle: organizing repayment and helping users follow it over time.
The app has earned a 4.8 average from around 1.1 thousand ratings and has passed 10 thousand installs, which suggests that its straightforward approach is connecting with a meaningful group of users. It was released on September 12, 2023, and the current version is 1.5.6. Those details matter less than the day-to-day experience, but they do place Ditch among newer, purpose-built finance tools rather than long-established banking apps.
Getting past the first points of friction
Why setup can feel harder than the payoff plan
The first hurdle with any debt tracker is not usually the repayment method. It is entering information carefully enough that the plan reflects real life. A balance that is slightly wrong, a payment date that is misunderstood, or an account that is left out can make the result feel unreliable. I would approach Ditch with the mindset that the initial setup is financial housekeeping, not a quick form to rush through.
Before opening the app, I would gather the current balance, minimum payment, interest information, and next due date for each debt I want to track. Having those details nearby reduces interruptions and makes it easier to spot an accidental omission. If I were entering information from memory, I would be more likely to create a plan that looks tidy but does not match my statements.
A useful way to begin is with only the debts that are currently active and relevant to the payoff goal. Adding every old account, closed balance, or informal obligation at once can make the screen harder to interpret. Once the main plan is behaving as expected, I would add anything else that genuinely belongs in the picture. This staged approach is one of the simplest ways to separate a setup mistake from a problem with the app itself.
I also would not treat an automated plan as permission to stop checking statements. Ditch can help me organize what I know, but the lender remains the source of truth for the actual balance, payment status, fees, and interest. If those records change, the tracker needs to be kept current. That is a normal limitation of a planning tool, and it is especially important for anyone expecting a debt app to replace a bank account.
Checks that prevent confusing results
When a payoff projection seems surprising, I would first review the inputs rather than assume the calculation is broken. A minimum payment may have changed, an introductory rate may have ended, or a payment could have been applied differently by the lender. The most helpful habit is to compare the app’s entries with the latest statement one account at a time.
I would also check whether the intended extra payment is realistic for the whole month. A plan can look encouraging when it assigns every spare dollar to debt, but it becomes frustrating if groceries, transport, or an irregular bill then force me to miss the target. In my experience, a slightly less ambitious amount that I can repeat is more useful than an impressive target that collapses after one unexpected expense.
Another practical check is to decide what “paid off” means for the plan. Some people want to eliminate the smallest balance quickly because visible progress keeps them motivated. Others care more about reducing interest and want to concentrate on the most expensive balance. Ditch is most useful when I make that priority clear to myself before judging the result. The app can support a repayment routine, but it cannot choose the emotional or financial trade-off for me.
What to do when the workflow seems stuck
If an entry does not appear to save, a payment does not seem reflected, or a screen behaves unexpectedly, I would avoid repeatedly entering the same information. First I would leave the section and return to it, then check whether the value is displayed correctly. Repeated submissions can make it harder to tell whether the issue is a delay, a duplicate entry, or a genuine failure.
The next sensible step is to close and reopen the app, then confirm that the device has a stable connection if the action depends on online access. I would also make sure the installed version is current, since Ditch is actively identified by version 1.5.6 and an older installation can behave differently from the current release. These are simple checks, but they resolve many ordinary app hiccups without risking the underlying plan.
If the problem concerns a number rather than the interface, I would compare the entry with the lender’s statement before changing anything. A debt tracker should not be “corrected” merely because its estimate differs from a bank’s live figure. The safer workflow is to identify which value is authoritative, update the plan deliberately, and then observe whether the payoff path makes sense again.
Recovering a plan after missed payments or changed circumstances
Real budgets rarely follow a perfect line. If I missed an extra payment, received a lower paycheck, or had to use money for an urgent expense, I would not discard the entire Ditch plan. I would treat the setback as a reason to review the next manageable payment and continue tracking from there. A debt tool is more valuable when it helps me resume than when it only looks good during a perfect month.
For a recovery routine, I would compare the planned payment with the amount I can safely send now, verify the next due date with the lender, and then revise my expectations. I would avoid pretending that an old target is still affordable. The point of tracking is to make the next decision clearer, not to preserve a projection that no longer matches my budget.
This is also where the app’s automation-oriented approach needs realistic boundaries. Automating a plan can reduce mental effort, but it should not encourage blind transfers or payments that leave essential bills uncovered. I would keep a small buffer for ordinary surprises and review the plan whenever income or fixed expenses change. That balance between consistency and flexibility is more important than chasing the fastest theoretical payoff.
Where Ditch fits in everyday money management
A realistic monthly scenario
Imagine I have several debts, receive my paycheck near the end of the month, and usually lose track of which balance should receive extra money. I could use Ditch at the start of the month to review the balances, confirm the minimum obligations, and decide what additional amount is safe. After the required payments are covered, I would use the app as a progress reference rather than opening multiple lender sites just to remember the overall direction.
Later in the month, an unexpected repair might reduce the money available for debt. Instead of abandoning the plan, I would check the remaining budget, lower the extra amount if necessary, and keep the record aligned with what I can actually do. The benefit is not that the repair disappears; it is that the debt decision becomes a deliberate adjustment instead of an anxious guess.
At the next statement cycle, I would compare the recorded balances with the lender’s figures. If the difference comes from interest or a fee, I would update the relevant information and continue. This monthly check is a non-obvious but important part of using a tracker well: the app can show progress, but the user still has to reconcile that progress with real accounts.
Who is likely to benefit most
Ditch is a good match for someone who wants a dedicated debt payoff workspace without building formulas in a spreadsheet. It should appeal to users who feel overwhelmed by several balances, people who need a visible routine to stay motivated, and anyone who prefers a focused finance app instead of a broad budgeting platform filled with unrelated sections.
It may also help couples or households that have agreed on a repayment goal but need a shared point of reference during monthly money conversations. Even without turning the process into a formal financial meeting, a clear list of priorities can make it easier to discuss what is realistic. I would still confirm sensitive figures together, because a tracker only reflects the information entered into it.
The free entry point is another reason I would suggest trying it before committing to a more elaborate financial service. However, the app includes in-app purchases ranging from $5.99 to $89.99 per item. That means I would pay attention to what is available without payment and what requires an upgrade before building my entire routine around a paid capability. The presence of purchases does not make the app unsuitable, but it does make checking the value of any optional feature important.
Who should choose another kind of tool
I would not make Ditch my only financial tool if I needed full household budgeting, investment tracking, bill negotiation, or direct banking management. A bank app is better for confirming transactions and payment status. A detailed budgeting platform may be better for assigning every expense to a category and forecasting cash flow across an entire household. A spreadsheet may be preferable for someone who wants complete control over formulas and custom scenarios.
I would also be cautious if my debt situation involves legal collection activity, disputed charges, or complex tax consequences. A payoff tracker can organize information, but it is not a substitute for advice from a qualified financial or legal professional. Likewise, anyone who expects automatic changes to lender accounts should verify exactly what the app can do before assuming that tracking and payment execution are the same thing.
The trade-off between simplicity and control
The strongest part of Ditch is its narrow focus. I do not have to turn debt repayment into a full financial-management project just to see what I should work on next. That simplicity lowers the barrier to returning to the app regularly, which is where a payoff plan gains practical value.
The trade-off is that a focused tool may feel limiting to users who want deep customization. If I enjoy building alternative scenarios, modeling irregular income, or combining debt with detailed savings targets, I may eventually want a spreadsheet or a broader platform beside it. Ditch works best as the clear debt layer in my routine, not necessarily as the entire financial system.
Privacy-minded habits and safe use
Because debt information is sensitive, I would use ordinary caution when entering account details into any finance application. I would keep my device protected, avoid documenting unnecessary identifying information in notes, and review the app’s own prompts carefully rather than assuming that every field is required for the payoff plan. I would also avoid sharing screenshots that expose balances or account references.
My safest habit would be to use Ditch for organization while confirming important actions through the lender. Before sending a payment, I would check the official account. Before assuming a balance is cleared, I would wait for the lender’s confirmation. This two-source routine adds a little effort, but it prevents a planning display from being mistaken for proof that a transaction has settled.
How the app compares with familiar alternatives
Compared with a paper list, Ditch offers a more active way to think about repayment because the information is arranged around progress rather than simply written down. Compared with a spreadsheet, it should be easier for someone who wants a ready-made debt-focused workflow and does not want to maintain formulas. The spreadsheet still wins when I need unusual rules, extensive customization, or a full audit trail.
Compared with a general budgeting app, Ditch’s advantage is concentration. A broad budget can tell me where money is going, but it may not keep the payoff goal at the center of attention. On the other hand, a general budgeting app may be the better choice if overspending is the main reason debt keeps growing. In that situation, tracking repayment without understanding cash flow could treat the symptom rather than the cause.
The best combination for some users may be a bank app for transaction truth, a budget for spending control, and Ditch for the repayment path. That is not unnecessary duplication if each tool has a distinct role. The mistake would be entering conflicting numbers and then trusting whichever screen looks most encouraging.
My practical verdict
After looking at the app as a real part of a monthly routine, I see Ditch as a useful, approachable option for people who want debt payoff to feel more organized. Its free price makes experimentation easy, its Everyone age rating keeps the audience broad, and its purpose is clear enough that I would not need a long learning period to understand the basic idea. The 4.8 average and roughly 1.1 thousand ratings also show that many users have responded positively to that focused approach.
I would recommend it to a friend who has several debts, keeps postponing repayment decisions, and wants a dedicated place to turn intentions into a repeatable plan. I would tell that friend to prepare accurate figures, start with the active debts, reconcile the plan against statements, and avoid setting an extra payment that leaves no room for normal life. Those habits will matter as much as the app itself.
I would not recommend relying on it alone for banking, comprehensive budgeting, or complicated financial decisions. The app can make the path easier to follow, but it cannot guarantee that a lender’s balance is current, that a payment has settled, or that a chosen strategy fits every household. Its value comes from disciplined use: enter carefully, review regularly, recover calmly after changes, and treat official account records as final.
Overall, Ditch is most convincing when I use it as a practical debt dashboard rather than a magic shortcut. It gives repayment a place in my routine, helps me see the next decision, and can reduce the mental clutter around multiple balances. For users who want that focused support, it is worth trying. For users who need a complete financial command center, a broader alternative will probably serve them better.
FAQ
What is Ditch: Pay Off Debt Faster, and how does it work?
Ditch: Pay Off Debt Faster is a debt-management app designed to help you organize outstanding balances and create a clearer repayment plan. After entering information such as balances, interest rates, minimum payments, and due dates, the app can help you understand your overall debt and compare repayment strategies. It is primarily a planning and tracking tool, not a lender or a service that automatically removes debt.
Can Ditch help me decide which debt to pay first?
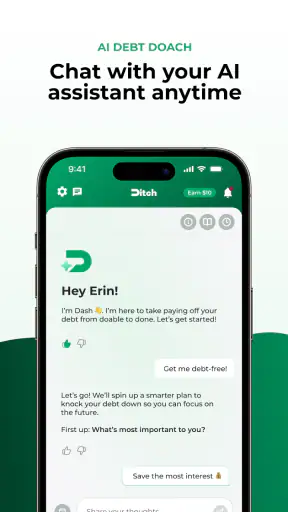
Yes, the app is intended to make repayment priorities easier to understand. Depending on the information and options available in your version, it may help you compare approaches such as focusing on the highest-interest balance first or paying off the smallest balance for quicker psychological wins. The best method depends on your interest rates, fees, income, and personal goals, so its suggestions should support—not replace—your own financial judgment.
Do I need to connect my bank accounts or provide sensitive financial information?
The amount of information required can depend on the app version, platform, and features you choose to use. Some users may be able to enter debts manually, while other functions could involve connecting financial accounts or sharing additional details. Before continuing, review the app’s privacy policy, permissions, data-storage practices, and any third-party connections. Avoid entering information you are uncomfortable sharing, and use strong device and account security.
Is Ditch free to download, and are there subscriptions or in-app purchases?
The app may be available to download without an upfront charge, but certain planning tools, premium features, or advanced guidance can be offered through subscriptions or in-app purchases. Pricing, trial periods, renewal terms, and available features may vary by country and change over time. Check the current Google Play or App Store listing before downloading, and confirm the subscription details carefully so you understand when and how you may be charged.
Can Ditch pay my bills automatically or guarantee that I will become debt-free faster?
Ditch should be viewed as a budgeting and repayment-planning companion rather than a guarantee of financial results. Unless your version specifically supports an authorized payment feature, you remain responsible for making payments to each creditor on time. The app cannot eliminate interest, negotiate every account, or promise a particular payoff date. Results depend on your income, spending habits, debt terms, and ability to follow the repayment plan consistently.











