

Deferit: Split Bills, Pay in 4
4.6FinanceUpdated October 2, 2026
Screenshots
Pros
- Helps spread eligible bills across several scheduled payments.
- Payment reminders can reduce the risk of forgetting important due dates.
- Useful budgeting overview for recurring household expenses.
- Simple interface makes setting up a bill relatively straightforward.
- May help manage cash flow without using a traditional credit card.
Cons
- Approval and available limits may vary between users.
- Late or missed payments can lead to fees or account restrictions.
- Not every bill or service provider may be supported.
- Splitting payments can make recurring expenses harder to track.
- Terms
- fees
- and eligibility should be checked before relying on the service.
 Analysis By Mobexer
When a bill arrives at the wrong moment, the problem is often timing rather than the total amount. That is the situation Deferit is designed to address. It is a finance app from Deferit that lets eligible users divide bills into four smaller payments without interest, rather than handling the full amount in one transaction. I found the idea easy to understand, but its usefulness depends heavily on how carefully you manage the repayment schedule.
Deferit: Split Bills, Pay in 4 is free to download and aimed at everyone from an age-rating perspective. It runs on Android devices using Android 7.0 or later, and the current version is 3.0.6. Those details make it accessible to people using older phones, although the quality of your experience will still depend on your device and the way the latest app version behaves on it.
How the bill-splitting approach works in everyday life
A simple idea with a very specific purpose
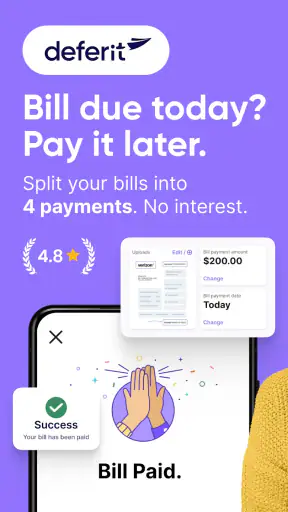
The central appeal is straightforward: instead of paying a bill in one go, I can spread it across four payments with no interest. That makes the app different from a normal budgeting tool. A budgeting app helps me plan money, while Deferit focuses on smoothing out the timing of a bill that is already due or needs attention.
That distinction matters. If I have enough money overall but my payday falls after a utility bill is due, splitting the payment may help me avoid an uncomfortable shortfall. If I do not have enough income to cover the bill and the later repayments, however, the app does not solve the underlying problem. It only changes when the money leaves my account.
I would therefore treat it as a short-term cash-flow tool, not as extra income. The four-part structure can make a large payment feel more manageable, but every installment still needs to fit into the weeks that follow. The most useful habit is to look at the complete repayment schedule before accepting anything and compare it with rent, food, transport, subscriptions, and other fixed commitments.
What “free” means here
The app itself is free, which removes an upfront purchase barrier. That is useful for someone who wants to explore the service without paying to install a finance application. The interest-free billing model is also an important part of the value proposition: the appeal is not simply spreading a payment, but doing so without interest.
Still, I would not read “free” as a guarantee that every possible situation has no cost or consequence. Financial products can have eligibility rules, repayment conditions, and account requirements, so I would review the terms shown inside the app before relying on it for an urgent bill. The confirmed benefit is the absence of interest on the four-payment arrangement; that should not be casually extended into a promise that every related circumstance is costless.
This is one of the first questions I would answer before using it: am I comfortable with the repayment commitment, not merely the fact that downloading the app costs nothing? If the answer is no, a conventional payment plan agreed directly with the bill provider may be easier to understand and control.
A realistic household example
Imagine that my electricity bill arrives just before several other monthly expenses. I could use the app to divide that bill into four smaller payments, then mark each future payment on my calendar. The immediate benefit would be breathing room in the current week. The important follow-up would be checking that the next three installments do not collide with another large bill.
In that example, the app is most valuable when I already know my income pattern and can reserve the money in advance. I would keep the installment amount in my weekly budget rather than treating the first payment as the end of the problem. A separate note in my banking app or calendar can help me remember the remaining dates, especially if I use Deferit only occasionally.
The less comfortable version of the same scenario is using one split payment to cover another because the first repayment has not been planned. That can create a chain of obligations. My practical advice is to use the service for a clear timing mismatch, not to cover a repeated gap between income and essential spending.
Where it fits among familiar alternatives
The usual alternative is paying the bill directly from a bank account or card. That option is simpler when the money is already available and avoids adding another repayment schedule. Direct payment is also better for someone who wants fewer financial accounts and fewer dates to track.
Another alternative is asking the bill provider for its own extension or payment arrangement. That may be preferable when the provider offers a plan tailored to the account, because the arrangement is handled at the source of the bill. A standard budgeting app is another option, but it will not replace the bill-splitting function; it can help me save ahead of time rather than divide a bill after it arrives.
Deferit sits between those choices. It is more targeted than a general budget planner and potentially more convenient than negotiating every bill separately. Its advantage is strongest when the bill is suitable for the service and the four-payment rhythm matches my income. Its advantage is weaker when I can simply pay in full or when I need a longer, more flexible arrangement.
Small workflow choices that make a big difference
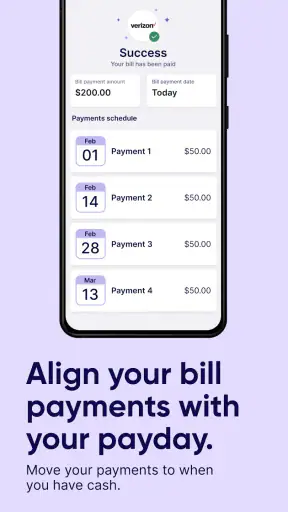
The first useful workflow is to review the calendar before submitting a bill. I would check the next four payment dates against paydays and other automatic withdrawals. This is more important than the initial approval screen because the real test is whether the later installments remain comfortable.
The second is to separate essential and discretionary bills in my own planning. Using a split arrangement for an essential household bill can be understandable when the timing is temporary. Using it for optional spending deserves more caution, because the purchase may feel small now while the repayment still competes with necessities later.
The third is to keep a record outside the app. I would save the bill name, the total, and each expected payment date in a calendar or budget note. That is not a criticism of the product; it is a sensible safeguard whenever a financial service creates a new schedule. It also makes it easier to notice whether several split arrangements are active at the same time.
A fourth insight is that “no interest” should be compared with the full commitment, not just the first payment. Interest-free financing can be genuinely useful, but only if the arrangement remains manageable. The absence of interest does not remove the need for discipline, and it does not make a bill affordable when the total is beyond the household budget.
What I liked about the value
The strongest value is clarity of purpose. Deferit is not trying to be a complete banking replacement or an all-purpose money manager. It focuses on a familiar pain point: a bill that is due before the money needed to pay it has arrived. That narrow focus makes the service easier to judge than a finance app with a long list of unrelated tools.
The four-payment format is also easier to picture than an open-ended debt arrangement. I know from the start that the bill is being divided into a limited number of parts, and the interest-free structure keeps the basic calculation simple. For someone who carefully tracks cash flow, that predictability can be more helpful than using a credit product with a less obvious final cost.
The app has also attracted a substantial user base. It has more than a million installs, an average rating of 4.6 from around twenty thousand ratings, and roughly two thousand reviews. Those figures suggest that many people find the concept useful, although they should not replace checking whether the service fits my own circumstances.
Where the experience needs caution
The main friction is psychological: a smaller first payment can make a bill feel cheaper than it really is. I have to actively remind myself that the full obligation remains. This is especially important when several bills arrive close together and each one appears manageable on its own.
There is also a practical risk in depending on an app for a time-sensitive bill. I would not wait until the final minute to begin the process. A delayed review, an eligibility issue, or a problem with the bill details could leave less time to find another solution. The safest approach is to start early and keep a backup payment method available for essential services.
Another limitation is that the service is not automatically the best answer for every bill. If I can pay in full without affecting necessities, direct payment is simpler. If I need a longer period than four installments, this structure may feel too tight. If my income is unpredictable, even a small scheduled payment can become stressful when several commitments overlap.
I would also avoid assuming that a strong public rating means a frictionless result for every user. Ratings reflect many individual experiences, while financial suitability is personal. Someone with regular income and one temporary bill problem may benefit greatly; someone already juggling multiple repayments may find the same product adds pressure.
Who is likely to get the most value
I think the best fit is a person with a temporary cash-flow mismatch, a reliable plan for upcoming income, and a bill that can reasonably be handled through four interest-free payments. The app may also suit someone who wants a focused bill solution rather than a conventional credit card or a broad personal-finance platform.
It can be particularly practical for households that budget by payday. Instead of treating the full bill as a single hit, I can assign one installment to each part of the coming schedule. That only works if the budget includes the repayment before discretionary spending. The app should support a plan I already understand, not replace one.
I would be more cautious if my income changes from week to week, if I regularly miss scheduled payments, or if I am already using several buy-now-pay-later arrangements. In those cases, speaking directly with the bill provider or getting help from a qualified financial counselor may be more appropriate than adding another repayment stream.
The app is also not ideal for someone who dislikes managing digital financial services. If I want every bill paid immediately and every transaction kept in one familiar account, a direct bank payment may be less mentally demanding. Convenience is personal; dividing a bill can reduce one kind of stress while creating another through extra tracking.
Questions I would settle before relying on it
Before using it, I would first confirm that the specific bill and account are accepted through the current app flow. The general concept is clear, but suitability depends on the bill I am trying to handle and the conditions presented during the process. I would also read the payment schedule carefully rather than assuming every bill follows an identical experience.
I would then check how the four payments fit with my actual income dates. A plan that looks comfortable in isolation may become difficult when combined with rent, groceries, transport, or another installment. Writing the dates down is a quick way to expose that problem before committing.
I would also ask myself whether I need flexibility beyond the four-part arrangement. If the answer is yes, I would compare the service with a direct provider arrangement or a budgeting plan instead. The interest-free feature is attractive, but a plan that is too short can still be the wrong plan.
Finally, I would decide what happens if my circumstances change. Keeping a small buffer, avoiding several simultaneous arrangements, and retaining a backup way to pay an essential bill are sensible precautions. Those steps do not make the app less useful; they prevent a convenient tool from becoming the only support holding a fragile budget together.
My verdict on Deferit
My view is positive but deliberately narrow. Deferit offers real value when I need to divide a bill into four interest-free payments and have a dependable plan for completing them. The free access and focused design make it worth considering for a temporary timing problem, especially when paying the full amount today would disrupt essential spending.
I would skip it when I can comfortably pay the bill directly, when I need a longer arrangement, or when my budget is already relying on several future payments. In those situations, simplicity or direct negotiation may be safer than adding another schedule.
Overall, I see it as a useful financial tool rather than a financial rescue. The best results come from treating the first payment as the beginning of a commitment, not as a discount. If I check the dates, keep the total in view, and use it only for a manageable short-term gap, the app’s interest-free four-payment approach can be genuinely helpful.
With its Everyone rating, Android compatibility from version 7.0 onward, and current version 3.0.6, it is accessible to a broad range of users. My recommendation is therefore conditional but clear: try it if your problem is timing and your repayment plan is solid; choose a simpler or more flexible alternative if the underlying issue is that the bill is unaffordable.
FAQ
What is Deferit: Split Bills, Pay in 4?
Deferit is a bill-management and payment service designed to help users handle eligible expenses when they cannot pay the full amount immediately. Depending on availability in your region, the app may let you pay certain bills in installments, split a purchase into several payments, or organize upcoming obligations in one place. Features, limits, fees, and supported billers can vary by country and account eligibility.
How does Deferit’s Pay in 4 or bill-splitting feature work?
After creating an account and completing any required verification, you select an eligible bill or purchase and review the repayment schedule shown in the app. The total amount is divided into scheduled installments, commonly four payments, rather than being paid all at once. Before confirming, carefully check the due dates, payment amounts, applicable fees, and any consequences of a missed payment.
Are there fees or interest charges when using Deferit?
Deferit’s costs depend on the specific service, your location, the type of bill, and the terms presented during checkout. Some transactions may include a subscription, convenience fee, late fee, or other charge, while others may have different pricing. The app should display the relevant costs before you accept a plan, so review the final repayment total instead of assuming every transaction is interest-free.
What bills, purchases, and payment methods does Deferit support?
Support is not universal, and available billers or purchase categories may differ by country and change over time. The app may accept selected utilities, telecommunications, insurance, government-related bills, or other recurring expenses, depending on its current partnerships. You should confirm eligibility inside the app before downloading or relying on the service, and check whether your preferred debit card, bank account, or other payment method is supported.
What happens if I miss a Deferit installment or cannot complete repayment?
Missing an installment can result in additional fees, restricted access to future plans, unsuccessful bill payments, or other account consequences described in Deferit’s terms. It may also create problems if the original bill remains unpaid. If you expect difficulty, contact Deferit through its official support channels as soon as possible, review the hardship or repayment options available, and avoid taking another plan simply to cover an existing obligation.











