

Común: Your money, your way
4.8FinanceUpdated October 5, 2026
Screenshots
Pros
- Simple interface makes everyday money management easy.
- Useful tools help organize spending and keep financial goals visible.
- Personalized features adapt to different money habits and needs.
- Clear transaction information improves awareness of where money goes.
- Convenient mobile access lets you manage finances from almost anywhere.
Cons
- Some features may depend on your country
- bank
- or account type.
- New users may need time to understand all available financial tools.
- Notifications can feel excessive if several alerts are enabled.
- Advanced budgeting options may be limited for experienced users.
- App performance may vary on older devices or slower connections.
 Analysis By Mobexer
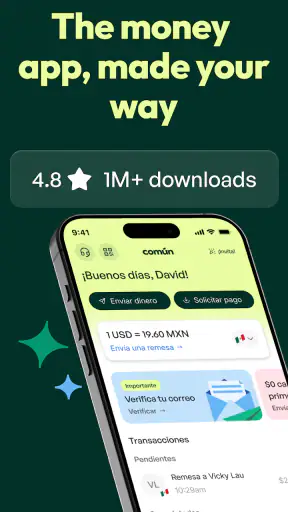
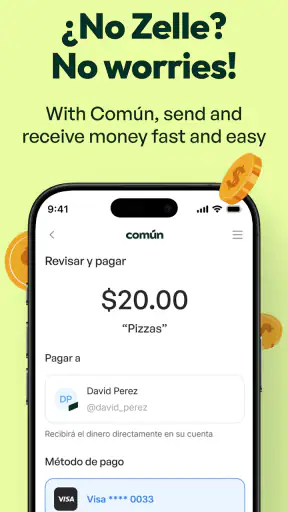
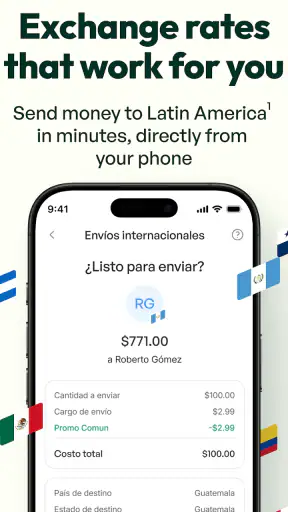
I approached Común as a practical finance app rather than just another digital wallet. Its promise is straightforward: pay other people, send money to Latin America, and use a Visa debit card. In everyday use, that combination makes it interesting for people whose financial life crosses borders, especially when a traditional bank feels too slow or complicated for a simple transfer.
What I like most is that the app is built around actions people actually repeat. You are not opening it merely to inspect a chart or read financial education content. You are opening it because someone needs to be paid, money has to move to family in Latin America, or you want to use a debit card connected to the same financial setup. That focus gives the experience a clear purpose.
Común is a free finance app from Comun, available for users aged Everyone. It has reached more than 500 thousand installs, with an average score of 4.8 from around 22 thousand ratings and roughly 2.7 thousand written reviews. Those figures suggest that the app has found a real audience, although a high store rating should be treated as a starting point rather than proof that every transfer or card interaction will feel perfect for every person.
How Común feels when money needs to move quickly
Speed expectations for ordinary payments
The first thing I would expect from Común is a short path between opening the app and completing a basic money task. Its purpose is narrower than a full-service banking application, so the interface benefits when it keeps attention on payments, transfers, and the Visa debit card. For a routine payment to another person, that focused design is more useful than a crowded dashboard filled with unrelated financial products.
Still, “fast” in a finance app has two meanings. The app itself can respond promptly while the actual movement of money depends on the transaction route, the recipient, and any checks required along the way. I would not judge the experience only by how quickly a confirmation screen appears. The important question is whether the status is clear afterward and whether I know what to do if the recipient does not see the money immediately.
That distinction matters particularly for Latin America transfers. A cross-border payment is not the same as handing cash to a friend. Before sending, I would double-check the recipient details, the destination, and the final amount. A few extra seconds spent reviewing the transfer can prevent a much longer recovery process later. The app’s value is strongest when it reduces friction without encouraging careless taps.
A realistic everyday scenario
Imagine that I live in the United States and need to send money to a relative in Latin America after receiving a message that a household expense is due. With Común, I would want to open the app, select the transfer route, verify the recipient information, review the amount, and save the confirmation. I would then tell my relative what I sent and when, rather than assuming that a completed screen automatically means the money is already available on their side.
For a second task, I might use the Visa debit card for a normal purchase instead of moving money separately into another service. That is where the app’s combined approach becomes convenient: sending money and spending through a card can live in one place. The trade-off is that I would rely more heavily on one account, so I would keep an alternative payment method available for an important purchase or travel day.
Where heavy use changes the experience
Común may feel particularly useful during busy periods when several small financial tasks happen close together: paying a friend, checking a transfer, and using the debit card on the same day. A focused app can be easier to navigate than a traditional bank application that mixes checking, savings, loans, investments, and promotional messages. I would expect the lighter scope to help me find the action I need without much searching.
However, heavy use also exposes the parts that a quick first impression cannot show. If I were sending several transfers, I would review each confirmation rather than relying on memory. I would also avoid treating the app as a running ledger unless the transaction history gives me enough detail for that purpose. For budgeting, I prefer recording important payments in a separate system as well, because a payment tool and a complete personal-finance tracker are not necessarily the same thing.
Another practical tip is to separate urgent transfers from routine spending in my own notes. If I use the card several times and send money abroad on the same day, it becomes easier to confuse one transaction with another. Keeping the recipient, purpose, and amount written down gives me a simple reference if I need to investigate a status later. This is not glamorous, but it is the kind of habit that makes a financial app safer to use.
Reliability, recovery, and the limits of convenience
What I would look for when something goes wrong
Reliability in finance is not only about avoiding crashes. It is also about making uncertain moments understandable. If a transfer appears delayed, I want to know whether it is pending, completed, or needs attention. If a card payment is declined, I want enough context to decide whether to retry, use another card, or contact support. A clean interface is helpful, but clear status information matters more than visual polish.
My advice would be to keep confirmation details for transfers that matter. A screenshot or saved record can help when coordinating with a recipient, especially across time zones or languages. I would not send a second payment simply because the first one is not visible yet. Duplicating a transfer is one of the easiest ways to turn a temporary delay into a real financial problem.
The same caution applies to changing recipient information. I would treat a new recipient as a separate verification task, even if the name looks familiar. Before confirming, I would compare the details with the message or conversation where the request originated. This is a useful workflow for any money-transfer app, but it is especially important when the payment crosses borders and recovery may be less straightforward than canceling a local payment.
Who will appreciate the recovery mindset
Común is a good fit for someone who wants a more direct way to pay people and send money to Latin America, but it still requires normal financial discipline. I would recommend it to users who are comfortable checking transaction details, watching statuses, and keeping a backup payment method. The app can simplify the process, but it cannot remove the consequences of sending money to the wrong person or spending more than intended.
I would be more cautious recommending it as someone’s only financial tool. A person who needs a broad banking relationship, extensive account management, or a mature budgeting workspace may feel more comfortable with a traditional bank or a larger financial platform. Those alternatives can be less focused, but they may better suit someone who wants every financial service under one established account.
Comparing it with the usual alternatives
Compared with a conventional bank, Común appears more focused on the immediate jobs of paying, transferring, and using a debit card. That focus can make it more approachable for a particular use case, especially when sending money to Latin America is central to the user’s routine. A bank may offer a broader account structure, but broader does not always mean quicker to understand.
Compared with a dedicated remittance service, Común has a wider everyday role because the Visa debit card and person-to-person payments sit alongside international transfers. A remittance specialist may be preferable when the only goal is sending money abroad and the user wants to compare every available transfer option. Común is more compelling when the same person also wants a card for ordinary spending.
Compared with peer-to-peer payment apps, its cross-border purpose gives it a different reason to exist. A general payment app may be excellent for splitting lunch or reimbursing a local friend, but it may not be the first tool I choose when the recipient is in Latin America. The right choice depends on where the money is going and whether I want a card connected to the same app.
Device constraints and practical setup decisions
What the operating-system requirement means
The current version is 2.29.0 and requires Android or iOS 10 or later. That is a modest technical requirement for many users, but it still matters if the app is being installed on an older phone. Before relying on Común for an urgent transfer, I would install it, sign in, and test the basic flow while I still have access to another payment method.
Finance apps are not ideal tools to test for the first time during an emergency. An older device may have limited storage, a weak battery, or an operating system that cannot receive newer updates. Even if the app installs, the broader phone environment can affect notifications, authentication, or the ability to switch between the app and a verification message. I would keep the phone updated as far as it reasonably allows and avoid uninstalling the app before confirming that I can access the account again.
Resource demands and connection habits
I would expect a focused finance app to be less demanding than a game or a media-heavy service, but I would not make assumptions about battery use or performance on every device. The important practical constraint is connectivity: transfers and card-related actions need a dependable connection and careful attention. If I am using mobile data in an unfamiliar place, I would wait for a stable signal before confirming a significant transaction.
I also prefer not to perform sensitive financial actions on a shared or unreliable device. A personal phone with a working lock screen is a better environment than borrowing someone else’s handset. If I do need to change phones, I would make sure I know my sign-in details and can complete any account verification before leaving the old device behind. This reduces the risk of being locked out at the exact moment I need access.
Notifications deserve a practical check as well. If I depend on an alert to notice a payment or transfer update, I would verify that notifications are enabled and that the operating system is not aggressively restricting background activity. I would still open the app to inspect important transactions instead of treating a notification as the complete record.
Questions I would answer before depending on it
Can it replace my bank? I would say no, not for everyone. It can cover a useful set of payment and transfer needs, but someone seeking a full banking relationship should compare it with a traditional bank before moving all financial activity into one place.
Is it suitable for sending money to Latin America? That is one of its clearest intended uses, and it is the reason I would consider it over a purely local payment app. I would still verify the recipient and review the transfer carefully every time, particularly for a first payment or a large amount.
Can I use it for normal purchases? The Visa debit card makes everyday card spending part of the experience. I would use it for routine purchases while keeping another payment option available for situations where a card transaction is especially time-sensitive.
Will an older phone run it? Devices using Android or iOS 10 or later meet the stated minimum operating-system requirement. I would test the complete sign-in and payment workflow before depending on an older handset, because installation alone does not prove that the overall experience will be comfortable.
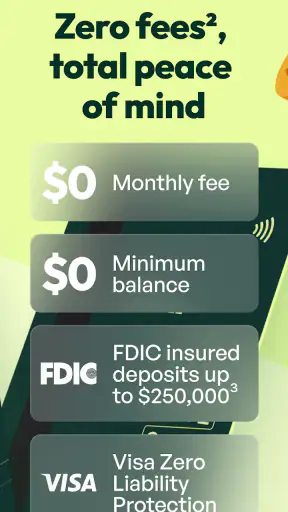
Is the free price the only thing to consider? Free access makes trying the app easier, but I would still examine the details shown during each transaction and understand the amount being sent before confirming. “Free” does not mean I should skip the review step or assume every financial route works identically.
My performance verdict after weighing convenience against control
My overall impression is that Común makes the most sense when its three central jobs overlap in one person’s life: paying others, sending money to Latin America, and using a Visa debit card. It is not trying to be an all-purpose financial command center in the way a large bank can be. That narrower identity is a strength for users who want a direct path to these tasks, and a limitation for anyone searching for a complete money-management ecosystem.
The app’s strong store reception, with a 4.8 average from around 22 thousand ratings, supports the idea that many users find the experience useful. I would interpret that as encouragement rather than a guarantee. Financial apps are judged in very personal circumstances, and the right choice depends on transfer habits, device age, preferred backup options, and comfort with checking every transaction.
For me, the best way to use Común would be deliberately: install it on a supported device, complete setup before an urgent need, start with a small familiar payment, confirm how statuses are presented, and keep a second payment method available. I would use written notes for important cross-border transfers and avoid sending a duplicate payment when a status is unclear.
My recommendation is positive for people who need a focused bridge between everyday payments, Latin America transfers, and card spending. I would skip it as a primary choice if I need extensive banking features, advanced budgeting, or a single platform for every financial product. Used for the job it is designed to handle, Común feels more purposeful than a generic wallet, and that purpose is its most convincing advantage.
FAQ
What is Común: Your money, your way?
Común: Your money, your way is a personal finance app designed to help users manage their money from one place. It may provide tools for tracking spending, organizing financial information, monitoring balances, and making more informed decisions. Before downloading, check whether its available services, supported currencies, financial institutions, and account features match your country and personal banking needs.
Is Común: Your money, your way safe to use?
Financial applications require careful attention to privacy and security. Before creating an account, review Común’s privacy policy, permissions, authentication options, and information about data protection. Use a strong, unique password and enable any available security features, such as biometric access or two-step verification. Avoid installing modified versions and download the app only from an official store or trusted source.
Does Común connect directly to my bank accounts or cards?
The available connection options can depend on your location, bank, and the version of the application. Común may support certain financial accounts, cards, or services, but compatibility should be confirmed before registration. Read the connection permissions carefully and make sure you understand whether the app can only display information or also initiate payments, transfers, or other financial actions.
Is Común: Your money, your way free to download and use?
The app may be free to download, but some features could require a subscription, service fee, transaction charge, or eligibility through a particular financial product. Pricing and availability can change by country and account type. Check the official store listing and the app’s terms before using paid tools, linking an account, or authorizing a transaction, especially if you want to avoid unexpected costs.
Who should download Común: Your money, your way?
Común may be useful for people who want a more organized way to view and manage their finances through a mobile device. It can suit users interested in budgeting, monitoring activity, or keeping financial information accessible. However, it should not automatically replace professional financial advice. Confirm that the app supports your region, language, currency, and preferred financial services before downloading.











