

Cashli: Cash Advance & Rewards
4.1FinanceUpdated October 5, 2026
Screenshots
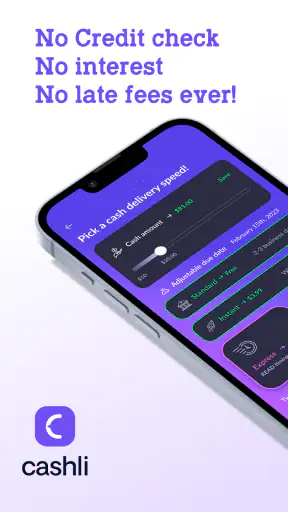
Pros
- Fast application process with a clear
- beginner-friendly interface.
- Rewards can add extra value for users who regularly engage with offers.
- Repayment details are displayed before accepting an advance.
- Useful option for managing short-term cash flow emergencies.
- Mobile access makes checking eligibility and account details convenient.
Cons
- Eligibility and advance limits may vary significantly between users.
- Fees or expedited-transfer charges can reduce the amount you receive.
- Repayment dates may arrive quickly
- leaving little room for delays.
- Rewards may require specific actions
- purchases
- or qualifying conditions.
- Availability and features can depend on your location and banking setup.
 Analysis By Mobexer
Cashli: Cash Advance & Rewards is a finance app from Cashli Funds that caught my attention because it focuses on a very specific moment: needing a small amount of money before the next payday. I approached it less like a general budgeting tool and more like a short-term cash option, asking a practical question: does it make an urgent money problem easier to handle, or does it simply move the pressure somewhere else?
My overall impression is mixed but useful. The app is free to install, aimed at everyone, and has built a noticeable user base, with more than one hundred thousand installs. Its average score sits at 4.1 from roughly five thousand ratings, alongside about three thousand written reviews. Those figures suggest that plenty of people find value in it, but they also tell me not to treat it as a universally smooth solution. Cashli can make sense in a narrow situation, yet it deserves a careful look before you rely on it for recurring expenses.
How Cashli feels in its current state
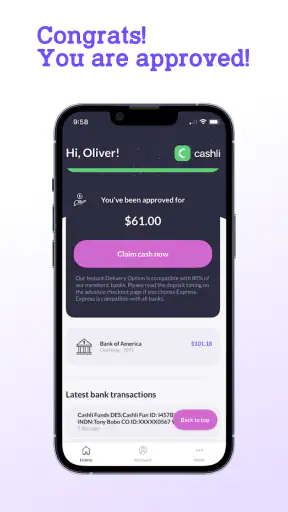
The central appeal is straightforward: Cashli presents itself as a way to access up to 150 dollars when financial worries are pressing. That makes it different from a traditional banking app, where the main job is usually checking balances, moving money, or tracking spending. Here, the important question is whether the app can help bridge a temporary gap without turning a one-time problem into a habit.
I think the app is easiest to understand when you place it beside familiar alternatives. A bank overdraft may already be available, but it can be expensive or unpredictable. A credit card can provide flexibility, although interest and minimum payments can stretch a small purchase over a long period. Borrowing from a friend avoids an app-based process, but it may feel uncomfortable and is not always possible. Cashli sits in the space between these choices, offering a dedicated cash-advance experience rather than a full financial account.
That narrow focus is both its strength and its limitation. I would not open Cashli expecting detailed household budgeting, investment tools, bill negotiation, or a complete view of my financial life. I would open it when I wanted to investigate a short-term cash option and compare the app’s terms with alternatives already available to me.
The store summary speaks directly to people losing sleep over money, but I would treat that message as an invitation to investigate rather than a promise that every user will receive the same result. An advance is still money that affects a future budget. Before accepting anything, I would want to understand the repayment timing, the total cost, eligibility requirements, and what happens if my next paycheck is already committed to rent, utilities, or other essentials.
The first-use experience is about checking the details
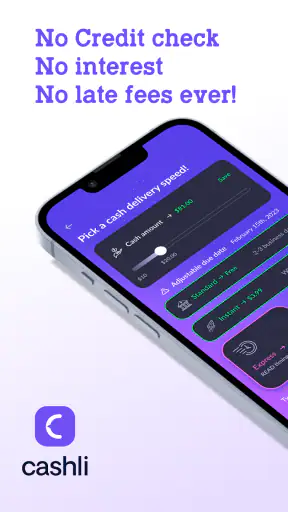
With an app like this, the most important part of the experience is not visual polish. It is the clarity of the information shown before I commit. I would pay close attention to every screen that explains the amount available, the expected repayment, any optional services, and the way rewards connect to the main cash-advance experience.
That is also where I see a useful habit for new users: take screenshots or notes of the final terms before confirming. This is not because Cashli is automatically untrustworthy; it is because short-term financial products are easy to misunderstand when someone is stressed and moving quickly. A calm review of the final amount and repayment date can prevent an avoidable surprise.
The rewards angle may make the app feel more engaging than a plain advance service, but I would not let rewards distract me from the borrowing decision. A reward is only valuable if it does not encourage unnecessary spending, repeated advances, or acceptance of terms that are worse than another option. In my view, rewards should be treated as a secondary benefit, never as the reason to take money I do not genuinely need.
What the current release tells me
Cashli is currently listed as version 1.0.19, and it runs on Android 8.0 or later. That gives the app a fairly broad device reach, which is useful for people who do not own a recent phone. The release date is July 18, 2023, so this is not a brand-new launch being tested by only a handful of early adopters. The install count and review volume show that the app has had time to reach real users and collect substantial feedback.
At the same time, I would not mistake a version number for proof that every part of the service is mature. A finance app can work reliably on an older operating system while still leaving questions about eligibility, repayment flexibility, customer support, or how clearly it explains its conditions. The current version is a useful sign of ongoing product maintenance, but it is not a substitute for reading the screens that matter to your own situation.
From a reviewer’s perspective, the most meaningful evolution is that Cashli has moved beyond being an unknown experiment. People have installed it, rated it, and written reviews. That gives prospective users more context than a launch-day app would provide. However, ratings are broad signals. They do not tell me whether a particular reviewer needed a different advance amount, lived in a different location, had different eligibility, or used the rewards side more heavily than the cash side.
How existing users may experience the update path
For someone already using Cashli, staying on the current version is sensible because financial apps often depend on changes behind the scenes as well as visible interface updates. Keeping the app current can help avoid compatibility problems, especially on an older Android device. I would still review any new permission request or revised explanation carefully instead of approving everything automatically.
Existing users should also reassess their routine rather than assuming that a familiar app is automatically the best option. If Cashli helped once during an isolated emergency, that does not mean it should become part of every pay cycle. A useful personal rule is to ask whether the next repayment can be covered without skipping essentials. If the answer is no, the advance is solving today’s shortage by creating tomorrow’s.
Another practical point is record keeping. I would save confirmation details for each transaction, including the amount received and the expected repayment information. That makes it easier to compare the app with a bank account statement and to notice if my own budget is drifting. It also prevents the rewards feature from making the overall flow feel less like borrowing and more like ordinary shopping.
Where Cashli helps, and where it still falls short
A realistic everyday situation
Imagine that a necessary expense arrives a few days before payday: a prescription, a transport repair, or a basic household purchase. I have checked my account and know the shortage is temporary, but I do not have enough cash available today. In that situation, Cashli may be worth opening because it is designed around immediate access rather than long-term financial planning.
My process would be deliberately slow. I would first check whether the expense can wait, then compare Cashli with my bank’s available options, an existing credit line, and a trusted personal alternative. If I chose Cashli, I would request only what the expense requires, not the largest amount displayed. I would then place the repayment date directly into my calendar and reserve that amount in my next budget.
This is one of the app’s better use cases: a defined, short-lived gap with a clear repayment plan. It is a poor fit for an open-ended shortage, such as regularly being unable to cover groceries, rent, or utilities. Those problems need a broader budget change, a conversation with the provider, community assistance, or professional debt advice. A cash advance can provide breathing room, but it cannot repair an income-and-expenses imbalance by itself.
Three details I would check before using it
- Look beyond the amount offered. The number available today is less important than the amount that must leave your account later. I would compare the full repayment obligation with the money I expect to have after essential bills.
- Separate rewards from borrowing. I would evaluate the cash advance on its own and only then consider whether the rewards element adds real value. This avoids treating a bonus as a discount on a decision that may still create financial pressure.
- Use it for a named expense. Writing down exactly what the advance covers makes it easier to spot repeat borrowing. If I cannot name the expense, I would pause rather than request money simply because it is available.
These steps may sound simple, but they address a less obvious risk: convenience can reduce the emotional pause that normally comes with borrowing. Cashli’s focused design may be helpful when time matters, yet that same focus can make it tempting to act before considering the next week’s obligations.
Who should consider it
I see Cashli as a possible fit for an adult who needs to investigate a modest, short-term cash advance, understands the repayment commitment, and has a realistic plan for covering it. The free download lowers the barrier to comparing the service with other choices, and the Everyone content rating makes it broadly accessible as an app. Still, accessibility should not be confused with suitability. The right question is not whether I can install it, but whether the financial arrangement fits my budget.
It may also suit someone who prefers a focused app instead of a full bank platform. If I only want to explore a cash advance and rewards rather than manage investments or build a detailed spending plan, Cashli’s limited scope can feel less cluttered. The app’s category is finance, but I would think of it as a specific financial utility, not a replacement for my bank or a complete money-management system.
Who should skip it
I would skip Cashli if I already know that my next income is fully allocated. I would also avoid using it to cover repeated shortfalls, discretionary shopping, or bills that I cannot keep up with month after month. In those cases, a budgeting service, a nonprofit adviser, a bank conversation, or a structured repayment plan may be more appropriate than another short-term advance.
People who want transparent long-term planning may also prefer a conventional budgeting app. A budgeting tool can show spending patterns and help identify where money is going; Cashli is aimed at a more immediate need. Likewise, someone who already has a low-cost emergency option through their bank should compare that option carefully before choosing a separate service.
The gaps I would like to see addressed
The biggest remaining challenge is not the basic idea. It is making every important condition easy to understand before a user accepts an advance. In financial products, clarity about repayment, eligibility, timing, and possible costs matters more than a friendly interface or a reward mechanism. I would like every user to be able to answer those questions without hunting through several screens.
I also think the product needs to be judged on what happens after the advance, not only on how quickly the request begins. A strong experience should help users stay aware of the upcoming repayment and understand their ongoing choices. If the app encourages repeat use without helping people recognize the pattern, convenience becomes a weakness.
The rating of 4.1 indicates a generally positive reception, but not an effortless one. I read that kind of score as a reason to test the app carefully rather than dismiss it or trust it blindly. The written feedback volume is large enough to show that user experiences matter here, yet individual results can still vary. Eligibility and terms should be evaluated inside the app for the person using it, not inferred from someone else’s experience.
What I would watch in future releases
For future updates, I would watch for clearer explanations around the complete borrowing journey: what a user sees before requesting money, how repayment is presented, and how the app helps prevent accidental overuse. I would also look for improvements that make rewards easier to understand without blurring the difference between earning something and taking on an obligation.
Another area worth watching is support for people who change their mind or encounter a problem. The best financial apps make the next step obvious when a user needs clarification, notices an error, or wants to review a transaction. I would value practical guidance and visible records more than extra promotional features.
The current Android requirement of 8.0 or later is helpful for compatibility, but future development should continue balancing broad device support with strong security and a dependable experience. As the app evolves, I would judge it by whether updates improve confidence and control, not simply by whether the version number increases.
My final recommendation
After looking at Cashli as a real financial tool rather than a quick fix, I would recommend it cautiously to someone facing a clearly defined, temporary cash gap. Its free availability, focused purpose, and established user presence make it worth comparing with the usual alternatives. I would install it to inspect the offer, but I would not accept an advance until the repayment details fit comfortably into my budget.
My strongest advice is to use Cashli as an emergency comparison point, not as an extension of your regular income. Request the smallest necessary amount, separate the rewards from the borrowing decision, save the transaction details, and set aside the repayment immediately. Those habits turn the app from an impulse option into a considered one.
For ongoing financial stress, I would choose a broader solution instead. Cashli can help with a short bridge, but it cannot replace income planning, debt support, or a sustainable budget. Its value depends less on how quickly it offers cash and more on whether you can repay it without creating a second problem. That is why I see it as potentially useful, but only for the right situation and with a clear limit on how often I use it.
Cashli: Cash Advance & Rewards is developed by Cashli Funds, remains free to install, and is available for Android devices running 8.0 or later. Its current version, 1.0.19, shows an active product rather than a forgotten release. I would keep it on my shortlist for comparing short-term options, while making sure a bank facility, a personal emergency fund, or a non-borrowing form of support is not safer and cheaper for the problem in front of me.
FAQ
What is Cashli: Cash Advance & Rewards, and how does it work?
Cashli: Cash Advance & Rewards is a financial app designed to help eligible users access cash advances and potentially earn rewards through selected activities or offers. After installing the app, users generally create an account, provide requested personal and financial information, and review any available advance options. Availability, limits, fees, repayment terms, and reward opportunities can vary by user, location, and eligibility, so read the in-app disclosures carefully before accepting anything.
Is Cashli: Cash Advance & Rewards a legitimate loan app, and is it safe to use?
Cashli should be evaluated like any other financial service rather than treated as free money. Before signing up, check the developer information, privacy policy, security practices, customer support details, and the permissions requested by the app. Only download it from an official app store, use a strong password, and avoid sharing account credentials or verification codes. Carefully review the company’s terms and authorization requests before connecting a bank account.
How much money can I receive through Cashli, and how quickly is it deposited?
The amount and delivery speed of a cash advance are normally determined after Cashli reviews your eligibility and the information submitted in your profile. New users may receive different limits from returning users, and approval is not guaranteed. Standard transfers may take longer, while faster delivery—if offered—could involve an additional charge. The app should show the advance amount, total repayment, timing, and any applicable fees before you confirm.
What fees, repayment rules, or other costs should I expect?
Before accepting an advance, examine the complete cost rather than focusing only on the amount deposited. Depending on the offer and your location, Cashli may disclose service fees, optional expedited-transfer charges, subscription-related costs, or other expenses. Confirm the repayment date, payment method, cancellation rules, and consequences of a failed or late payment. Never proceed if the total repayment amount or withdrawal schedule is unclear.
How do the rewards work, and can I withdraw them as cash?
Cashli’s rewards may be connected to activities such as completing eligible offers, meeting promotional requirements, or using specific features within the application. Rewards usually have conditions, limits, expiration dates, and verification requirements, so they may not be available immediately. Read each offer’s terms before participating, especially details about qualifying purchases, personal-data sharing, minimum withdrawal thresholds, and whether rewards can be converted to cash or are limited to another form of credit.











