

Cash Advance – Quick Borrow
4.8FinanceUpdated October 5, 2026
Screenshots
Pros
- Simple application process with minimal paperwork
- Quick eligibility checks can save time
- Clear repayment information before accepting an offer
- Useful for covering unexpected short-term expenses
- Available from a mobile device at any time
Cons
- Approval is not guaranteed for every applicant
- Loan availability may depend on your location
- Late payments can lead to additional fees or penalties
- Short repayment periods may be difficult to manage
- Personal and financial data must be shared with the app
 Analysis By Mobexer
When an unexpected bill lands between paydays, the hardest part is often not finding a borrowing app but deciding whether borrowing is sensible at all. I approached Cash Advance – Quick Borrow as a decision tool rather than a magic fix. It belongs to the finance category, is free to install, and is designed to collect cash advance and personal loan offers through an online request. That makes it potentially useful when speed matters, but it also means the important question is not simply whether the request feels easy. The real question is whether the offer, repayment timing, and total cost suit your situation.
My overall impression is that this app is best treated as a convenient starting point for comparing available borrowing options, not as permission to borrow without checking the details. TIMECORE Studio has kept the concept focused: open the app, review the borrowing route available to you, and decide whether moving forward makes sense. I like that straightforward purpose, although people who need a full budgeting system, a savings tracker, or long-term debt management will probably need a different kind of finance app.
How I would judge the app before requesting money
The first decision criterion is urgency. If the need is genuinely time-sensitive, an online request can be more practical than visiting a branch or making several phone calls. A broken appliance, an essential transport expense, or a bill that cannot reasonably wait are situations where a quick way to explore an offer may have value. I would still separate “I need money today” from “I want to buy something today.” The former may justify research; the latter is usually a reason to pause.
The second criterion is clarity. Before accepting anything, I would look for the amount offered, the repayment schedule, the total amount to be repaid, and every applicable charge. A cash advance can appear manageable when viewed only as a short-term amount. The repayment obligation is what belongs in the household budget. If the app leads you toward an offer, read the lender’s final terms rather than relying on the initial impression created by the request process.
The third criterion is fit. A short-term advance and a personal loan are not interchangeable. An advance may address a small timing gap, while a personal loan may be structured for a larger planned expense. The right choice depends on the amount, the repayment period, and your ability to meet the payments without using another loan to cover them. I would not use this app to solve a recurring monthly shortfall; that pattern calls for a budget review and possibly advice from a nonprofit debt service.
There is also a practical privacy decision. Any financial request deserves careful attention to the screens asking for personal information. I would check the app’s permissions and privacy information before entering details, use a secure connection, and avoid completing a request on a shared device. These are not reasons to dismiss the app, but they are part of responsible borrowing. Convenience should never replace knowing where your information is going or which party will make the final lending decision.
The app has an average rating of 4.8 from around 935 ratings, with 27 written reviews and over 10K installs. Those figures suggest that early users have generally responded well, but they should not be mistaken for a guarantee that every applicant will receive an offer or find the terms suitable. A positive app experience and a suitable financial product are two separate judgments.
What the request process is good at
The strongest part of the concept is the reduction of initial effort. Instead of beginning with a random internet search for lenders, I can use one finance app to explore cash advance and personal loan possibilities. That is particularly helpful for someone who does not know which borrowing category matches an immediate need. The short description, “Cash Advance,” sets a narrow expectation, while the broader purpose includes personal loan offers as well.
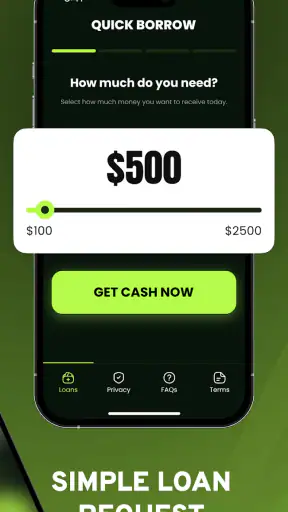
One useful habit is to decide the maximum amount before opening the request. Without that limit, an available offer can quietly become the amount you accept. I would write down the exact bill or expense, subtract any money already available, and request only the remaining gap. This small step turns the app from an impulse tool into a controlled comparison step.
Another practical technique is to take a screenshot or note the key terms before leaving the offer screen, provided doing so is allowed by the app and lender. I would record the repayment dates, total repayment, and any fee wording in a private note. That makes it easier to compare the offer with a bank overdraft, a credit-union option, an employer advance, or a payment arrangement with the bill provider. The advantage is not merely speed; it is having the terms in front of me while considering other choices.
I would also use the app at a calm moment rather than during the final minutes before a payment is due. Rushing encourages people to focus on approval and ignore repayment pressure. If the request is started earlier, there is more time to contact the creditor, ask for an extension, or compare a lower-cost alternative. The app may help with discovery, but the best outcome can sometimes be avoiding a loan altogether.
A realistic everyday situation
Imagine that a necessary household repair costs more than the money available until payday. I would first ask the repair provider whether a delayed payment or staged invoice is possible. If that fails, I would open Cash Advance – Quick Borrow, set a strict borrowing ceiling based on the repair cost, and review any available cash advance or personal loan offer. Before accepting, I would place the repayment dates beside rent, utilities, food, and transport costs in my budget.
If the repayment would leave too little for essentials, I would stop there. A fast request is not a successful result if it creates a second emergency. If the payment fits comfortably and the terms are clear, the app may have done its job by helping me examine an option quickly. Notice that the useful workflow includes alternatives before and after the app; the application is one part of the decision, not the entire decision.
Where this app wins, and where another route may be better
Its advantage over searching lender by lender
Compared with manually visiting several lender websites, the app offers a more focused first step. I do not have to begin with a vague search and sort through unrelated pages. The borrowing purpose is immediately visible, which can be reassuring for a person who needs to understand the difference between an advance and a personal loan.
That simplicity is valuable for users who are comfortable reading terms but do not want to spend an evening organizing a search. It can also help someone prepare questions for a lender. For example, after seeing an offer, I would ask whether the repayment is one payment or several, whether the amount can change, and what happens if the due date falls before my next income arrives. The app makes those questions more concrete.
Its free price is another practical advantage at the installation stage. I can examine the borrowing pathway without paying to download the application. That does not mean the borrowing itself is free, so I would keep the distinction clear: the app costs nothing to install, while an accepted financial offer may carry its own repayment obligations and charges.
Why a bank, credit union, or creditor may still be preferable
For an existing bank customer, speaking directly with the bank may be better when the need is predictable and the customer already understands the account terms. A credit union may also be worth checking, especially for someone who values a local relationship and can wait for a more deliberate evaluation. I am not claiming either option will always be cheaper or faster; the point is that a familiar provider may offer context that a quick online request does not.
For a bill that is already overdue or nearly due, contacting the creditor can be the smartest alternative. A utility company, medical provider, landlord, or service provider may have a payment arrangement that avoids borrowing. This route takes a phone call or message, but it can be financially cleaner than adding a new repayment obligation. I would compare that possibility before accepting an offer simply because it is available.
People with repeated cash shortages should skip this app as a routine solution. A borrowing application can cover one gap, but it cannot repair a budget in which essential expenses consistently exceed income. In that situation, a budgeting app, debt counselor, benefits adviser, or direct conversation with creditors is more appropriate. Likewise, someone seeking investment tracking, bill reminders, credit education, or savings automation will not find this focused borrowing tool to be a substitute for a broader money-management application.
Important friction before accepting an offer
The main limitation is that a request is not the same as guaranteed money. The app can help present borrowing possibilities, but the final result depends on the applicable lender and the terms shown during the process. I would not plan a payment around money that has not actually been approved and made available. If a bill is due soon, keep a backup plan ready.
Another limitation is emotional rather than technical. The promise of a quick request can make borrowing feel smaller than it is. I would avoid opening the app while shopping, late at night, or immediately after receiving a stressful bill. Write down the need first, calculate the repayment room, and then use the app. That order protects the decision from urgency.
There is also a switching cost when moving from a familiar financial provider to a new offer. You may need to learn a new payment schedule, remember another account, and monitor a separate obligation. Even if the initial process is simple, the loan remains part of your monthly administration until it is repaid. I would add the due dates to a calendar and keep the repayment amount visible in the household budget.
Cash Advance – Quick Borrow runs on Android seven or later, which makes it accessible to people using relatively older supported devices. Its current version is 1.0.7, and the app is rated for Everyone. Those details make the entry barrier modest, but they do not remove the need to keep the operating system updated and protect the phone with a lock screen. Financial apps deserve the same care as banking applications, even when their purpose is narrower.
Questions I would answer before downloading
Is it suitable for a first-time borrower? It can be a reasonable place to begin learning what kind of offer may be available, provided the user reads every term and understands the repayment plan. I would not recommend accepting an offer simply because the application feels easy. A first-time borrower should also compare a creditor arrangement, a trusted bank, or a credit union where possible.
Can it replace an emergency fund? No. An emergency fund reduces the need to borrow; this app helps explore borrowing when a need has already arisen. If you use it after every unexpected expense, the pattern may become expensive and stressful. I would treat any successful borrowing experience as a reason to rebuild a small cash buffer afterward, not as evidence that future advances will always be manageable.
What should someone do if the offer is unsuitable? Leave it unaccepted and compare alternatives. The app does not need to be deleted merely because one offer does not fit, but there is no benefit in forcing a decision. Contacting the bill provider, asking an employer about available assistance, or delaying a nonessential purchase may be better than accepting terms that strain the next pay cycle.
Is the app better than a traditional lender? It is better for quickly exploring an online request when speed and convenience are important. A traditional lender may be better when you want an established relationship, in-person explanation, or a product designed around a longer planning horizon. Neither route wins automatically. The deciding factors are total cost, repayment pressure, transparency, and how much time you have.
My recommendation for different types of users
I would recommend trying the app to a careful Android user who has a specific, necessary expense, wants to explore a cash advance or personal loan offer, and is willing to compare the repayment terms before committing. The free installation and focused design make it a practical first stop. I would especially value it when I need to organize options quickly but still have enough time to review a creditor arrangement or another provider.
I would recommend skipping it to anyone looking for free money, guaranteed approval, or a way to cover an ongoing income shortfall. I would also steer away from it if the repayment would require missing rent, food, utilities, or another essential obligation. In those cases, borrowing can postpone the problem while increasing its size.
My preferred workflow is simple: define the exact need, check non-borrowing alternatives, use the app to inspect an offer, write down the full repayment commitment, and compare it with a bank, credit union, creditor arrangement, or personal support option. Only then would I decide. The app is most useful when it improves your comparison process, not when it shortens your thinking.
Cash Advance – Quick Borrow from TIMECORE Studio earns a place on my shortlist as a focused finance app for exploring quick borrowing possibilities. Its strong early reception, free access, and narrow purpose are appealing, but the quality of the experience ultimately depends on the offer and on the user’s repayment plan. I would use it as a research doorway and a backup option, never as an automatic answer to every financial surprise.
FAQ
What is Cash Advance – Quick Borrow, and how does it work?
Cash Advance – Quick Borrow is a financial app designed to help eligible users request short-term borrowing options through a mobile device. After creating an account, you generally provide personal and financial information, choose an available amount, and submit a request for review. Approval, loan terms, fees, and funding speed depend on the provider’s assessment and your location, so review every offer carefully before accepting it.
Who can use Cash Advance – Quick Borrow, and what information is required?
Eligibility requirements can vary according to your country, state, age, income, employment status, banking history, and the lending partners available through the app. During registration, users may be asked for identification details, contact information, income data, employment information, and bank account details. Only submit accurate information through the official application, and check the privacy policy to understand how your data is collected and shared.
How quickly can I receive money through Cash Advance – Quick Borrow?
The app may provide a convenient way to submit a borrowing request, but approval and delivery are not guaranteed or necessarily immediate. Processing time can depend on identity verification, lender review, banking institutions, weekends, holidays, and the selected transfer method. Some users may receive funds quickly after approval, while others may experience delays. Always confirm the expected funding date and any expedited-transfer charge.
What fees, interest, and repayment terms should I check before accepting an offer?
Before accepting any advance or loan, carefully review the annual percentage rate, interest, origination charges, subscription costs, late fees, transfer fees, and the total amount you will repay. Short-term borrowing can become expensive if repayment is delayed or renewed. Make sure you understand the payment schedule, automatic-debit authorization, cancellation rules, and consequences of missed payments. Never rely solely on an advertised starting rate.
Is Cash Advance – Quick Borrow safe to use, and what should I do to protect myself?
A finance app should be treated as a service that handles highly sensitive personal and banking information. Download Cash Advance – Quick Borrow only from an official app store, verify the developer, read recent user reviews, and inspect the requested permissions. Avoid sharing passwords or verification codes, use a strong unique password, and monitor your bank account. Be cautious of anyone requesting upfront payment or promising guaranteed approval.











