

Cash Advance Now - PayDaySay
4.6FinanceUpdated October 2, 2026
Screenshots
Pros
- Fast application process with minimal paperwork
- Clear repayment terms shown before accepting an offer
- May help cover urgent expenses between paychecks
- Available online without visiting a physical branch
- Useful for borrowers with limited traditional credit options
Cons
- Interest and fees can make borrowing expensive
- Approval and terms vary by state and personal information
- Late payments may lead to extra charges or collection activity
- Not suitable as a long-term solution for recurring expenses
- Requires sharing sensitive financial and personal details
 Analysis By Mobexer
Cash Advance Now - PayDaySay is a finance app built around a simple, urgent need: finding a small amount of money before payday. I approached it as the kind of tool someone might open when an unexpected bill, transport cost, or grocery gap cannot wait. That makes convenience important, but it also means the app deserves a more careful look than an ordinary budgeting tool. Borrowing is a decision with consequences, so I paid attention not only to how quickly the process feels, but also to where a user may need to slow down and check the details.
The app is free to install and comes from PayDaySay. It has an Everyone content rating, works on Android devices running version 6.0 or later, and its current version is 1.26. Its audience is clearly people looking for a payday cash advance rather than long-term financial planning. In my view, that narrow purpose is both its main strength and its main limitation: it can be relevant in a short-term emergency, but it is not a replacement for savings, a regular banking app, or a complete money-management service.
Where the real friction usually begins
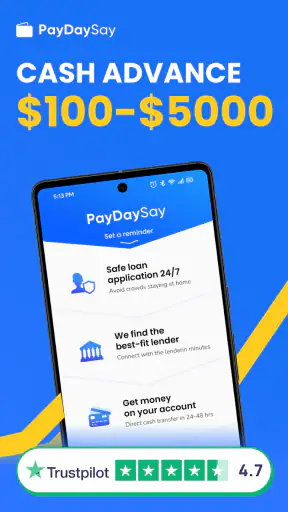
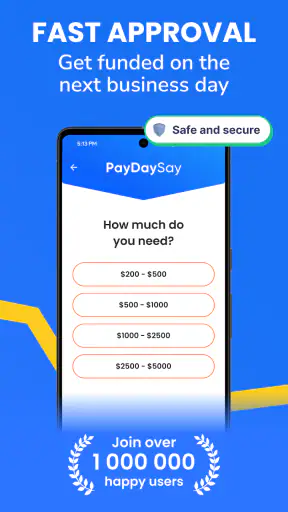
The first surprise with a cash-advance app is that installing it is usually the easy part. The harder part is understanding what happens after opening it. A user may expect to enter an amount, complete a few details, and receive money immediately. In practice, the journey can involve reviewing eligibility, entering personal information, checking repayment terms, and waiting for a decision or transfer. I would not treat the word “instant” as a promise that every person will receive funds at the same speed.
That distinction matters most when the need is time-sensitive. If rent, a utility bill, or a late-night purchase depends on the money, opening the app only minutes before the deadline leaves little room for a problem. I recommend starting the process while there is still time to read each screen carefully. A fast application is useful; a rushed application is where mistakes happen.
Another common sticking point is entering information consistently. Names, addresses, employment details, and banking information should match the records used by the relevant financial services. Even a small spelling difference or an outdated address can create extra verification work. I would keep the necessary details nearby before beginning instead of switching repeatedly between apps and guessing from memory.
There is also a difference between an application being accepted and money being available. A decision may not mean that the funds are already usable in the account. Transfer timing can depend on the financial institution and the point at which the transaction is processed. For that reason, I would never plan around the most optimistic possible arrival time, especially when a payment deadline is fixed.
The most important habit is to read the repayment information before accepting anything. The amount received is only one part of the decision. Look at the total amount to be repaid, the expected date, any applicable charges, and what happens if the repayment cannot be made on time. If a screen is unclear, that is a reason to pause rather than tap through it.
What to check before creating a borrowing plan
Cash Advance Now - PayDaySay may appeal to someone who needs a modest bridge between paydays, but the right question is not simply whether an application can be submitted. The better question is whether the repayment will fit comfortably into the next budget. If repaying the advance would leave you short for food, transport, housing, or another essential expense, the app is probably not solving the underlying problem.
I also suggest writing down the repayment date before completing the process. A calendar reminder is more useful than relying on memory, particularly if several bills are due around the same time. This small step turns an abstract borrowing decision into a concrete plan. It also makes it easier to compare the advance with alternatives such as asking a provider for a payment extension, using an existing emergency fund, or speaking with a trusted person.
The app is free to download, but that should not be confused with borrowing being free. Installation cost and loan cost are separate questions. Before accepting an offer, I would inspect every figure shown in the agreement and save a copy of the relevant information for personal records. That is practical protection if you later need to check what you accepted.
Privacy is another setup consideration. A finance application naturally asks users to handle sensitive information, so I would install it only from the official app marketplace and check that the developer name shown there is PayDaySay. I would avoid entering financial details while connected to an unfamiliar public network and would keep the device protected with a screen lock. These are simple precautions, but they matter more in a borrowing app than in a casual entertainment download.
How I would approach the application flow
I would begin by checking that the device meets the Android requirement and that the operating system is reasonably stable. The minimum supported version is Android 6.0, but older phones can still struggle because of limited storage, outdated system components, or unreliable connectivity. If the app opens but a page does not load correctly, the operating system requirement alone does not prove that the problem is with the service.
Before entering an application, I would close unnecessary apps, switch to a dependable connection, and make sure the phone has enough free space for normal operation. I would also disable any setting that aggressively restricts background activity if it interferes with receiving notifications or returning to an interrupted screen. I am not suggesting that every device needs these changes; they are sensible checks when the app behaves inconsistently.
During setup, I would use one consistent set of personal details and review each entry before moving forward. Auto-filled information can be convenient, but it is worth checking that an old address, phone number, or email has not been inserted. A typo is easy to overlook on a small screen and can be difficult to diagnose later because the resulting message may be vague.
The application should be treated as a financial form, not as a quick poll. I would read the consent language, repayment schedule, and any cost information at normal speed. If the wording is difficult to understand, I would not rely on assumptions about what a payday advance “usually” means. The exact terms displayed for the individual offer are more important than general expectations about this type of product.
One useful workflow is to capture your own notes immediately after reviewing the offer: the amount requested, the amount expected back, and the repayment date. I would not store sensitive screenshots in an exposed gallery or send them casually through messaging apps, but a secure personal record can prevent confusion. This is especially helpful if you compare the offer with a bank overdraft, a credit card, or a payment extension.
Recovering when the process does not go smoothly
If a page freezes, I would first wait briefly and check the connection rather than repeatedly submitting the same form. Multiple taps can create uncertainty about whether a request was sent once or more than once. Closing and reopening the app may help with a temporary display problem, but I would check for any confirmation or pending status before trying again.
When restarting does not help, the next sensible steps are ordinary ones: update the app through the official marketplace, restart the phone, and try a stable connection. Clearing temporary app data can sometimes resolve a damaged session, although I would be careful not to erase information that has not been recorded elsewhere. If the app shows a message about identity, eligibility, or account details, changing random settings is unlikely to fix it; reviewing the entered information is more productive.
There is an important difference between a technical failure and an application outcome. A declined request, a request for more information, or a delay in verification is not necessarily an app malfunction. Repeating the same submission will not automatically improve eligibility and could make the situation harder to understand. I would read the message carefully, keep a record of what happened, and use the app’s available support route if clarification is needed.
If the process appears to stop after submission, I would check the email address and phone notifications associated with the application, while avoiding repeated requests. Also check whether the bank account information was entered correctly and whether the receiving account is active. A transfer problem can occur after the application stage, so reinstalling the app may not address the real issue.
Reinstalling is a last resort rather than my first recommendation. It can clear local problems, but it may also remove a session or make you repeat steps. Before doing it, I would note any reference information visible in the app and confirm that I know how to sign back in. I would never provide a password, security code, or full banking credentials to someone contacting me through an unofficial channel while claiming to offer technical help.
When the phone is fine but the situation is not
Finance apps depend on more than the handset. A bank may delay a transfer, a verification service may be busy, or an account may reject incoming funds. In those cases, the app can appear to be the source of the problem even though the delay is elsewhere. I would check the status shown in the app, then contact the relevant official support channel rather than assuming that reinstalling will speed up a financial transaction.
Timing can also make a normal process feel broken. A request made outside ordinary processing periods may not move as quickly as one made earlier. Since the app is designed for short-term access to money, users may understandably expect immediate results, but I would still leave a buffer before a bill is due. If the deadline is today, I would look for a backup arrangement instead of relying entirely on an uncompleted application.
Another issue is affordability. Even if the app works exactly as intended, an advance can create pressure on the next payday. This is where Cash Advance Now - PayDaySay is not the right choice for everyone. Someone facing a recurring monthly shortfall may be better served by a debt adviser, a revised budget, a lower-cost credit option, or a conversation with the bill provider. Using a short-term advance repeatedly can mask the gap rather than close it.
For a one-off expense with a clear repayment plan, the app may be more relevant. Imagine a user whose paycheck arrives soon but whose car needs an unexpected repair to keep commuting. The app could be considered alongside asking the repair shop about timing, checking an existing emergency fund, or using another credit facility. The sensible choice depends on the total repayment cost and whether the next paycheck can cover it without creating a second emergency.
Compared with a traditional bank, this app is more focused on the immediate payday-advance use case. A bank may offer broader account tools, established transaction history, and other forms of credit, but its application process may not be designed around the same short-term need. Compared with a credit card, a cash advance app may feel more direct, yet a credit card can sometimes provide a different repayment structure. Neither comparison automatically makes one option cheaper or safer; the terms must be checked side by side.
Compared with borrowing from family or requesting a bill extension, an app can feel more private and convenient. The trade-off is that a formal financial product may carry costs and a fixed repayment obligation. I would choose convenience only after understanding that obligation. A familiar alternative with no borrowing cost may be preferable when it is available and does not create personal strain.
Who will get the most from it
The strongest audience is an adult who needs a short bridge, understands the repayment date, and can comfortably meet the full obligation from expected income. The app’s Everyone rating describes content accessibility, not financial suitability, so younger or inexperienced users should involve a trusted adult or financial professional before borrowing. The same caution applies to anyone who is already behind on several payments.
I would skip it if the amount needed is large, the expense is recurring, or repayment depends on another uncertain loan or paycheck. It is also a poor fit if you are unwilling to review the terms carefully or if you need a guaranteed arrival time. In those situations, a bank product, formal credit counseling, or direct negotiation with the creditor may be more appropriate.
The app has attracted a substantial audience, with over a hundred thousand installs, and its average rating is 4.6 from around fifteen thousand ratings. Those signals suggest that many people find the experience useful, but they do not predict an individual approval, transfer speed, or cost. I see them as evidence of interest and user experience, not as a substitute for reading the offer in front of you.
My practical verdict after weighing convenience against risk
Cash Advance Now - PayDaySay is a focused finance app for people exploring a short-term payday cash advance. I like the straightforward purpose, the free installation, and the fact that it can be considered when a small, urgent expense arrives between paychecks. The current version, 1.26, keeps it relevant for Android users who meet the operating-system requirement, while PayDaySay gives the product a clearly identified developer.
My reservation is not about the basic idea of the app; it is about the nature of short-term borrowing. The most difficult part may not be opening the application but deciding whether the repayment will make the next payday harder. Setup accuracy, stable connectivity, careful review of terms, and realistic timing all matter. If anything in the offer is unclear, I would stop and seek clarification rather than treating speed as the priority.
For a one-time cash gap with a dependable repayment plan, it is worth considering alongside other options. For ongoing financial stress, uncertain income, or a deadline that cannot tolerate delays, I would look elsewhere first. My recommendation is therefore cautious but positive: use it as a carefully checked emergency option, not as a routine extension of every paycheck.
In short, the app can be useful when the need is limited, the terms are understood, and the repayment is genuinely affordable. Convenience should come after clarity, not instead of it. That is the standard I would use before submitting any request through Cash Advance Now - PayDaySay.
FAQ
What is Cash Advance Now - PayDaySay?
Cash Advance Now - PayDaySay is a financial service app designed to help users explore short-term cash advance and personal loan options. After providing requested information, the app may connect you with lenders or financial service providers. It is not necessarily the lender itself, and approval, loan amounts, repayment terms, and interest rates depend on the provider that receives your application.
How does the Cash Advance Now - PayDaySay application process work?
The process generally begins with an online form asking for details such as your identity, employment, income, bank account, and contact information. Once submitted, your request may be reviewed and shared with a lender or matching network. If an offer is available, you should carefully review the annual percentage rate, fees, repayment schedule, and lender terms before accepting anything.
Is Cash Advance Now - PayDaySay available to everyone?
No. Eligibility can vary according to your location, age, income, employment status, banking information, credit profile, and the requirements of participating lenders. Completing the application does not guarantee approval or funding. Availability may also be restricted in certain states or regions, so users should check the current terms and eligibility conditions before submitting personal information.
How much does borrowing through Cash Advance Now - PayDaySay cost?
The cost depends entirely on the lender and the product offered. A short-term advance or personal loan may include interest, origination charges, late fees, or other costs, and the annual percentage rate can be high compared with traditional credit. Before accepting an offer, review every disclosure and confirm the total repayment amount, due dates, and consequences of late payment.
Is Cash Advance Now - PayDaySay safe to use?
The app may use security measures to handle submitted information, but users should still review its privacy policy, permissions, and terms before applying. Avoid entering sensitive details through unofficial download links or unexpected messages. Remember that financial information may be shared with lending partners or service providers, so only proceed when you understand how your data will be used and who may contact you.











