

Cash Advance - No credit Check
4.7FinanceUpdated October 5, 2026
Screenshots
Pros
- Quick application process with minimal paperwork
- No traditional credit check required for approval consideration
- Funds may be deposited directly into your bank account
- Clear repayment dates can help with short-term planning
- Useful for unexpected expenses when other options are unavailable
Cons
- High fees or interest can make borrowing expensive
- Repayment may be due very quickly
- Approval and loan amounts vary by applicant and lender
- Late payments can lead to additional charges or collection activity
- The app may share information with third-party lending partners
 Analysis By Mobexer
When an unexpected bill arrives before payday, the appeal of a cash advance app is obvious: you want to understand your options quickly, without sitting through a long financial process. I spent time examining Cash Advance - No credit Check with that situation in mind. It is a free finance app from D.J. Advance App, aimed at people looking for short-term access to cash and presenting itself as an option that does not depend on a traditional credit check.
My first impression is that this is best treated as a starting point for exploring a cash advance, not as a guaranteed solution to a money problem. The app can be useful when speed and convenience matter, but the word “free” needs to be understood carefully. Free access to an app does not automatically mean that borrowing money has no cost. That distinction is the most important thing to keep in mind before entering personal or financial details anywhere.
What the app actually offers and what “free” means
Cash Advance - No credit Check belongs to the finance category rather than banking, budgeting, or investment tools. Its store summary focuses on getting cash while waiting for payday, so its purpose is narrower than a general money-management app. I would not install it expecting spending charts, savings goals, bill tracking, or a complete replacement for a bank account. Its appeal is concentrated around the cash-advance journey.
The app itself is free to download, and it is marked for Everyone. That makes trying the interface less of a financial commitment than signing up for a paid service. However, the free download should not be confused with a free loan. Any advance, repayment arrangement, eligibility decision, service charge, or other borrowing condition should be read carefully before accepting anything. A finance app can cost nothing to install while the financial product connected to it has its own terms.
This is also why I would avoid judging the app only by its prominent promise of quick cash. The useful question is not simply whether the app opens without payment. The useful question is whether the complete offer shown to you is understandable: how much you may receive, what you must repay, when repayment is due, and whether any charges apply. If those points are unclear, I would stop rather than proceed because speed is not a substitute for transparent terms.
The app has a 4.7 average from around 35 thousand ratings, with roughly 2.8 thousand written reviews. It has also passed 500 thousand installs, which suggests that many people have at least tried it. Those figures are helpful signals about visibility and user interest, but they are not proof that every person will qualify or receive money. Approval, availability, and the final conditions can depend on the individual situation and the service shown inside the app.
It was released on December 5, 2022, and the current version is 1.1.3. Compatibility begins with Android 7.0, a broad enough requirement for many older Android phones. I like that the technical entry point is not limited to only recent devices, especially because people dealing with financial pressure may not be using the newest handset. Still, keeping the app updated is sensible when handling sensitive financial activity.
How I would approach the first session
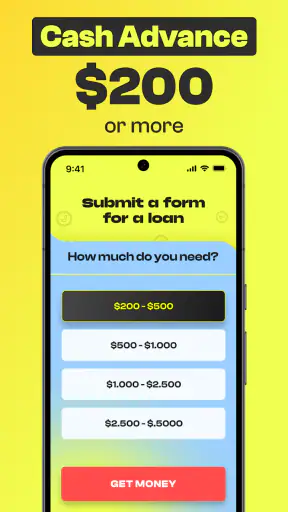
I would begin by reading the opening screens slowly rather than tapping through them just to reach the next page. In a cash-advance app, small wording changes can separate an educational explanation from an actual application step. I would note whether a screen is describing eligibility, requesting information, or asking me to accept a financial arrangement. That simple habit reduces the chance of agreeing to something I have not understood.
I would also prepare the information I genuinely need before starting. Having a clear picture of the upcoming bill, the next payday, and the amount I can realistically repay makes the app more useful. Without that preparation, the temptation is to request the largest amount available, even when a smaller advance would solve the immediate problem with less pressure later.
A less obvious but important tip is to take a private note of every repayment amount and date shown during the process. Do not rely on memory, especially if you are comparing the offer with an overdraft, a bank option, or help from someone you trust. A quick written comparison of total repayment rather than just the amount received can reveal whether the convenience is worth it.
Where the value comes from in everyday use
The main value is convenience. A person who needs to investigate a short-term cash option can begin from a phone instead of visiting a branch or searching through several unrelated services. That matters in an evening emergency, when a utility payment is due the next morning or a necessary purchase cannot wait for the normal pay cycle.
Imagine that a household appliance stops working a few days before payday. The repair is important, but the available balance is not enough. I would use this app to understand whether a cash advance route is even available, then compare the complete repayment obligation against the cost of postponing the purchase, asking the provider for more time, or using an existing bank facility. The app’s value in that situation is not merely “getting money”; it is helping me examine one possible route quickly.
That distinction makes the app more useful for organized users than for impulsive ones. If I already know the exact gap and have a firm repayment plan, a cash-advance tool may help me investigate a temporary bridge. If I am unsure how I will repay, the same convenience can make the situation worse by turning a short delay into a new obligation.
Another practical strength is that the app is focused. It does not present itself as a broad financial dashboard, so someone looking specifically into payday-related cash access may find the purpose easier to understand than in a crowded personal-finance application. The focused design can reduce searching, but it also means the app should be paired with your own budgeting method rather than used as the budget itself.
I would use a separate note, spreadsheet, or banking tool to record the advance and its repayment. That workflow is more reliable than treating the app as the only place where the obligation exists. The advance should appear in the same monthly picture as rent, food, transport, subscriptions, and existing debt. This is one of the most useful habits for avoiding the common mistake of solving today’s shortage while hiding next week’s shortage.
Comparing it with ordinary alternatives
Compared with asking an employer about an early wage option, a bank about an overdraft, or a bill provider about a payment extension, Cash Advance - No credit Check may feel faster and less intimidating. Its phone-based approach is convenient when you need to explore an option outside normal office hours. On the other hand, a familiar bank or employer program may offer clearer account history, established support, or terms that are easier for you to verify.
Compared with a budgeting app, this product serves a completely different purpose. A budget tool helps locate the cause of a shortfall and plan around it; this app is oriented toward finding short-term cash. If your problem is recurring rather than temporary, budgeting, changing payment dates, negotiating bills, or seeking reputable debt advice is likely to deliver more lasting value than repeatedly seeking advances.
Compared with a credit card, the choice depends on the complete cost and repayment structure, not on which option sounds quicker. Some people already have a card with terms they understand, while others may prefer not to increase revolving debt. I would compare the total amount repaid, the due date, and the consequences of missing payment before choosing either route. The app can be part of that comparison, but it should not make the decision for you.
The “no credit check” wording may attract people who have limited or damaged credit histories. That can be relevant, but it should not be read as a promise of approval or as evidence that repayment is unimportant. A provider may still use other eligibility information, and the final offer may not match what a user expects. I would treat the phrase as a reason to inspect the process carefully, not as a guarantee.
Tradeoffs I noticed before recommending it
The biggest tradeoff is speed versus scrutiny. A fast application can be helpful during a genuine short-term emergency, but rushing makes it easier to miss the repayment date or misunderstand the total obligation. I would never accept an offer while distracted, tired, or under pressure from a bill collector. If the page does not make the essential terms easy to locate, that friction is meaningful rather than something to ignore.
There is also a difference between eligibility and affordability. Even if an applicant can access an advance, the payment may still be difficult once normal expenses arrive. Before using the app, I would subtract the proposed repayment from the next pay cycle and check whether essentials remain covered. If that calculation leaves no room for food, housing, transport, or existing commitments, the advance is probably not affordable.
Privacy deserves the same attention as cost. A finance application may involve personal information, so I would read each permission and information request in context and avoid entering details into screens I cannot explain. I would also download only the genuine app from a trusted store and be cautious of similarly named copies. A familiar-looking icon is not enough when financial information is involved.
Support is another practical consideration. If a repayment question or application issue appears, I want to know where the explanation is located and whether the wording is clear. I would save confirmation screens and important messages for my records. This is not glamorous advice, but it matters when an app is connected to a real financial obligation and a dispute later depends on what was displayed.
The app’s free price is a positive for exploration, but it does not remove the need for comparison shopping. I would not install it because I assume “free” means the cheapest borrowing option. I would install it only to inspect the route and then compare the actual terms with alternatives I already have. That is a much safer way to evaluate its value.
Who is most likely to benefit
I think the app is most suitable for an adult who has a temporary, clearly defined cash gap, understands the next income date, and can repay without sacrificing essentials. It may also suit someone who wants to investigate a short-term option from an Android phone rather than begin with a branch visit. The broad age classification and support for Android 7.0 make it accessible from a device perspective, but financial suitability still depends on the person’s circumstances.
It can be particularly useful as a comparison step. For example, I might check the app after asking a bill provider for an extension and before deciding whether to use an overdraft. I would write down the amount received and the total repayment for each option. This turns the app from an emotional emergency button into one item in a deliberate decision process.
I would recommend extra caution for anyone already juggling several advances, credit-card balances, overdrafts, or late payments. A new advance can conceal a recurring income problem instead of fixing it. In that situation, a debt counselor, a nonprofit advice service, or a direct conversation with creditors may be more valuable than another fast-cash application.
I would also tell people with irregular income to be especially careful. A repayment date that looks manageable after one strong pay period may become difficult after a weaker one. The app may still be useful for understanding an option, but the decision should be based on the least comfortable realistic income scenario, not the most optimistic one.
Who should probably skip it
I would skip this app if I could not explain exactly how repayment would fit into my next budget. I would also skip it if I was looking for long-term debt consolidation, investment guidance, credit building, or detailed spending analysis. Those needs call for different kinds of financial tools and support.
Someone who already has a lower-cost, well-understood alternative should compare that first. A bank facility, employer program, emergency fund, or negotiated payment delay may be less convenient but more predictable. Convenience alone is not enough to justify borrowing, particularly when the amount needed is small enough to solve through a short-term adjustment.
Finally, I would stop using the app if the information requested felt unrelated to the purpose, if the terms were difficult to locate, or if the process created pressure to accept immediately. A trustworthy financial decision should leave room to read, compare, and change your mind before committing.
My buy-or-skip verdict
Because Cash Advance - No credit Check is free to download, I see it as a low-cost way to investigate a particular short-term finance route, not as a free source of money. Its strongest qualities are its focused purpose, phone-based convenience, and accessibility on older Android devices. Its most important limitation is that the convenience can encourage a rushed borrowing decision, while the real value depends on the complete terms shown to each user.
My recommendation is conditional: try it as a comparison tool if you have a genuine temporary need, a realistic repayment plan, and the patience to read every financial detail. Record the total repayment and due date, then compare them with your bank, employer, bill provider, and other legitimate alternatives. Do not let the absence of a traditional credit check replace an affordability check in your own budget.
I would skip it for recurring cash shortages, uncertain income, or any situation where the next repayment would put essentials at risk. In those cases, the better answer is usually a broader review of expenses and debts rather than another advance. For the right user, this finance app can make an urgent search more convenient; for the wrong user, that same convenience may simply postpone the problem.
Overall, I would recommend Cash Advance - No credit Check only with careful expectations. It is free to access and has attracted a strong audience, but those points should support investigation, not automatic trust. Used deliberately, it can help you explore a short-term option before payday. Used impulsively, it can turn a brief cash gap into a repayment problem, which is why my final advice is simple: understand the full obligation first, and borrow only when the next step is genuinely affordable.
FAQ
What is Cash Advance - No Credit Check, and how does it work?
Cash Advance - No Credit Check is generally presented as a financial service app that helps users explore short-term borrowing options without relying solely on a traditional credit-score review. After entering personal, employment, and banking information, the app may connect you with lenders or offer providers. Approval, loan amounts, interest rates, fees, and repayment terms are determined by the actual lender, not necessarily by the app itself.
Can I really get a cash advance without a credit check?
The phrase “no credit check” should be interpreted carefully. Some providers may use alternative information or perform a soft inquiry instead of a traditional hard credit check, while others may still review your financial history, income, or banking activity. There is no guarantee of approval, and users should read the lender’s disclosures to understand whether a credit inquiry, verification process, or additional eligibility requirements applies.
How much does the service cost, and are there hidden fees?
The total cost can vary considerably depending on the lender, state regulations, loan amount, repayment period, and your eligibility. Possible charges may include interest, origination fees, subscription costs, late-payment penalties, expedited-funding fees, or other service charges. Before accepting an offer, carefully review the annual percentage rate, total repayment amount, due dates, and all fee disclosures rather than relying only on promotional wording.
Is Cash Advance - No Credit Check safe to use with my personal and banking information?
Financial apps may request sensitive information such as your name, address, income, identification details, and bank-account data. Before submitting anything, verify the developer, privacy policy, permissions, customer-support details, and the identity of any lender receiving your information. Avoid sharing passwords or security codes, and never proceed if the app or a linked provider pressures you to pay an upfront fee to guarantee approval.
What should I know about repayment before applying for a cash advance?
Cash advances are usually intended for short-term financial needs and may require repayment quickly, sometimes on your next payday or within a few weeks. Missing the due date can lead to additional fees, collection activity, overdraft charges, or difficulty managing future expenses. Confirm whether repayment is automatic, whether extensions are available, and whether the payment schedule fits your budget before accepting any offer.











