

Cash Advance: Get 250 Fast
4.7FinanceUpdated October 2, 2026
Screenshots
Pros
- Simple application process with minimal paperwork
- Fast eligibility checks can save time in emergencies
- Repayment details are shown before accepting an advance
- Useful for users with limited traditional credit options
- Mobile access makes managing requests convenient
Cons
- Advance fees may make the total repayment expensive
- Approval and available amounts can vary by applicant
- Late payments may lead to extra charges or collection contact
- Not available in every state or for every financial situation
- Requires access to personal and financial information
 Analysis By Mobexer
When an unexpected bill lands between paydays, the appeal of Cash Advance: Get 250 Fast is easy to understand: it presents borrowing as a short, focused process rather than as a full banking experience. I reviewed it as a finance app from KOMPANIIA LORENS PP, and my overall impression is that it is aimed at people who want to explore a cash advance without paying a subscription fee. It is free to install, rated for Everyone, and its straightforward presentation makes it less intimidating than many financial tools.
That simplicity is also the first thing I would approach carefully. A cash advance is not the same as free money, and the app should be treated as a way to review an offer, not as an automatic solution to every cash-flow problem. The useful question is not simply whether it looks quick, but whether the repayment terms fit comfortably into your next budget. In my experience, that distinction matters more than a polished interface.
How quickly the experience feels in everyday use
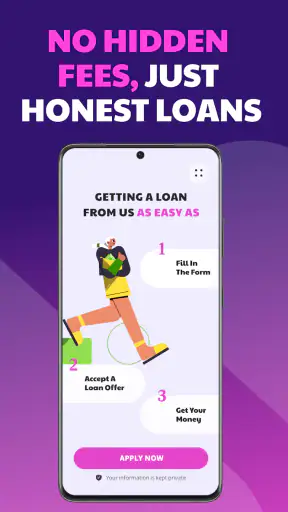
The app’s strongest promise is a short path from opening the service to understanding whether a cash advance may be available. The store summary emphasizes simple steps and no subscription fees, while the short description reduces the idea to “Cash Advance.” That tells me the product is designed around a narrow task instead of trying to replace a current account, budgeting tool, or complete personal-finance dashboard.
For a user in a genuine hurry, the practical advantage is focus. You are less likely to spend time navigating unrelated features before reaching the relevant application flow. I would still avoid assuming that a quick start means instant access to funds. Financial applications commonly depend on information checks, eligibility decisions, and the details of the offer. The app can make the process feel direct, but it cannot turn a careful borrowing decision into something that should be accepted without reading.
A realistic example would be a household facing a utility payment a few days before payday. I would open the app, inspect the available steps, and write down the total repayment obligation before proceeding. If the amount due next payday would leave too little for groceries, transport, or rent, the apparent speed would not make the advance a sensible choice. In that situation, asking the provider for more time or using an existing emergency fund may be safer.
One useful habit is to prepare the information you will need before beginning. Keep your income details, regular expenses, and repayment date in mind, and do not rush simply because the interface is compact. This reduces the temptation to make a decision based on the requested amount alone. The real measure of speed is how quickly you can reach a clear, affordable decision, not how quickly you can tap through screens.
The app has attracted a 4.7 average from around 25K ratings, which suggests that many users find the basic experience approachable. I treat that as a sign of broad appeal rather than proof that every applicant will receive the same result. A smooth experience for one person may not translate into approval, identical terms, or identical timing for another.
What the simple design does well
Keeping the purpose narrow can be helpful when someone is stressed. I prefer a finance app that makes its main action obvious over one that buries borrowing behind a maze of menus. The absence of a subscription fee is another practical positive: you are not paying simply to keep the app installed or to access a recurring membership layer.
There is an important trade-off, though. A focused cash-advance tool is not a replacement for a spending plan. It may help with a temporary gap, but it does not solve the reason the gap appeared. I would use it only after checking the next few weeks of expenses, especially if another bill is due before the expected repayment date.
What happens when the app is used during stressful or heavy moments
“Heavy use” for this app is less about graphics or demanding background work and more about the pressure surrounding a financial decision. Someone may open it repeatedly while comparing options, reviewing an application, or checking whether a request has progressed. In those moments, clarity and stability matter more than visual effects.
Because this is a finance app rather than a game or media tool, I do not expect it to place unusual demands on a modern phone. Its current version is 1.2.2, and the minimum operating-system requirement is Android 7.0. That broad compatibility is useful for people who keep an older device, although an older phone may still feel slower when switching between the app, email, identity documents, or a banking application.
A better workflow is to avoid bouncing between several apps while making the decision. First review the offer and its repayment details inside the finance app. Then compare that commitment with your own notes or budget. Only after that should you move to another service if required. This reduces the chance of losing track of which amount is borrowed, which amount must be repaid, and when the payment is expected.
Another non-obvious point is that repeated checking can create false reassurance. Opening the app again and again does not necessarily make a review happen faster, and it can encourage impulsive acceptance. I would check deliberately, then close the app and return to the figures with a clear head. If the situation is urgent, asking a trusted person to look over the repayment amount can be more valuable than refreshing the screen.
The app is also not the right tool for long-term borrowing. If you need money every month to cover ordinary living costs, a cash advance can become a cycle rather than a bridge. In that case, a nonprofit debt adviser, a bank budgeting service, or a properly structured personal-loan comparison may be more appropriate. Those alternatives may take longer, but they can provide a clearer view of recurring affordability.
Resource demands and older phones
Its minimum Android requirement makes the service accessible to a wide range of devices. That is particularly relevant for users who do not replace phones frequently. Still, operating-system compatibility does not guarantee identical performance on every handset. Older hardware, limited free storage, a crowded browser session, or an unstable connection can make any financial workflow feel slower.
I would keep the phone charged, close unrelated apps, and use a reliable connection before starting an application. Those are simple precautions, but they matter more here than they would in a casual entertainment app. If a screen takes longer to load, do not press the same control repeatedly or assume that a second tap has created a duplicate request. Pause, check whether the page has changed, and allow the process to settle.
People using a small screen should also zoom in mentally, even if the interface does not require actual zooming. Repayment figures, dates, and conditions deserve deliberate reading. A compact layout can make a service feel fast while making fine print easier to overlook. My advice is to read every amount twice and save your own note of the total commitment before confirming anything.
Reliability, recovery, and sensible safeguards
Reliability in a borrowing app has two sides. The first is technical: screens should open, information should remain consistent, and the process should recover sensibly if the connection drops. The second is financial: the user needs confidence that the displayed terms are understood before accepting them. I would judge both, because a stable interface cannot compensate for an unclear obligation.
If the app closes or the connection fails, my first step would be to reopen it and check the current status rather than immediately starting over. I would also keep a private record of what I had already submitted or reviewed. This is a useful recovery habit with any financial service, particularly when using an older phone or moving between Wi-Fi and mobile data.
Do not rely on screenshots alone as proof of an accepted request or completed transfer. A screenshot can help you remember what was displayed, but the important confirmation should come from the app’s own status information or the relevant account record. If something looks duplicated, delayed, or inconsistent, stop before submitting another request. Repeating an action out of frustration is one of the easiest ways to lose control of a financial workflow.
The app has passed the threshold of over 100K installs, so it is not an obscure experiment with no visible user base. That level of adoption, together with its substantial rating activity, makes it easier to see why people are interested in the service. Even so, popularity should not replace personal verification. I would still inspect the exact terms shown to me, confirm the repayment date, and make sure I understand any consequences of missing it.
Recovery also means knowing when to leave the app. If the offer is unaffordable, unclear, or not suitable for your situation, closing the process is a valid outcome. A finance app should support a considered decision, not pressure you into completing one. The fact that installation costs nothing does not mean borrowing carries no cost, so I would separate the free app download from the financial commitment being considered.
Who should use it and who should skip it
I can see the app working for an adult who has a short-term cash-flow problem, understands the repayment schedule, and wants a focused way to review a cash-advance option. It may also suit someone with an older Android phone because the operating-system requirement is not demanding. The simple presentation is helpful for users who do not want a large financial dashboard.
I would skip it if you are looking for investment tracking, bill reminders, credit-building education, detailed spending analysis, or a conventional bank account. Those needs call for different categories of tools. I would also avoid using it to cover a recurring deficit, repay another advance, or fund a purchase that can reasonably wait.
Families should be especially careful with the Everyone content rating. That label describes the app’s general content suitability, not whether borrowing is appropriate for every person or household. The financial decision still belongs with the responsible adult who can understand the terms and plan the repayment.
My performance verdict after weighing speed and control
Cash Advance: Get 250 Fast is most convincing as a focused entry point for reviewing a short-term cash advance. Its free installation, subscription-free positioning, broad Android compatibility, and narrow purpose make it approachable. The strong average rating and growing install base also show that the concept has found an audience.
My reservation is not about demanding hardware or complicated navigation; it is about the risk of confusing a fast-looking process with an affordable one. The app may help you move through the initial steps efficiently, but the responsible part of the experience happens when you slow down and calculate the repayment. That is where I would spend most of my attention.
For the best experience, use it in a quiet moment, prepare your budget first, read the full offer, and keep a record of the commitment you are considering. If the phone struggles, recover patiently instead of submitting repeated requests. If the repayment would make the next payday harder, choose another route. A slower alternative that protects your essentials is better than a quick advance that creates a second emergency.
In short, I would recommend trying this finance app only for a clearly defined, genuinely temporary need, and only when the repayment fits comfortably. I would not recommend treating it as a permanent financial cushion. Used with that boundary, its simple design can be useful; used without it, the very speed that makes the app attractive can encourage a decision that deserves more time.
FAQ
What is Cash Advance: Get 250 Fast, and how does it work?
Cash Advance: Get 250 Fast is a financial app designed to help eligible users explore short-term cash advance options. After creating an account, you may be asked to provide personal, employment, income, and banking information so the service can evaluate your request. Approval, available amounts, fees, repayment terms, and funding speed are not guaranteed and may depend on your profile and participating providers.
Can I really receive up to $250 immediately after applying?
The app’s advertised amount is a maximum, not a promise that every user will qualify for $250. The amount offered can vary according to eligibility requirements, income, account history, and other factors. Even when an application is approved, the time needed to receive funds may depend on verification procedures, your bank, weekends, holidays, and the specific provider handling the advance.
Are there fees, interest, or repayment requirements to consider?
Before accepting any cash advance, carefully review the complete offer shown in the app, including service charges, optional or mandatory fees, interest or annual percentage rate, repayment date, and possible late-payment consequences. Costs can vary by provider and state. A cash advance may be expensive compared with other borrowing options, so only accept terms you fully understand and can repay.
What personal information does the app request, and is it safe to use?
Cash advance applications commonly request sensitive details such as your name, contact information, identity data, employment details, income, and bank account information. Before submitting anything, read the app’s privacy policy and confirm who will receive or share your data. Download the application only from an official store, check the developer information, and avoid entering credentials through suspicious links or messages.
What should I do if I am not approved or cannot repay on time?
Not every applicant will qualify, and the app may connect you with alternatives rather than provide funds directly. If you cannot repay on the scheduled date, contact the applicable provider immediately and ask about available options before the payment is missed. Late fees, additional charges, collection activity, or bank overdraft costs may apply. Never borrow more than you can realistically repay.











