

Borrow Money: Fast Cash Loan
4.7FinanceUpdated October 5, 2026
Screenshots
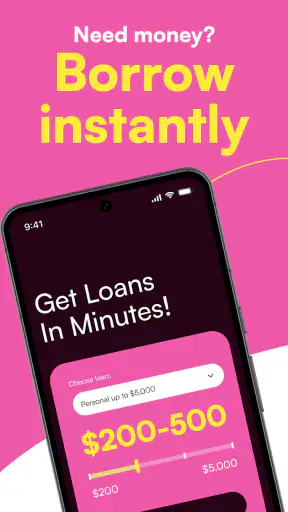
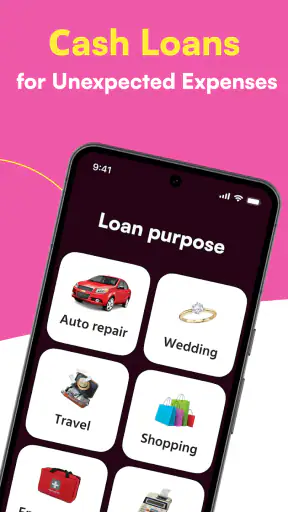
Pros
- Fast application process with minimal paperwork
- Clear repayment schedule shown before accepting a loan
- Useful for handling short-term emergency expenses
- Available application status updates reduce uncertainty
- Simple interface makes loan details easy to find
Cons
- Interest and fees may make borrowing expensive
- Approval and loan terms can vary by applicant
- Late payments may lead to additional charges
- Not suitable as a long-term financial solution
- Availability may depend on location and eligibility
 Analysis By Mobexer
When an unexpected bill lands between paydays, the hardest part is often not deciding that you need help but finding a borrowing app that feels straightforward under pressure. I spent time looking at Borrow Money: Fast Cash Loan, a finance app from Dollar Loan Center, with that exact situation in mind. Its purpose is clear: it is designed to help users request a cash advance through a mobile device, including people who may have limited or poor credit history.
My first impression is that this is a focused tool rather than a full personal-finance system. It is not trying to replace a budgeting app, a bank account, or a long-term debt plan. Its value is in giving you a mobile route to explore short-term borrowing when timing matters. That narrow purpose makes it easy to understand, but it also means you need to judge the borrowing decision separately from the convenience of the app.
The app is free to install and has an Everyone content rating. It has built a noticeable audience, with more than one hundred thousand installs, a 4.7 average from roughly twenty-one thousand ratings, and about one thousand one hundred written reviews. Those figures suggest that many users find the experience useful, although a high store rating should never be treated as proof that a loan is suitable for every financial situation.
How Borrow Money feels when speed matters
The main appeal is the possibility of handling a cash-advance request from a phone instead of beginning with a branch visit or a long search through unrelated financial products. In a stressful moment, that focus matters. I can see the app being useful when a person needs to start the borrowing process during a lunch break, after work, or while dealing with an urgent household expense.
It is important, though, to separate fast application access from guaranteed access to cash. The store summary presents the app as a way to get a cash advance and describes fast loans, even for users with bad credit. That sets an expectation of convenience, not an automatic approval or a promise that money will arrive immediately in every case. Your circumstances, the application review, and the terms shown during the process still matter.
A realistic example would be a renter who discovers that a necessary car repair has to be paid before the next paycheck. The app may offer a quicker starting point than calling several lenders, especially if the person is already comfortable completing financial forms on a phone. The responsible workflow is to open the app, review every displayed condition, compare the repayment obligation with the next few paychecks, and only continue if the full cost fits the budget.
That last step is where many people rush. A quick request can solve a timing problem while creating a larger problem later. I would not use the app simply because the interface makes borrowing feel easier. I would use it only after writing down the amount needed, the date income is expected, and the amount that can realistically be repaid without missing rent, utilities, food, or existing obligations.
What the app is good at in an urgent situation
Its strongest use case is a short gap between a known incoming payment and an unavoidable expense. That is a much narrower situation than “I need more money.” If the expense is recurring, uncertain, or larger than your normal monthly flexibility, a cash advance may only postpone the underlying issue. In those cases, speaking with the bill provider, asking about a payment arrangement, or comparing a credit-union option may be wiser.
The app may also be worth considering for someone whose credit history makes mainstream borrowing difficult. The positioning specifically includes people with bad credit, which makes it more relevant than a conventional lender that relies heavily on a strong credit profile. Even then, poor credit should not be treated as a reason to accept the first available offer. It is a reason to read the terms more carefully.
One useful habit is to take a screenshot or write down the final repayment information before accepting anything, provided the app and the process allow you to review it. Keep the amount borrowed, the total repayment, and the due date together in your calendar or budget notes. This is a small step, but it prevents the common mistake of remembering only the amount received and forgetting the amount that must leave your account later.
Where the speed can feel less impressive
The process may feel fast because the app puts the request in one place, but speed can still be affected by information you need to provide, eligibility checks, identity verification, or the way funds are delivered. I would not plan an essential payment around the assumption that opening the app equals receiving money at once.
This is also why I would avoid waiting until the last possible minute. If the expense is due tomorrow, begin reviewing options as soon as you know there is a problem. That gives you time to understand the offer and look for alternatives instead of accepting unfamiliar terms under extreme pressure.
Using it during heavy financial moments
Finance apps are not “heavy” in the same way as games or video editors, but borrowing situations can still put unusual pressure on the experience. You may be checking the app while switching between messages, bank information, a bill, and a calendar. A useful borrowing tool needs to remain understandable when your attention is divided.
Borrow Money: Fast Cash Loan benefits from having a specific job. You are not asked to navigate a large collection of budgeting dashboards before reaching the reason you installed it. That narrow scope can reduce mental clutter. At the same time, a simple borrowing path can make it tempting to move forward before considering whether the loan is actually affordable.
My advice is to treat the app as two separate tools: first, a way to explore eligibility and available borrowing; second, a prompt to make a repayment decision. Do not let the first step decide the second. If the app presents an offer, pause and compare the total obligation with your real cash flow. The most important number is not just what reaches you today but what you will have to give back and when.
Another practical tip is to use it from a stable, private connection rather than rushing through a request on public Wi-Fi. I am not claiming that the app requires a particular connection or that public networks will cause a problem. This is simply sensible behavior whenever you enter personal financial information. A quiet setting also makes it easier to check names, amounts, and dates before submitting anything.
Handling repeated use
I would be cautious about turning the app into a routine payday bridge. A one-time shortfall and a repeating shortfall are different problems. If you need a cash advance every month for groceries, transport, or basic bills, the borrowing cost can become part of the problem even when each individual request seems manageable.
For repeated pressure, I would first use a basic spending plan, contact creditors about hardship arrangements, and compare longer-term options. A bank overdraft, a credit-union product, or a structured personal loan may be more appropriate in some situations, depending on eligibility and terms. The better alternative is not always the one with the quickest application; it is the one that leaves you with a sustainable repayment plan.
There is also a recovery question after borrowing. Before accepting an advance, decide what will change on the next payday. If the repayment will leave you short again, the app has not solved the cash-flow problem. I find this forward-looking check more useful than focusing only on whether the request itself is easy to complete.
Reliability, clarity, and everyday confidence
The app comes from Dollar Loan Center, and its current version is 0.2.2. The release is relatively early in the product’s version history, so I would keep expectations practical: a focused app can work well while still receiving refinements as more people use it. I would make sure the app is updated through the official app store and avoid relying on an old installation when handling a financial request.
Its public reception is encouraging. A 4.7 average and a large volume of ratings indicate that the basic experience has worked for many people. Written reviews can be especially useful when you are deciding whether the process is understandable, so I would read recent comments for recurring complaints about application flow, communication, or repayment confusion rather than looking only at the headline score.
Reliability in a lending app is more than whether it opens. I also care about whether the information remains consistent from the initial request to the final review, whether I can understand what I am agreeing to, and whether I can keep a record of the transaction afterward. Those are areas where the user should remain alert, because an attractive interface cannot compensate for unclear terms.
Before submitting personal information, I would check that I am using the genuine listing associated with Dollar Loan Center and that the app is installed from the expected store. I would also avoid sharing login details or verification codes with anyone who contacts me outside the normal process. These precautions are not a criticism of this particular app; they are sensible for any financial service accessed from a phone.
Questions I would answer before accepting an offer
The first question is whether the amount requested is genuinely necessary. If the expense can wait a few days, waiting may be cheaper than borrowing. The second is whether the repayment date matches the timing of your income. A loan that is technically affordable over a month can still cause trouble if repayment arrives before your paycheck.
The third question is whether you understand the total cost, not merely the amount advanced. Read the final screen carefully and look for all repayment details shown there. If a phrase is unclear, do not guess. A financial agreement is not the place to rely on assumptions made because you are in a hurry.
The fourth question is what happens if your situation changes. If your paycheck is delayed or another emergency appears, a tight repayment plan may become difficult immediately. I would only proceed if I had considered that possibility and knew what funds would remain after repayment.
Finally, ask whether a different option is better. An employer advance, a trusted family arrangement, a bill extension, savings, or a lower-cost credit product may be more suitable. Borrow Money: Fast Cash Loan is most relevant when those routes are unavailable or impractical and the short-term obligation is still clearly manageable.
Device limits and resource expectations
The app supports Android 7.0 and later, which gives it a broad compatibility range for Android users who keep an older phone. That is useful for people who do not replace devices frequently. It also means the app is not limited to the newest hardware, although compatibility alone does not guarantee the same experience on every phone.
I would expect a finance app with a focused purpose to be less demanding than a modern game or a media-heavy social platform. Still, I would not judge performance only by how quickly the first screen opens. Network quality, device storage, background activity, and the financial-service workflow itself can all affect how smooth the process feels.
If the app takes longer than expected to load, I would avoid repeatedly tapping the submit button. First check whether the screen is still processing, then confirm whether the request actually went through before trying again. Duplicate actions are especially undesirable in a financial workflow. Closing and reopening the app, checking the connection, and reviewing any confirmation screen are safer steps than submitting multiple times.
Older Android devices may also have aggressive battery or background-data restrictions. I would keep the phone charged, close unnecessary apps if the device is struggling, and avoid switching repeatedly between applications while completing a request. These are general device habits, but they matter more when you need to preserve a confirmation message or carefully review a financial screen.
For recovery after an interruption, I would start by reopening the app and looking for a clear status or confirmation before beginning again. If the process was interrupted during a sensitive step, do not assume that nothing happened. Check your messages, account activity, or any available application history, and contact the appropriate support channel if the status remains unclear. The safest recovery is confirmation, not repetition.
My performance verdict for Borrow Money: Fast Cash Loan
After weighing its purpose against the risks of short-term borrowing, I see Borrow Money: Fast Cash Loan as a practical, narrowly focused finance app for people who need to explore a cash advance from their phone. Its strongest points are the direct borrowing focus, the stated attention to users with bad credit, broad support for older Android devices, and a strong public rating from a substantial user base.
I would recommend it to someone facing a specific, temporary cash-flow gap who has already calculated the repayment and wants a mobile starting point. I would not recommend it as a casual source of spending money, a replacement for budgeting, or a monthly solution to income that does not cover essential costs.
The app’s perceived speed is useful, but speed should remain secondary to clarity. A fast request is only a good result when the repayment is affordable and the terms are understood. The same principle applies to stability: a smooth screen and a well-reviewed product are helpful, but they do not remove the need to verify every amount and date.
For me, the best way to use it is deliberately: identify the exact shortfall, compare alternatives, review the full obligation, save the repayment details, and plan the next payday before accepting anything. Used that way, Borrow Money: Fast Cash Loan can be a convenient option for a narrow emergency. Used impulsively, it can make a temporary shortage harder to recover from.
Overall, I would consider it worth examining when traditional borrowing is difficult and time matters, but I would compare it with lower-cost options whenever possible. The app can simplify access to a borrowing request; the user still has to decide whether borrowing is the right answer.
FAQ
What is Borrow Money: Fast Cash Loan, and how does it work?
Borrow Money: Fast Cash Loan is a financial app designed to help users explore short-term borrowing options through a mobile device. After creating an account, you may be asked to provide personal, employment, income, and banking information so the service can assess eligibility. Available loan amounts, repayment periods, interest rates, and approval decisions vary by applicant and may depend on third-party lenders.
Is Borrow Money: Fast Cash Loan a direct lender?
Not necessarily. Apps with this type of service may operate as loan-matching platforms rather than providing the money themselves. Your application could be shared with one or more third-party lenders or financial partners, each with its own requirements, fees, annual percentage rate, and repayment terms. Before accepting an offer, carefully review the lender’s identity, agreement, total repayment amount, and privacy policy.
What information is required to apply for a loan?
The application may request details such as your full name, address, date of birth, phone number, employment status, income, bank account information, and identification details. This information can be used for identity verification, eligibility checks, and connecting you with potential lenders. Only submit accurate information through the official app or website, and check how your data is collected, stored, and shared before completing an application.
How much does borrowing through the app cost?
The cost depends entirely on the offer you receive and may include interest, origination charges, late-payment fees, or other lender-specific costs. A fast approval does not necessarily mean an affordable loan. Compare the annual percentage rate, finance charge, payment schedule, and total amount due before accepting anything. Never rely only on the advertised loan amount, because the final repayment can be considerably higher.
Is Borrow Money: Fast Cash Loan safe to use?
The app should be treated as a financial service, so users should verify its legitimacy before sharing sensitive information. Download it only from an official app store, confirm the developer and privacy policy, and avoid services promising guaranteed approval or requesting upfront payment before reviewing an offer. Also check local regulations and independent reviews, and remember that missing payments may lead to additional charges or credit consequences.











