

Borrow Cash Instantly WeDollar
4.7FinanceUpdated October 5, 2026
Screenshots
Pros
- Fast application process with minimal paperwork required
- Clear repayment details help users understand borrowing costs
- Convenient access to loan services from a mobile device
- Useful for handling short-term financial emergencies
- Simple interface makes navigation easy for new users
Cons
- Approval and loan availability may depend on eligibility checks
- Interest and service fees can make borrowing expensive
- Late payments may lead to additional charges or penalties
- Loan limits may be too low for larger financial needs
- Requires sharing sensitive personal and financial information
 Analysis By Mobexer
Borrowing money through a phone can feel appealing when an unexpected bill arrives and visiting a bank is not practical. Borrow Cash Instantly WeDollar is a free finance app built around that exact situation, presenting instant cash advance options in a simple mobile format. I approached it less like a general budgeting tool and more like a short-term borrowing doorway: useful when timing matters, but something that deserves careful thought before you accept any offer.
The app is developed by Voronkov Moner App and is aimed at an Everyone audience. Its current version is 2.0.2, and it runs on Android 7.0 or later. That broad operating-system support makes it accessible to people using older phones, although the age of a device can still affect how comfortably any finance app runs. The app is free to install, but that should not be confused with borrowing being free. The important financial details are the terms shown during the application process, not the download cost.
What using WeDollar feels like when speed matters
Quick access is the main reason to open it
My first impression is that WeDollar is designed for urgency rather than long-term financial planning. The central appeal is the possibility of requesting a cash advance from a phone instead of arranging a traditional appointment or searching through several unrelated services. That makes it relevant for a person facing a short gap between an expense and their next expected income.
Still, “instant” should be treated as an expectation of a faster application route, not a promise that every request will be completed immediately. A borrowing request can involve eligibility checks, identity information, account details, or other steps before any decision is reached. The practical speed will depend on the individual situation and on what the app asks the user to complete.
I would therefore use it when convenience is genuinely valuable, but I would not open it while rushing through a crowded commute or distracted at work. Financial applications reward careful reading. A few extra minutes spent checking the repayment amount and timing can matter more than saving a few minutes during the initial request.
A realistic everyday situation
Imagine a household whose essential appliance stops working just before payday. The person may not need a broad financial-management suite; they need to understand whether a short-term advance is available and what accepting it would mean. WeDollar can be a practical place to investigate that option from a phone, especially when a conventional bank process feels too slow for the immediate problem.
My advice in that situation would be to prepare the information needed before beginning, read each screen rather than tapping through it, and compare the total repayment with at least one alternative. If the expense can wait, postponing it may be cheaper. If a trusted person, existing bank facility, or employer-supported option is available on clearer terms, that route may be preferable even if it feels less convenient.
Where the app may feel slower than expected
The perceived speed of a finance app is not only about how quickly its screens open. It is also about how much work the user must do, how clearly the next step is explained, and how quickly a decision becomes understandable. A short download does not guarantee a short borrowing process.
That distinction is important with WeDollar because its strongest promise is convenience. If a user expects a few taps followed by immediate access in every case, disappointment is possible. I see the app as a faster starting point for exploring a cash advance, not as a substitute for reading the conditions or confirming that the money will arrive when it is actually needed.
Handling heavy-use moments
Most people will not use a borrowing app continuously throughout the day, but demanding moments can still happen. A user might reopen the app while comparing an offer, switch between it and a banking application, or return after an interruption. Those moments test more than raw speed: they test whether the process remains understandable after attention has been divided.
I find a finance app most comfortable when I can pause without losing track of what I was reviewing. With WeDollar, I would deliberately note the important figures and conditions before leaving a screen. That is a small but useful habit because a financial decision should not depend on remembering a page that was viewed quickly.
Another heavy-use case is repeated checking during an urgent expense. Reopening the app again and again may not improve the outcome, and it can encourage impulsive borrowing. A better workflow is to decide the maximum amount that is genuinely necessary, review the repayment obligation once with full attention, and only then continue. The app may make access convenient, but the user still controls whether convenience turns into unnecessary debt.
Stability and recovery after interruptions
Reliability matters more in a finance app than in a casual entertainment app because an interrupted form can create uncertainty. If a connection drops or the phone receives a call, I would avoid submitting the same request repeatedly without checking whether the earlier attempt was recorded. Duplicate actions are worth treating cautiously whenever money is involved.
My practical recovery routine would be simple: reopen the app, look for the current application status, review any confirmation message, and keep a personal note of what was submitted. If the app returns to an earlier screen, I would not assume that the previous step failed. I would verify the status before starting over.
This is also why I would keep screenshots or written notes of the offer details that matter to me, provided doing so does not expose private information. A record can make it easier to compare the decision later and can reduce confusion if the process is interrupted. That is not a special feature claim about WeDollar; it is a sensible way to use any mobile borrowing service responsibly.
Older phones and everyday device limits
WeDollar supports Android 7.0 and newer, which includes devices that are no longer recent. That is helpful for accessibility, especially for someone who does not replace a phone frequently. At the same time, operating-system compatibility does not tell the whole story. Older hardware may have less free storage, slower multitasking, or a weaker connection, and those factors can make a financial form feel more cumbersome.
I would use the app on a stable connection rather than relying on a weak signal in a crowded place. I would also close unrelated applications if the phone is struggling, not because WeDollar is known to be unusually demanding, but because reducing background load makes any important form easier to complete. Keeping the device updated within its supported limits is another sensible precaution for a finance application.
Resource demands are especially relevant for people using entry-level phones. The app is not something I would judge by gaming-style graphics or elaborate media performance; its value is in completing a sensitive financial task clearly. A modest device should be enough if it can run the supported Android version, but a user with a very slow phone should allow extra time and avoid starting an application when the battery or connection is unreliable.
What the public response suggests
WeDollar has a 4.7 average from around thirty thousand ratings, with roughly one thousand written reviews, and it has passed one hundred thousand installs. Those figures suggest that many people have found the app worth trying, which is useful context when deciding whether it deserves a place among the options you investigate.
Even a strong rating cannot answer the question that matters most to an individual borrower: whether the available terms fit their budget. Ratings often reflect ease of use and general satisfaction, while the financial suitability of an advance depends on personal income, timing, and repayment capacity. I treat the rating as a reason to examine the app, not as a reason to accept money without comparison.
How it compares with usual alternatives
The clearest alternative is a conventional bank or credit-union process. That route may feel slower, but it can offer a more familiar relationship, clearer records, or products intended for longer planning. WeDollar is more attractive when the immediate need is small or temporary and the user values a phone-based starting point. It is less attractive when the borrower needs a substantial amount, a long repayment period, or face-to-face guidance.
Another alternative is a general personal-finance app. Those tools may help track spending, create a budget, or identify where money is going, while WeDollar focuses on access to a cash advance. If the real problem is recurring overspending rather than a one-time timing gap, a budgeting tool may address the cause more effectively. Borrowing can solve an immediate shortage without solving the pattern that created it.
There is also the option of comparing several lending services manually. That takes more effort, but it can reveal differences in total repayment, timing, and eligibility. WeDollar wins on simplicity when the user wants one focused place to begin. It loses some of that advantage if the user treats the first available option as automatically best.
Who should consider it, and who should skip it
I would recommend looking at WeDollar to someone who needs to explore a short-term cash advance, has a compatible Android phone, and is prepared to read the full obligation before agreeing. It may also suit a person who values a mobile-first process and wants to investigate an urgent expense without starting with a branch visit.
I would suggest skipping it if repayment is already uncertain, if borrowing is being used to cover another loan, or if the expense is optional and can comfortably wait. I would also choose a different route when a bank, employer, family arrangement, or established credit option offers terms that are easier to understand and manage. Convenience is not a sufficient reason to borrow.
People often wonder whether installing a free app means there is no cost involved. The answer is no: free installation only describes access to the application. Before accepting anything, I would check the total amount to repay, the due date, any applicable charges, and what happens if repayment becomes difficult. Those details should guide the decision more than the app’s download price.
Another sensible question is whether an older phone can handle it. Since the minimum Android requirement is 7.0, many older devices are included, but performance can still vary. If the phone regularly freezes, loses its connection, or closes applications in the background, I would complete the process on a more dependable device rather than taking a risk with a time-sensitive financial request.
My performance verdict
WeDollar’s performance story is mainly about reducing friction around the first step of a borrowing request. Its free access, broad Android support, and strong user response make it easy to understand why the app attracts attention. I like the focused purpose: it does not pretend that a cash advance is the same thing as a complete financial plan.
My reservation is equally clear. The word “instant” can encourage unrealistic expectations, and no finance app should be used as a shortcut around comparison or repayment planning. The best experience will come from a calm user on a reliable device who knows exactly how much is needed and can repay it on schedule.
For that reason, I see this app as a useful option to investigate rather than an automatic recommendation for everyone. Voronkov Moner App has made a focused finance product available to a substantial Android audience, and the current release, 2.0.2, is accessible on older supported systems. My bottom line is simple: use WeDollar for speed of access, but make the final decision based on the complete repayment obligation.
If you can explain why you need the money, identify the exact amount required, and confirm that repayment fits comfortably into your next budget, the app may be worth considering. If you cannot answer those questions, a budgeting review or a slower, more transparent alternative is the better next move.
FAQ
What is Borrow Cash Instantly WeDollar, and how does it work?
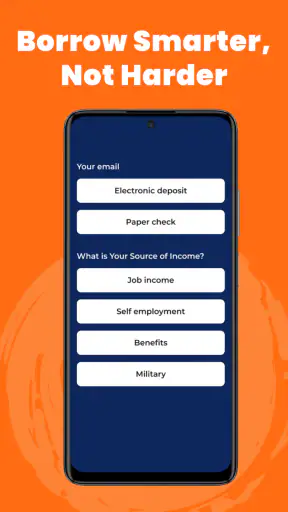
Borrow Cash Instantly WeDollar is presented as a financial app designed to connect eligible users with short-term borrowing options. After creating an account, you may be asked to provide personal, contact, employment, income, and banking information so the service can assess your request. The app may then display available loan offers, but approval, amounts, rates, and repayment terms depend on eligibility and the lending partners involved.
Can I really receive money instantly through WeDollar?
The word “instantly” should not be interpreted as a guaranteed immediate deposit. Processing speed can vary according to your application details, identity verification, approval procedures, the selected lender, banking hours, weekends, and your financial institution. Some users may receive funds quickly after approval, while others may experience delays or may not qualify. Always review the estimated funding time before accepting an offer.
How much does borrowing through WeDollar cost?
The total cost can include interest, origination or service fees, late-payment charges, and other expenses determined by the lender and your location. Before accepting any offer, carefully check the annual percentage rate, finance charge, repayment schedule, total amount due, and consequences of missed payments. Do not rely only on advertising language or the requested loan amount; the final repayment cost is what matters.
What personal information does the app request, and is it safe to provide?
A borrowing application may request sensitive information such as your name, address, phone number, date of birth, income details, identification information, and bank-account data. Before submitting anything, read WeDollar’s privacy policy, verify the official developer and download source, and confirm why each permission is needed. Avoid sharing passwords, security codes, or unnecessary information, and be cautious of requests made outside the official app.
What should I check before downloading or accepting a WeDollar loan?
Before downloading, confirm that the app is available legally in your country, check its current store rating and developer information, and read recent user reviews rather than relying only on promotional claims. Before accepting a loan, verify the lender’s identity, licensing where applicable, repayment dates, cancellation rights, privacy practices, and customer-support channels. Borrow only what you can repay, because missed payments may lead to fees, collection activity, or credit-related consequences.











